Finexer Open Banking Blogs
Screen Scraping: Why UK Firms Must Move to APIs
Screen scraping is under direct pressure after HMRC’s 2026 policy update reaffirmed that browser automation and robotic process automation breach Government Gateway terms. This guide explains what screen scraping is, what HMRC actually said, why regulated APIs already replaced it in banking, and what accounting platforms should audit in their stack now.
Payment Failure: Why It Keeps Happening and What Actually Fixes It
Every payment failure has a specific cause, and most payment failures follow familiar patterns across cards, Direct Debit and bank payments. This guide explains why they happen, how they affect revenue, and what to look for in a payment system for small businesses before failed collections become a recurring operational problem.
Build, Refer, or White Label: The Decision Most Platforms Get to Only Once
Choosing between building bank connectivity in-house, referring customers elsewhere or adopting white label finance solutions comes down to how much regulatory burden a platform wants to keep. This guide explains white label financial services against the other two routes, what regulatory reliance actually means and the criteria separating a strong provider from a weak one.
Alternative Payment Options: Best UK Methods Compared
Cards are not the only option for UK merchants. Alternative payment options -from Open Banking and Direct Debit to digital wallets and A2A -each offer different trade-offs on cost, settlement speed, and chargeback exposure. This guide compares the most relevant UK payment methods so merchants can evaluate what fits their business model.
Open Banking APIs: UK Standards and Specs Explained
Two providers connecting to the same bank can behave differently, even though both follow open banking api standards. This guide explains what the UK Open Banking Standard actually mandates, what is left to each provider’s implementation, and how to read API documentation against the spec before you commit to an integration.
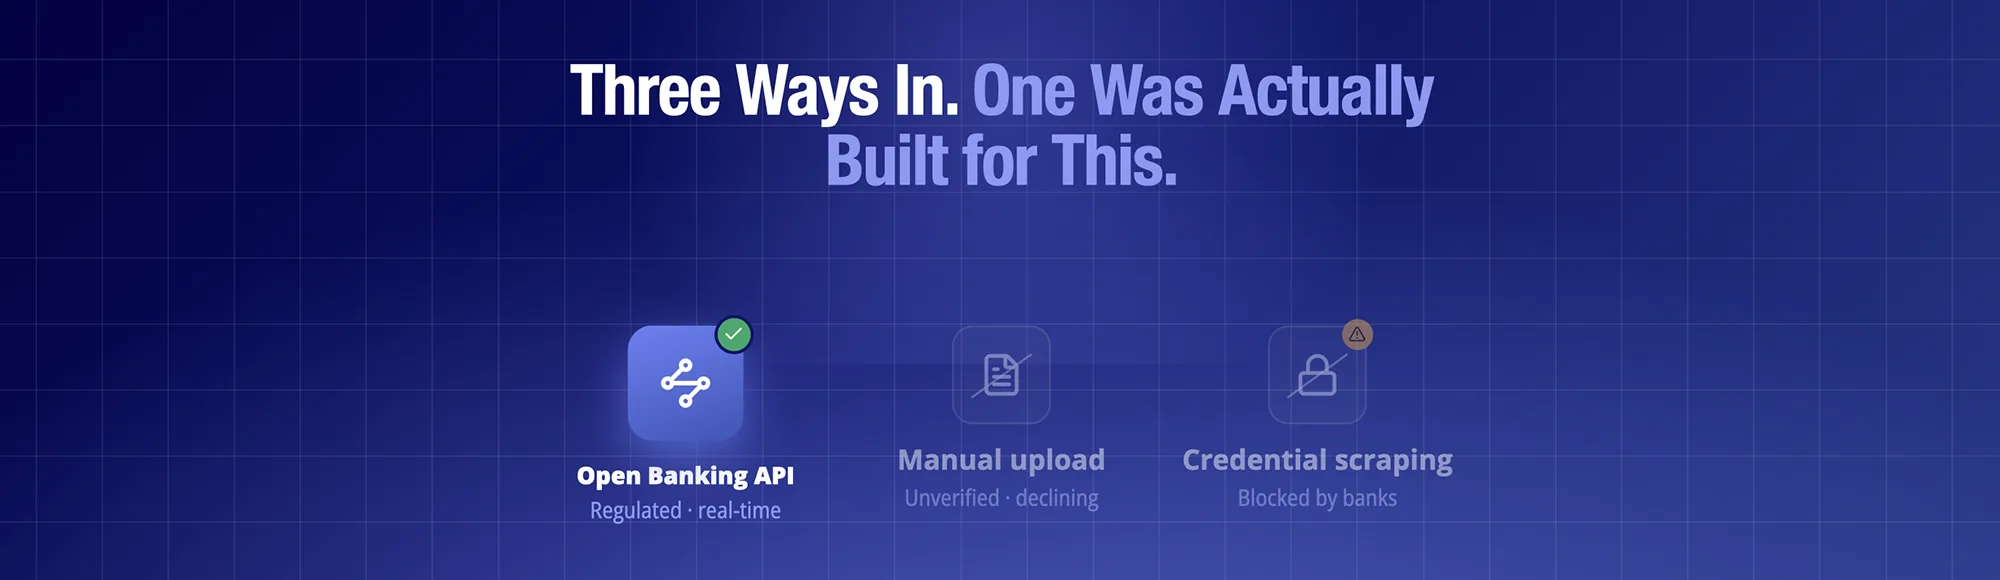
UK Financial Data: Verified Access Routes Explained
UK financial data can be accessed three ways: manual upload, credential scraping, or consented Open Banking connections. Only one is built for regulated, verified access at scale. This guide covers what UK financial data actually includes, how consent works, and what separates a legitimate access route from a declining one.
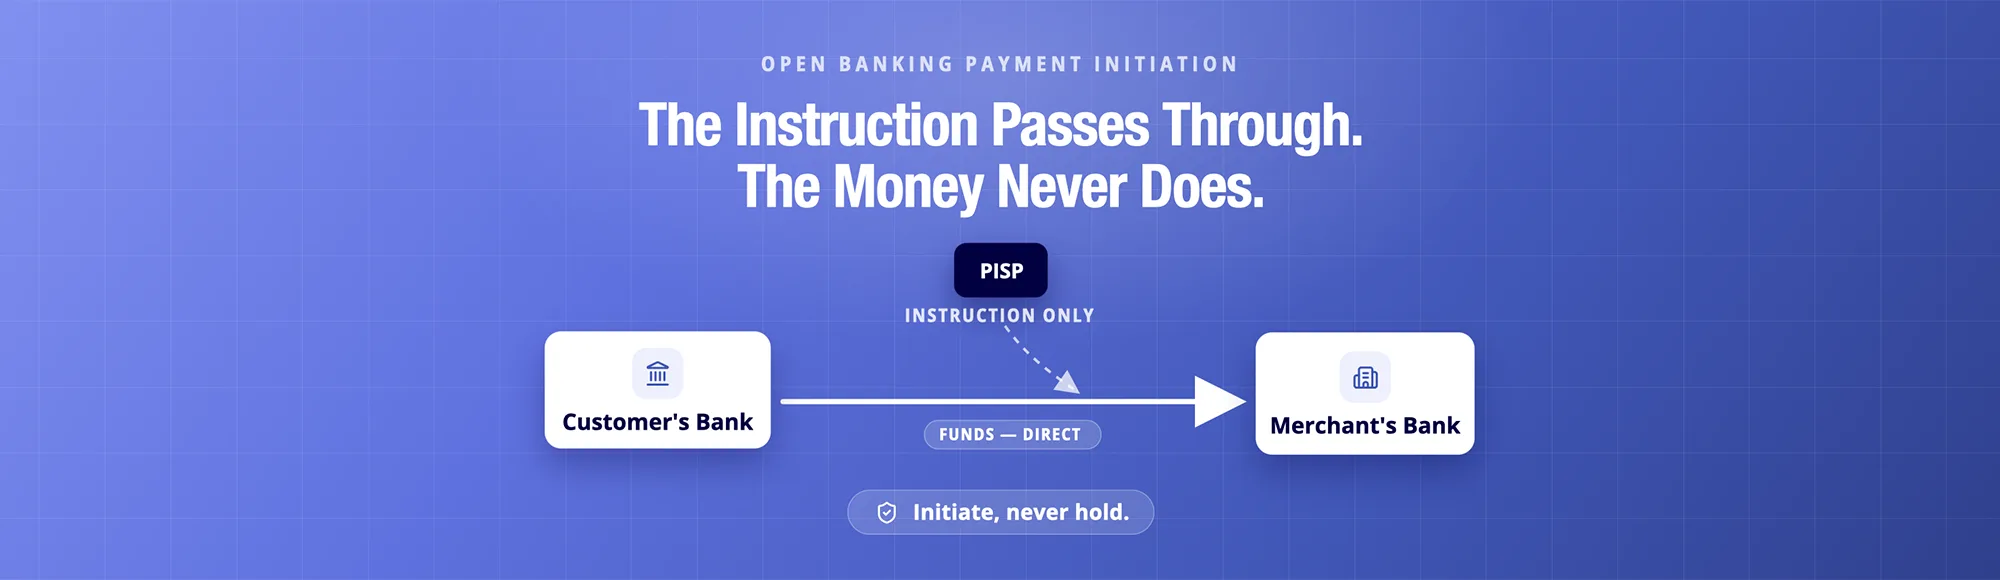
Open Banking Payment Initiation: How PIS Actually Works
Open banking payment initiation lets businesses collect bank payments directly through a regulated payment initiation service, without card networks or intermediaries. Learn how PIS works, how Strong Customer Authentication protects every payment, and what to evaluate before choosing a provider for Pay by Bank integration.
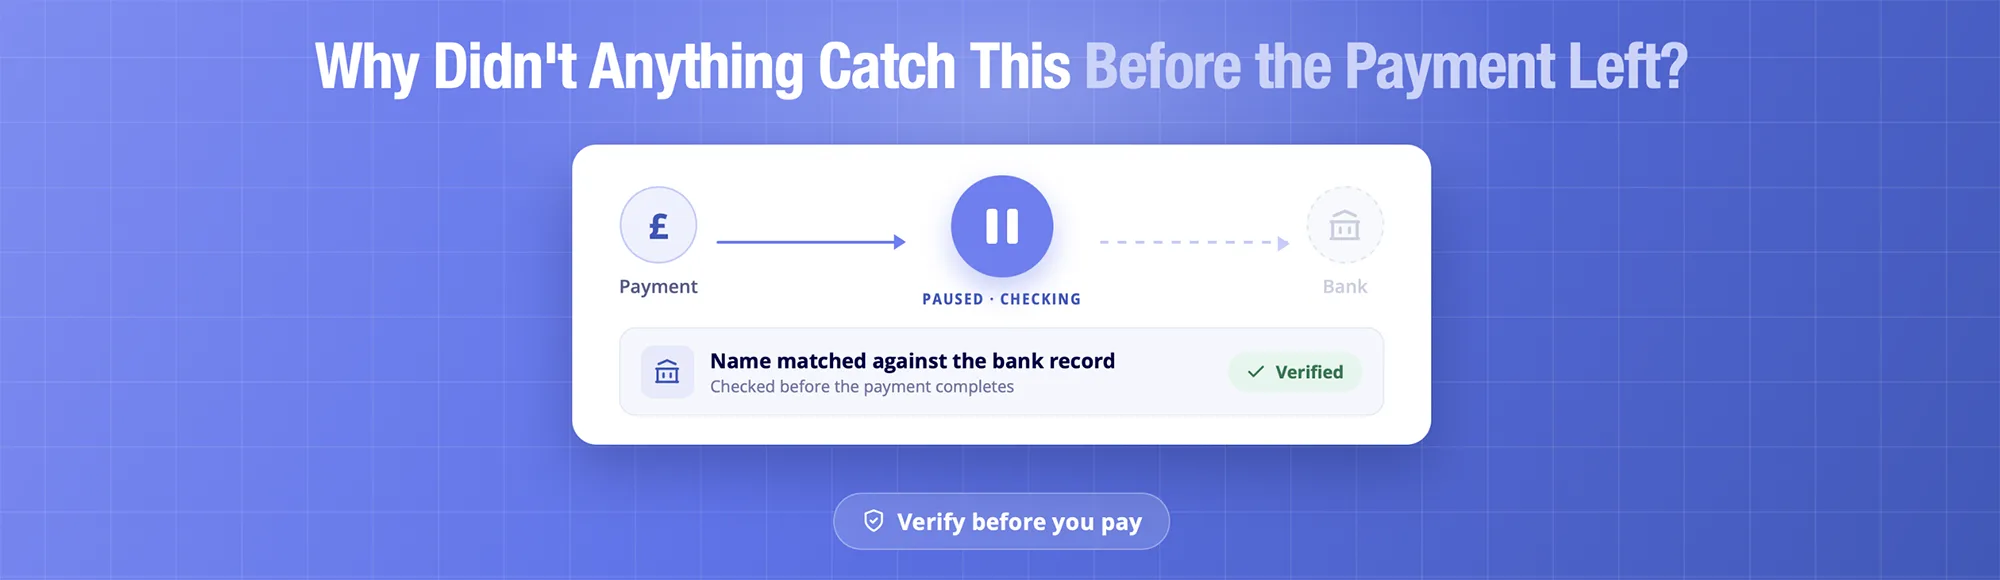
What a Bank Account Verification API Actually Returns
A bank account verification api checks that an account exists and that the name on it matches the expected payee before money moves. This guide covers UK bank account verification match outcomes, full match, close match, no match, where the check belongs in a payment flow, and what to evaluate before choosing an API provider.
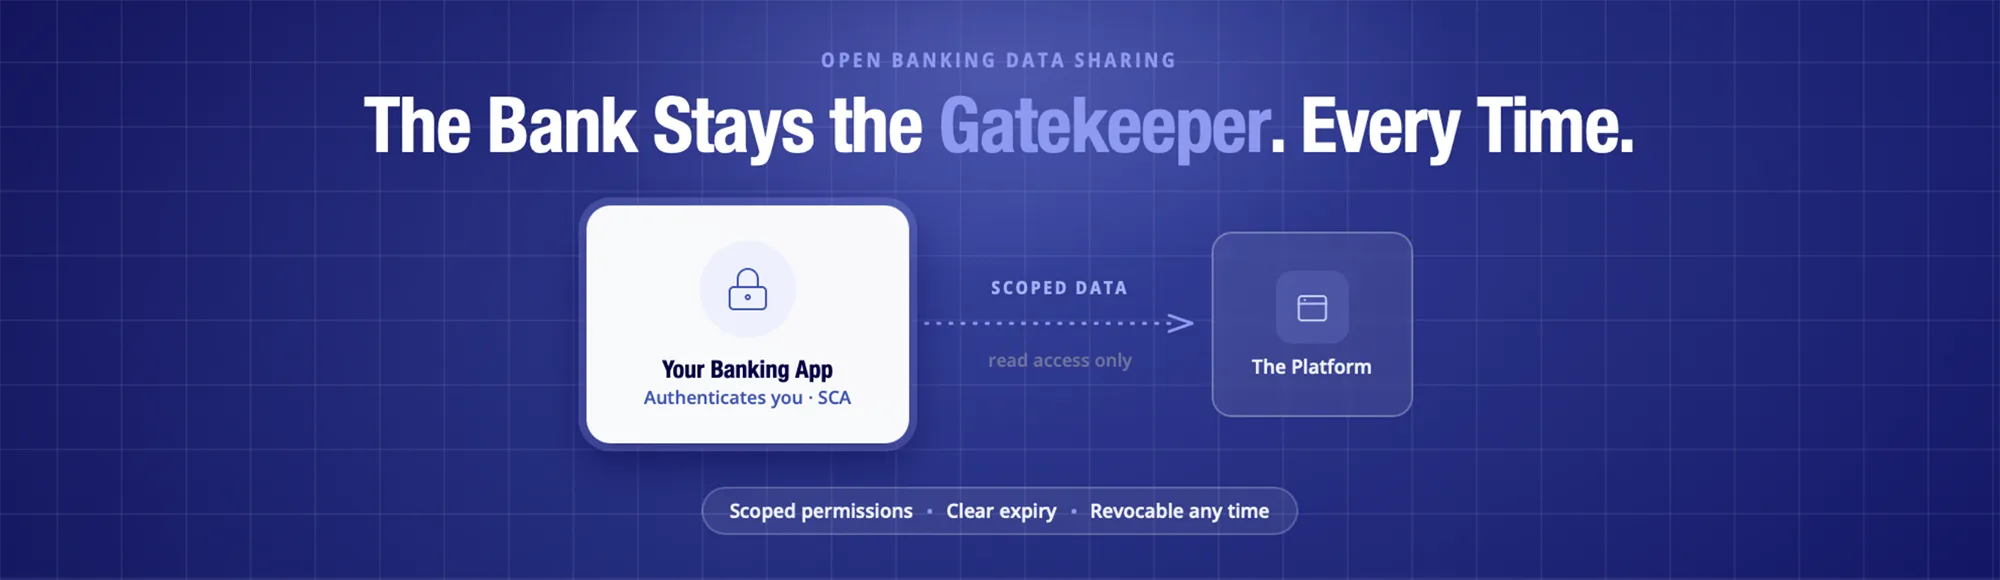
Open Banking Data Sharing: How Secure Consent Works
Open banking data sharing lets customers grant regulated third parties read access to specific bank data, for a defined period, without ever sharing login credentials. This guide walks through the consent journey step by step, what permissions actually mean, and the privacy protections built into the model by design.
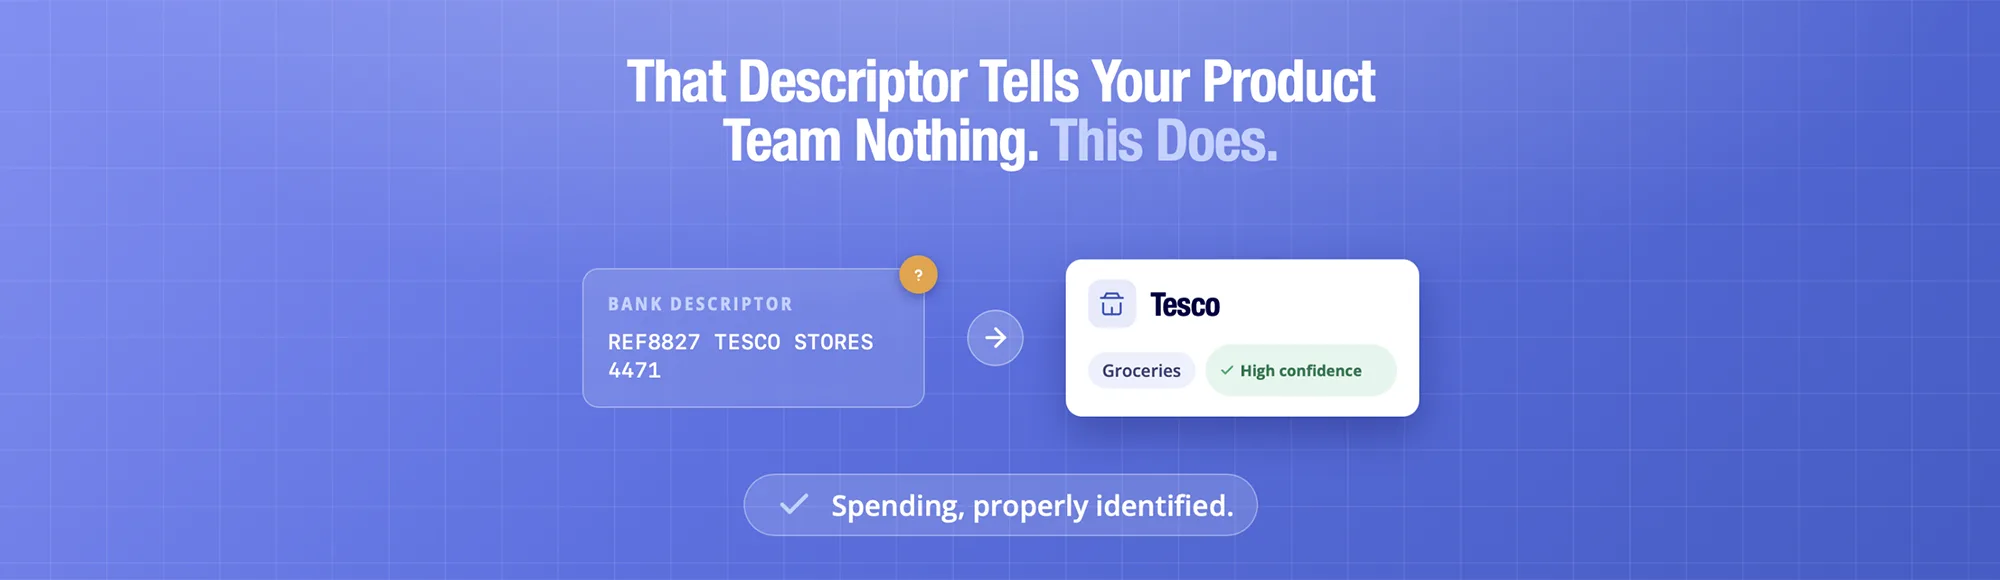
Inside Spending Data: What UK Platforms Actually Build Once the Merchant Names Are Right
Spending data shows exactly where money goes, merchant by merchant, once transactional data is enriched with category, confidence, and location. This guide explains what spending data actually contains, how bank descriptors become usable merchant names, and what UK platforms build with it: budgeting, affordability views, and expense categorisation, without touching lending or credit decisions here.
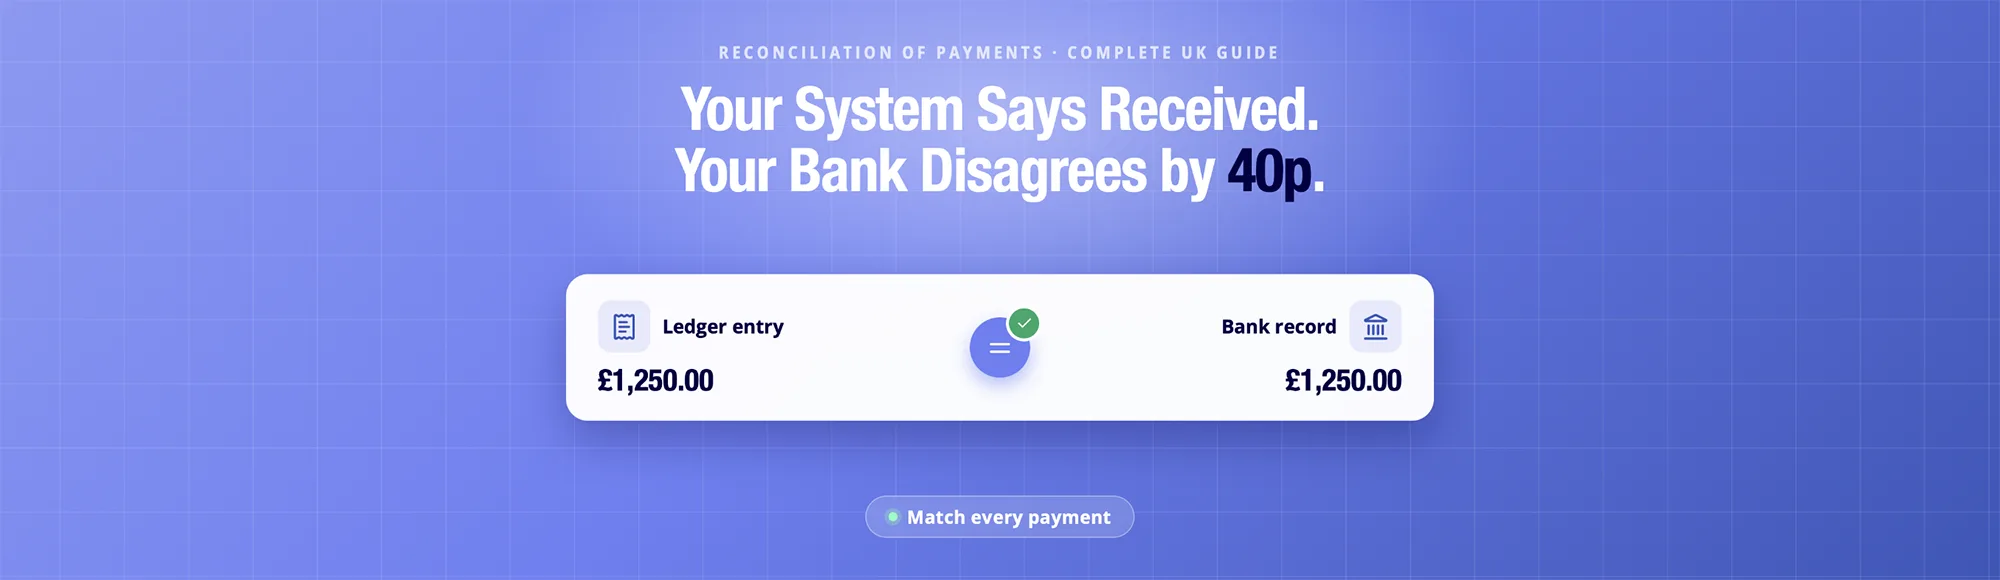
Reconciliation of Payments: The Complete UK Guide for Finance Teams and Platforms
Reconciliation of payments confirms that money recorded in your books has actually moved through the bank, but payment reconciliation still breaks more often than most UK finance teams openly admit. This guide explains what a bank reconciliation statement shows, why matching fails, what makes it solvable, and how platforms build dependable reconciliation of payments today.
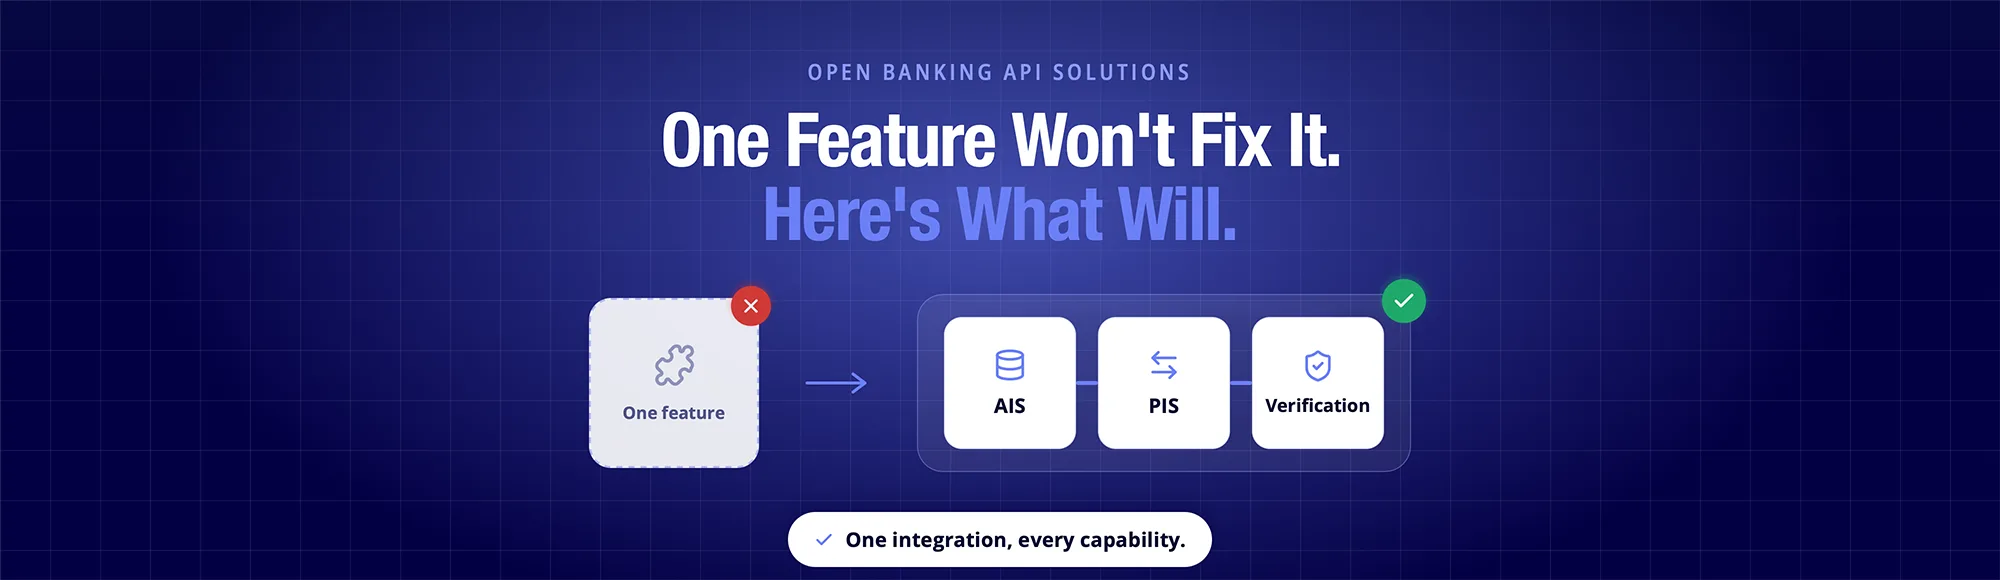
Open Banking API Solutions: Solve Real Business Problems
Open banking API solutions are not one feature. This guide maps specific business problems, manual reconciliation, high card fees, payment fraud, to the exact capability that solves each one, and explains why most real fixes need two or more capabilities working together, not a single API call.
Account Holder Name Check: How UK Verification Actually Works
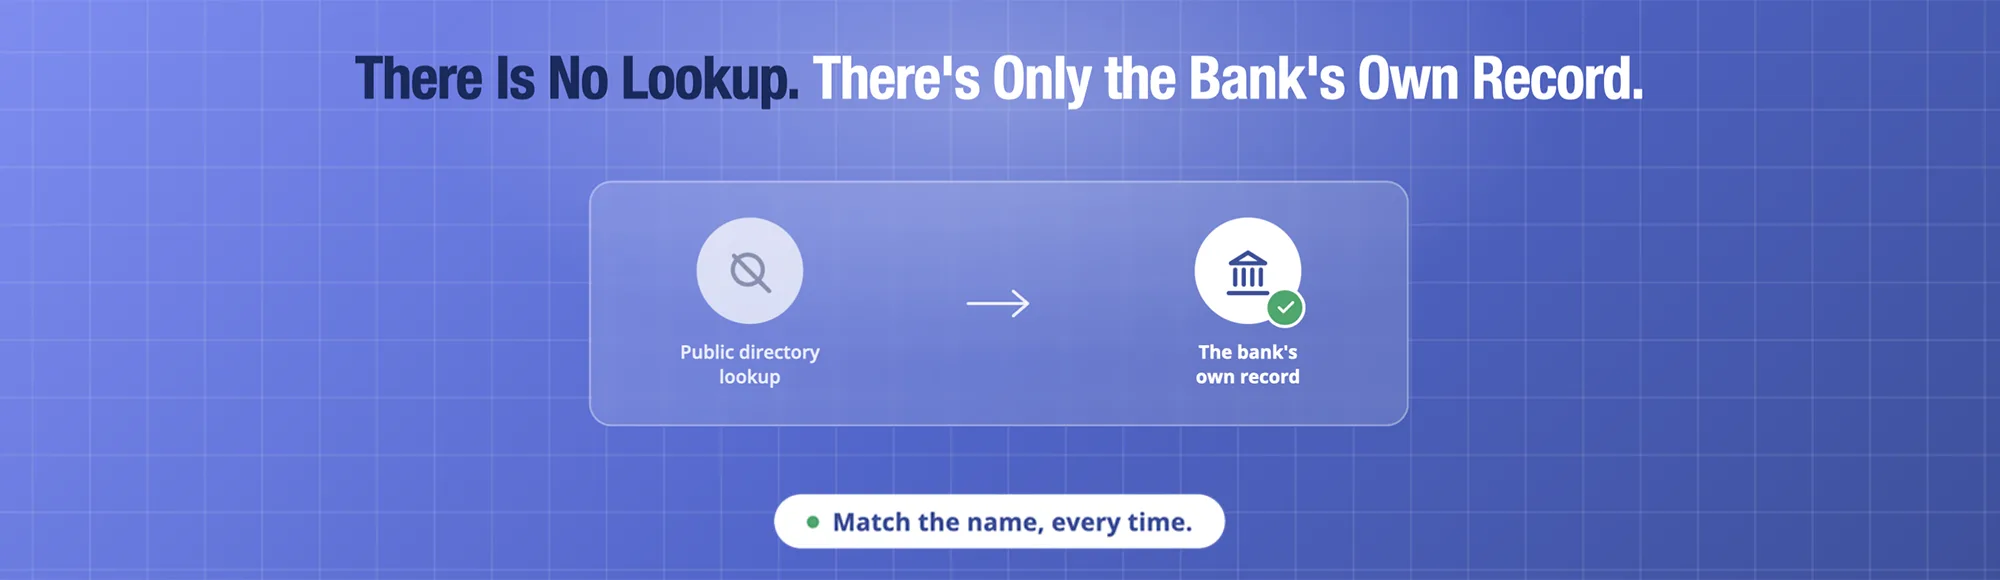
An account holder name check confirms whose name actually sits on a bank account before you pay it. This guide explains how to check bank account holder name details against the bank record, what full match, close match, and no match mean, and where bank account verification belongs in an individual or business payment process.
Open Banking API Examples: Real API Calls Explained
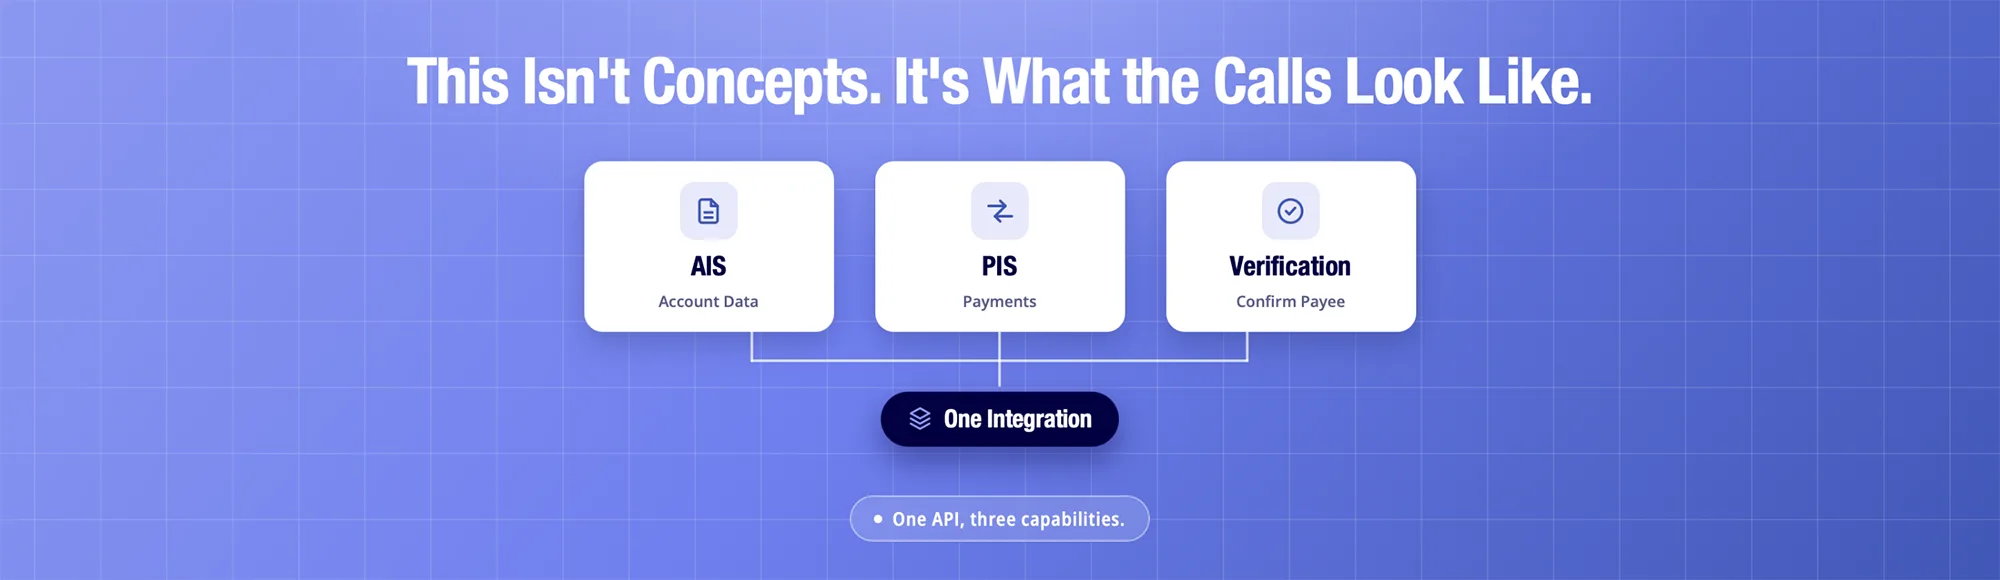
Open banking API examples walk developers through three core workflows: retrieving account data, initiating payments, and verifying account holders. This guide shows real request shapes, response structures, authentication flows, and the integration realities that separate documentation from production code you can actually ship.
Open Banking Payments: A Guide for UK Businesses
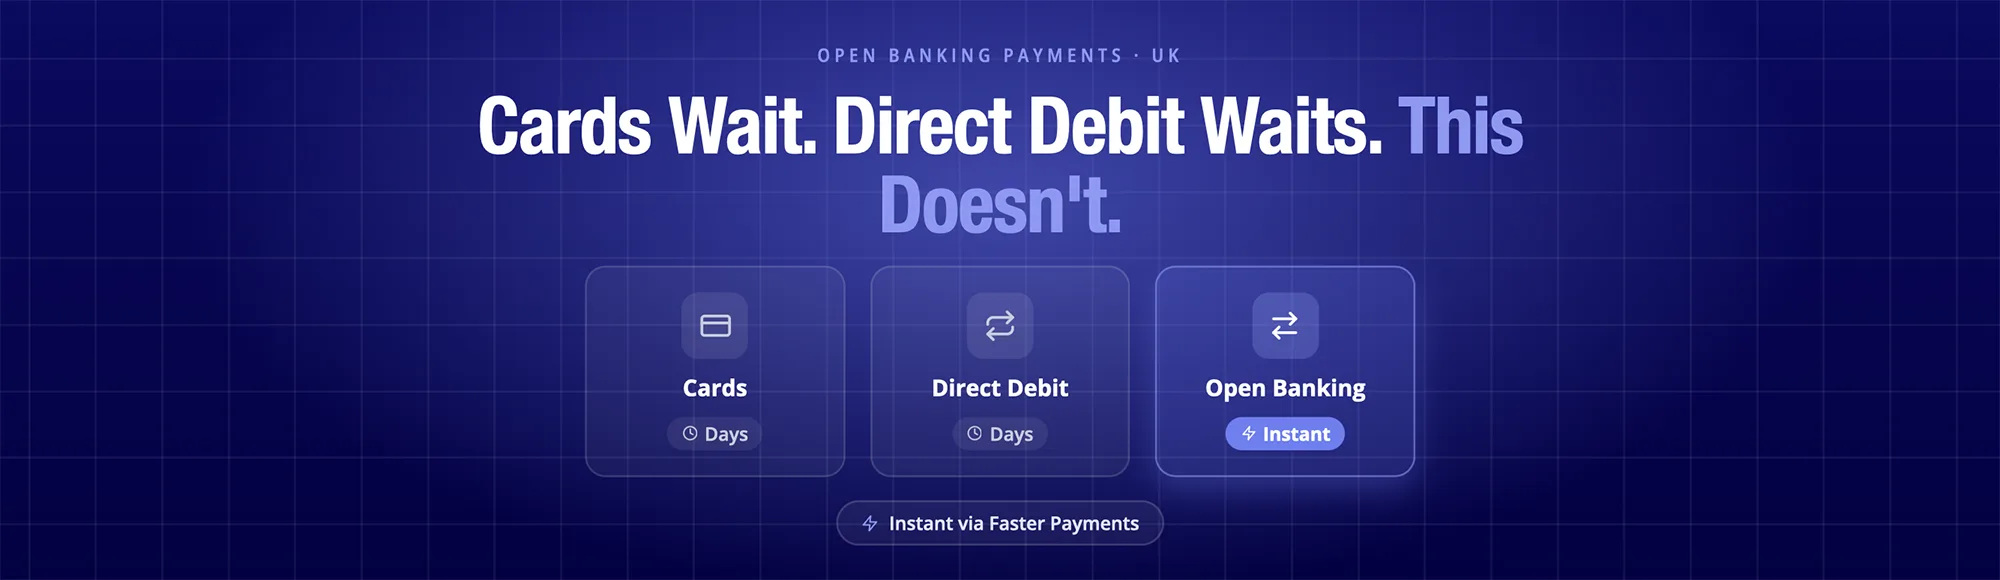
Open banking payments move money directly between bank accounts, authorised by the customer and settled via Faster Payments. This guide explains how they work, compares them with cards and Direct Debit, covers variable recurring payments for subscriptions, and outlines what to evaluate before choosing an Open Banking payments provider.
6 Open Banking API Use Cases: What Developers Actually Build
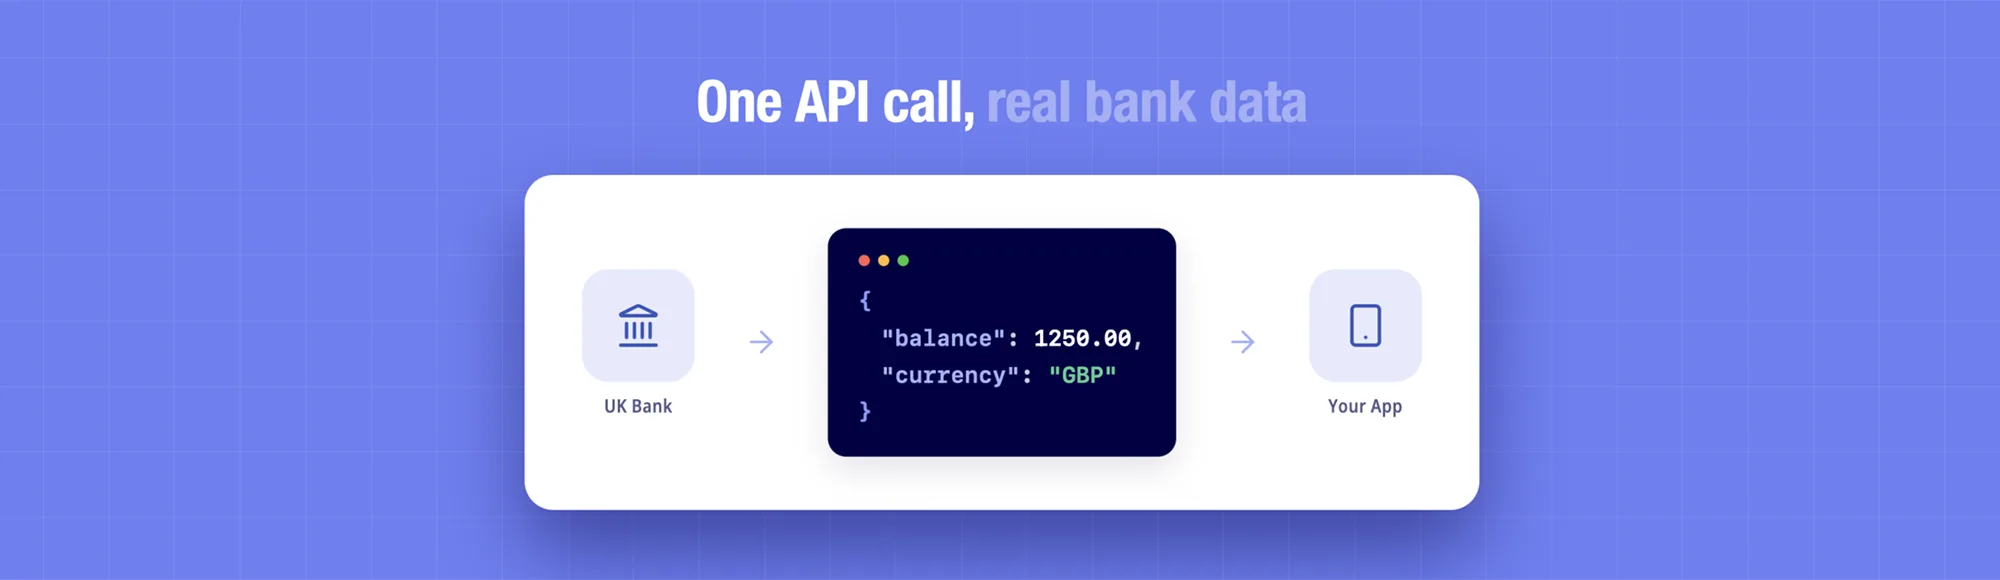
Most guides show business outcomes. This one shows what developers actually integrate. Concrete AIS endpoint structures, PIS payment flows, real data schemas, and worked examples of account aggregation, affordability checks, and Pay by Bank checkouts – the technical depth developers need before writing their first API call.
Invoice Bank Details: What to Include and How to Verify Them Before You Pay
Invoice bank details determine whether a payment reaches the right supplier or a fraudster. This guide covers what invoice details belong on a UK invoice, why invoice with bank details on a document you receive can be altered, and how UK finance teams verify the account name before releasing any payment, cutting redirection fraud risk.
Top 5 Tink Alternatives for UK Businesses in 2026
Searching for Tink alternatives usually starts with a mismatch: you need UK coverage and a fast integration, and an enterprise pan-European platform is more than the job requires. This guide compares five credible options on coverage, deployment speed and bundled capabilities, so that you can shortlist the provider that actually fits your product and timeline.
UK Open Banking Security: 5 Myths About Consent
Open banking security is often misunderstood because many businesses still believe outdated myths about consent and data sharing. This guide explains how open banking API security protects financial information, who controls access, and why regulated APIs provide stronger safeguards than older methods used before Open Banking became widely available in the UK.
Open Banking for Businesses: Why UK Companies Are Adopting It Faster Than Ever
Open banking for businesses gives organisations secure access to current banking data, account-to-account payments and faster financial decisions. This guide explains why open banking for small businesses’ adoption continues to grow, what commercial value it delivers and how to evaluate an FCA-authorised provider before selecting Open Banking infrastructure for long-term growth.
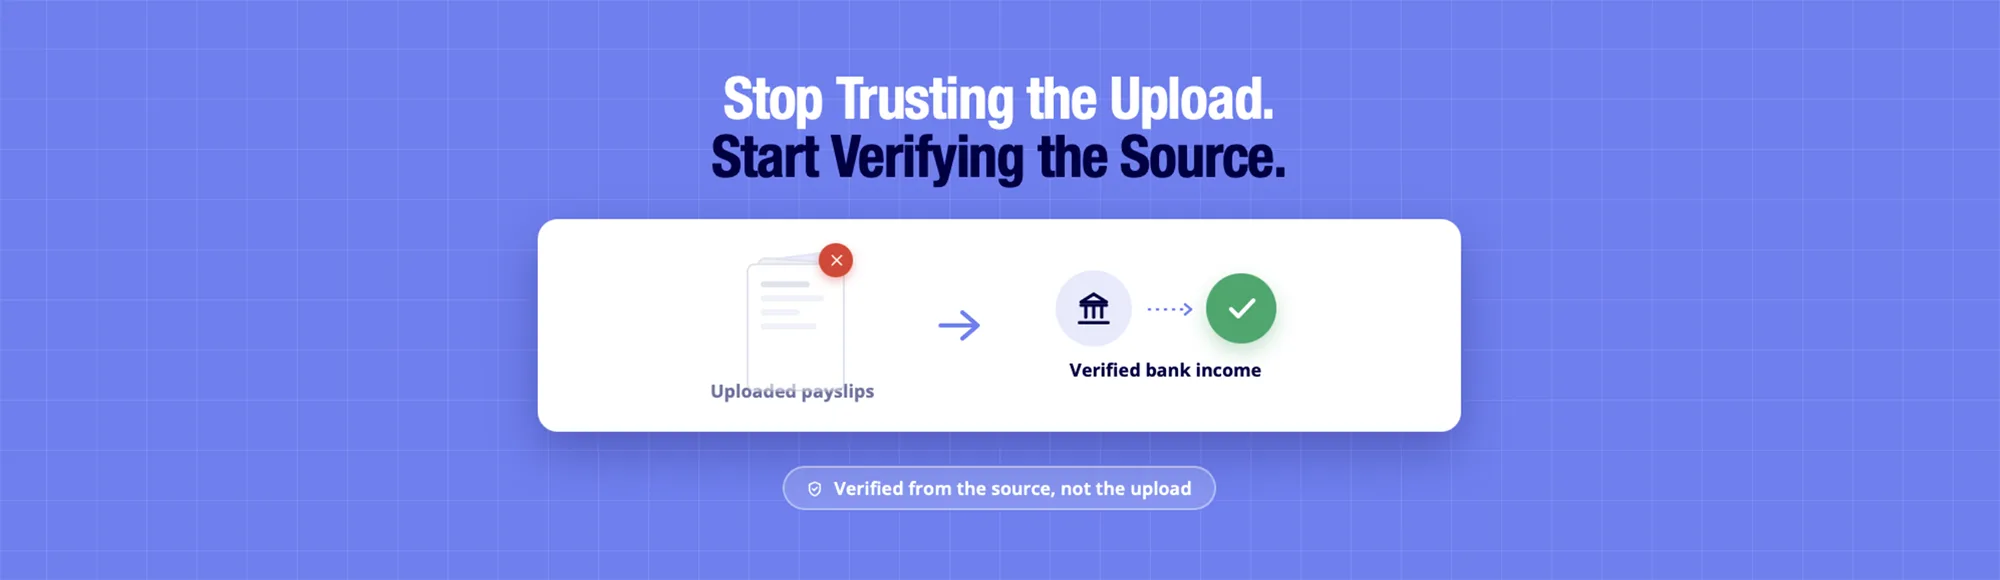
Rent Affordability Check: Verify Tenants with Bank-Verified Data
A rent affordability check no longer has to rely on payslips alone. Learn how bank-verified income strengthens every affordability check rent workflow, reduces fraud, shortens verification times and gives letting agents greater confidence when assessing tenants. Discover why Open Banking is reshaping tenant referencing across the UK property market today.
Transaction Monitoring Process UK: What the Law Requires
Most guides to the transaction monitoring process jump straight to software. This one starts where your obligations actually start: the regulatory text itself. In plain, practical terms, it covers exactly what MLR 2017 and POCA 2002 require, what triggers a SAR, how often monitoring should run, and the documentation HMRC expects to see on file.
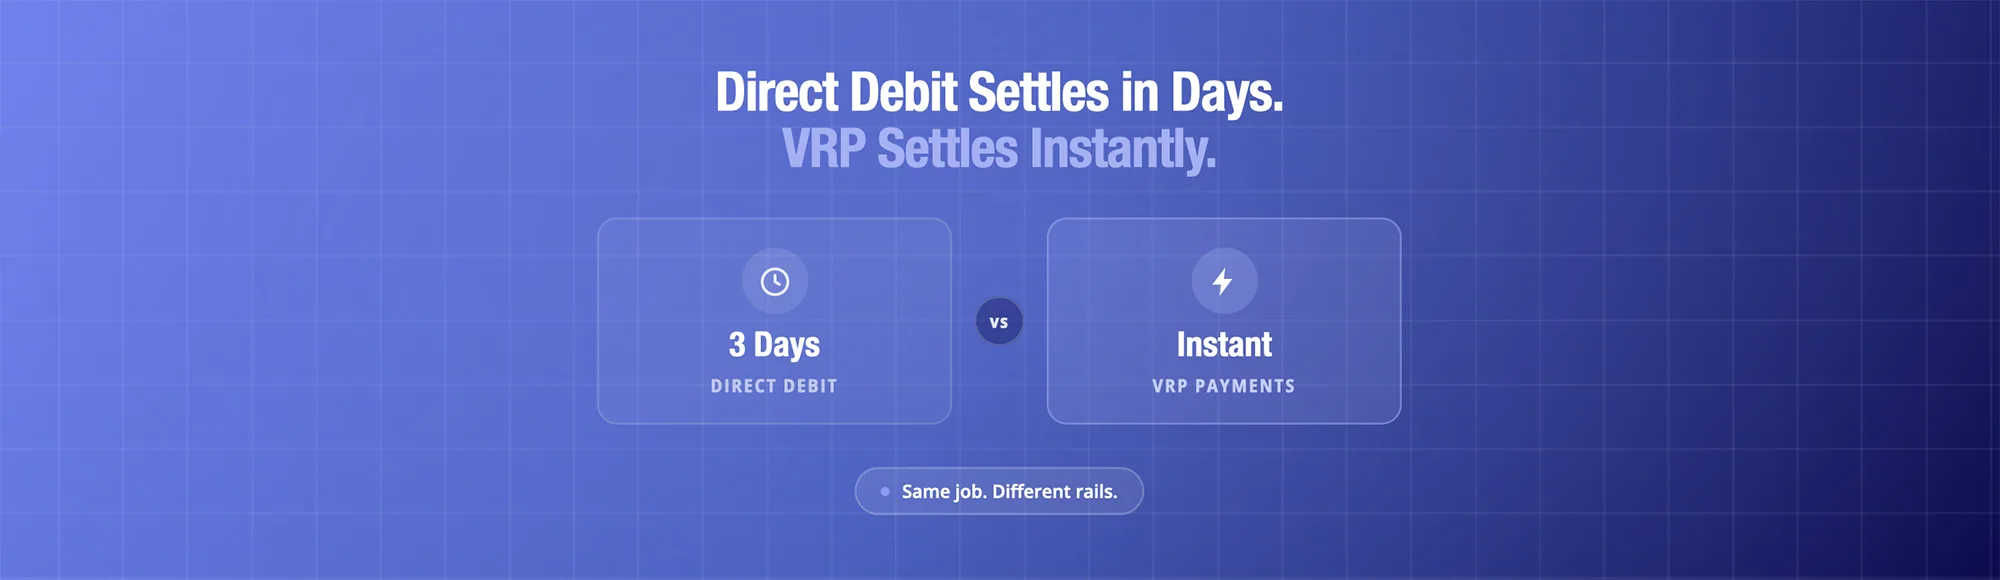
VRP Payments: The Direct Debit Alternative (UK Guide)
VRP payments let customers pre-authorise flexible, bank-enforced recurring payments that settle instantly instead of waiting on Direct Debit’s three-day cycle. This guide explains sweeping versus commercial VRP, which UK banks support, what the FCA and UK Payments Initiative launched in 2026, and what the rollout means for subscription businesses planning their next billing stack.
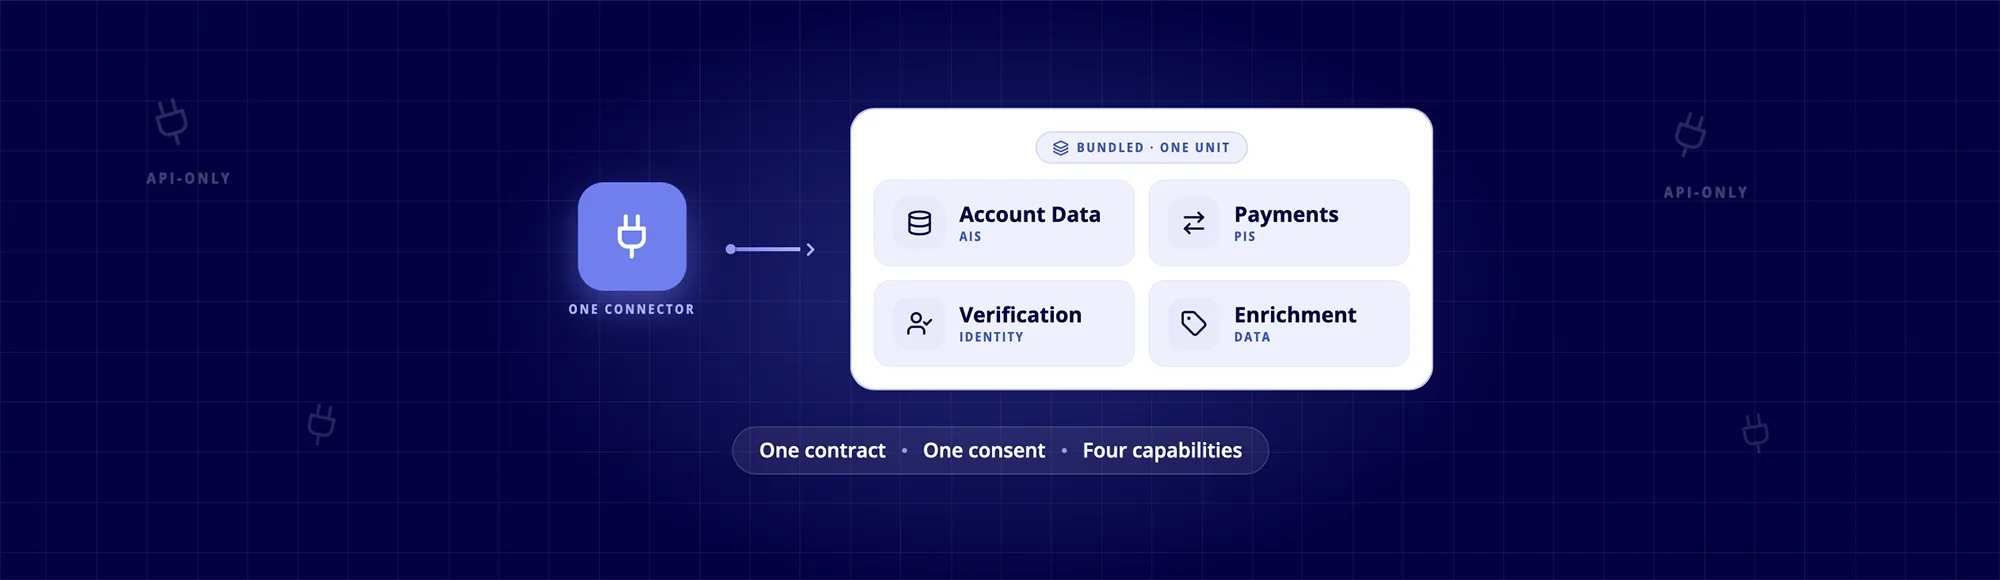
6 Best Open Banking Solution Providers UK 2026
Expense management automation goes beyond OCR receipt capture. This guide compares receipt-only workflows with bank-verified matching, showing how UK finance teams can use real bank transaction data to improve reconciliation, policy checks, GL-code automation, and audit readiness. Learn what to evaluate before choosing an expense management automation solution
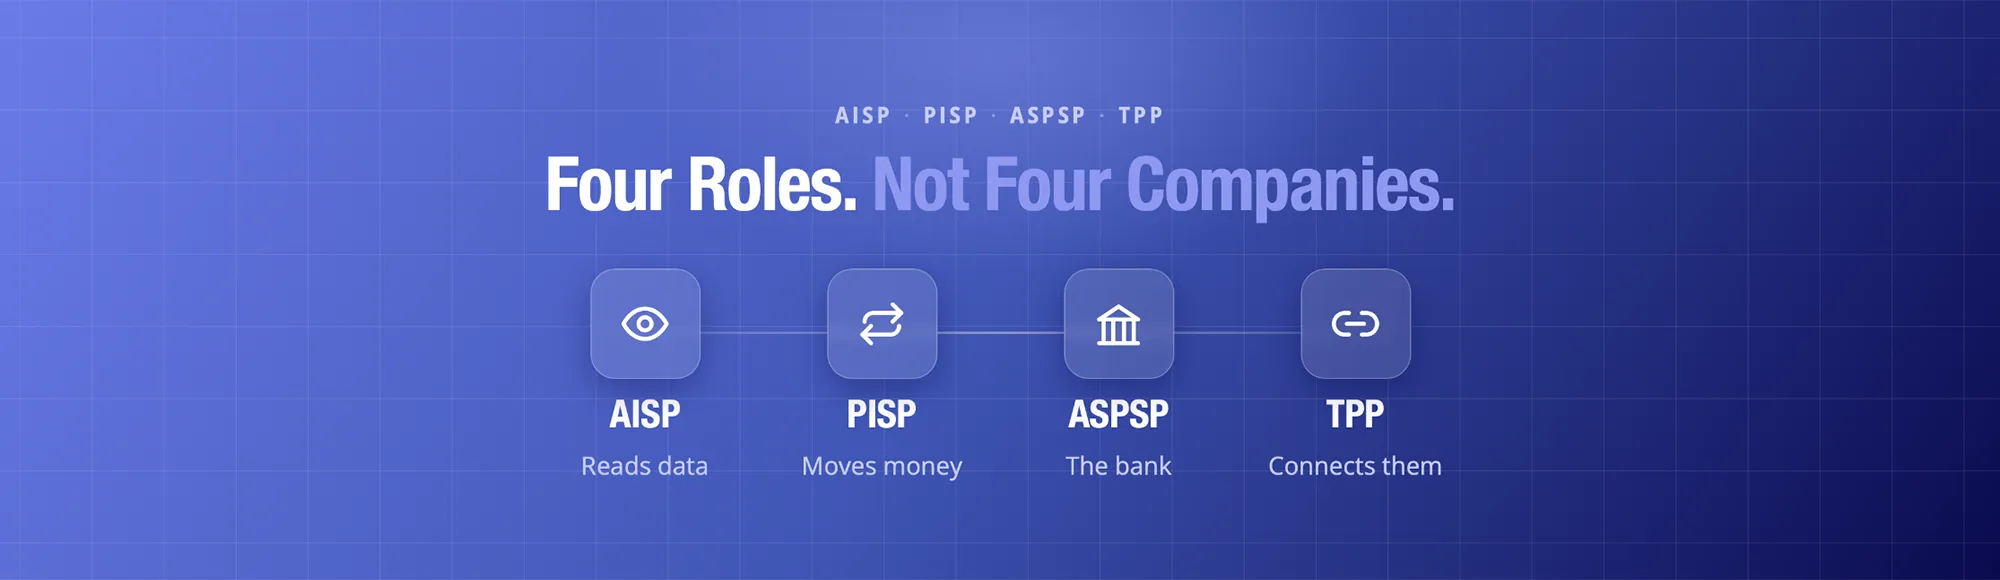
AISP Meaning: AISP vs PISP vs ASPSP Explained (UK)
AISP, PISP, ASPSP and TPP can look like alphabet soup, but the ideas behind them are genuinely simple. This plain-English guide explains what an AISP does, how it differs from a PISP and an ASPSP, why many providers hold both licences, and how to check any UK provider on the FCA register before you integrate.
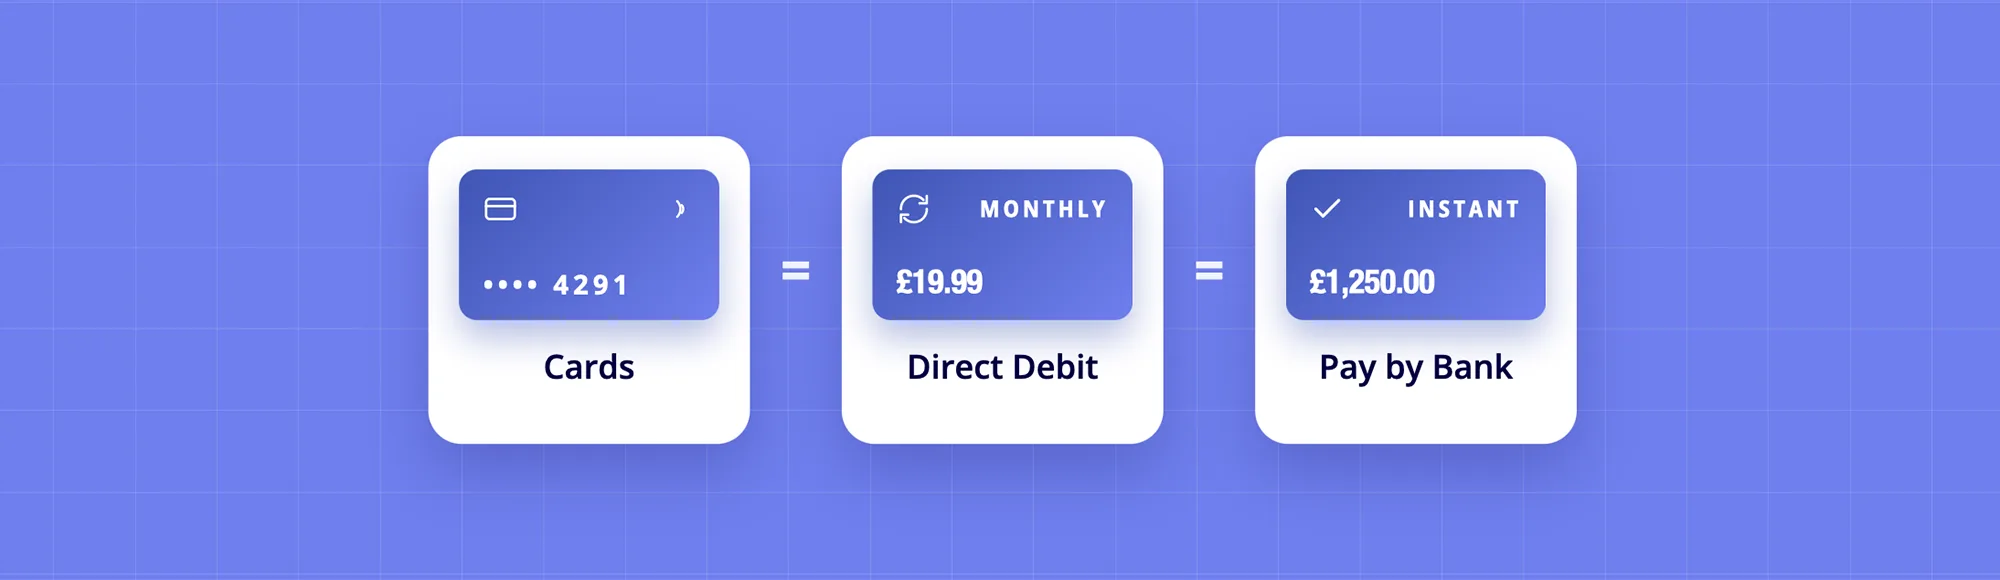
Online Payment Systems UK: Cards vs Bank Transfer 2026
Online payment systems in the UK now span cards, bank transfers, and Open Banking. Each suits different use cases-cards dominate by volume, Direct Debit by recurring bills, and Open Banking by speed. This guide compares all three, so you pick the right system for your business.
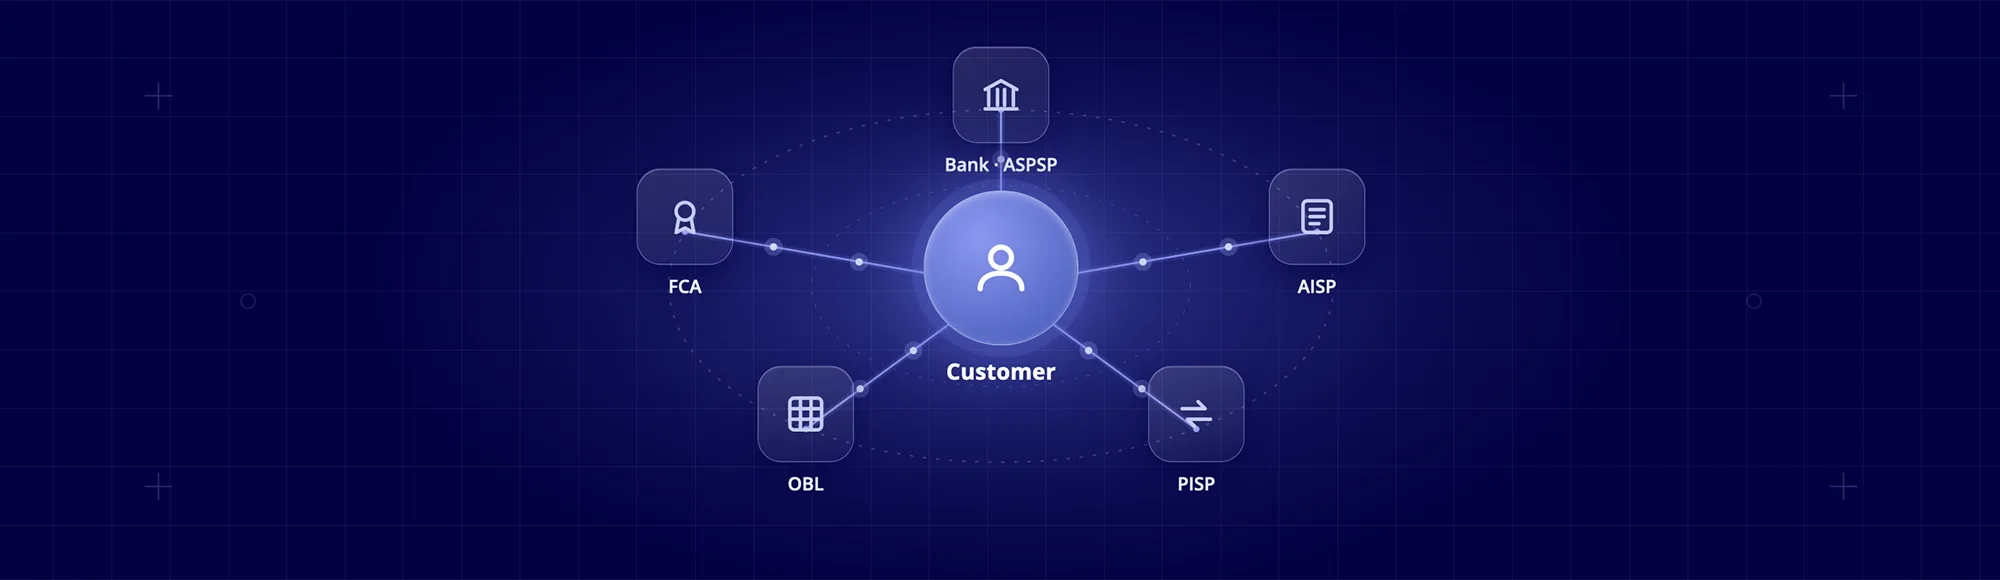
Open Banking Ecosystem: Who the Players Actually Are (and How They Work Together)
Understanding the open banking ecosystem begins with knowing who participates, why they exist and how data moves securely between them. This guide explains banks, AISPs, PISPs, regulators and open banking infrastructure using practical examples, helping buyers understand the UK’s Open Banking landscape without needing multiple resources or technical documentation.
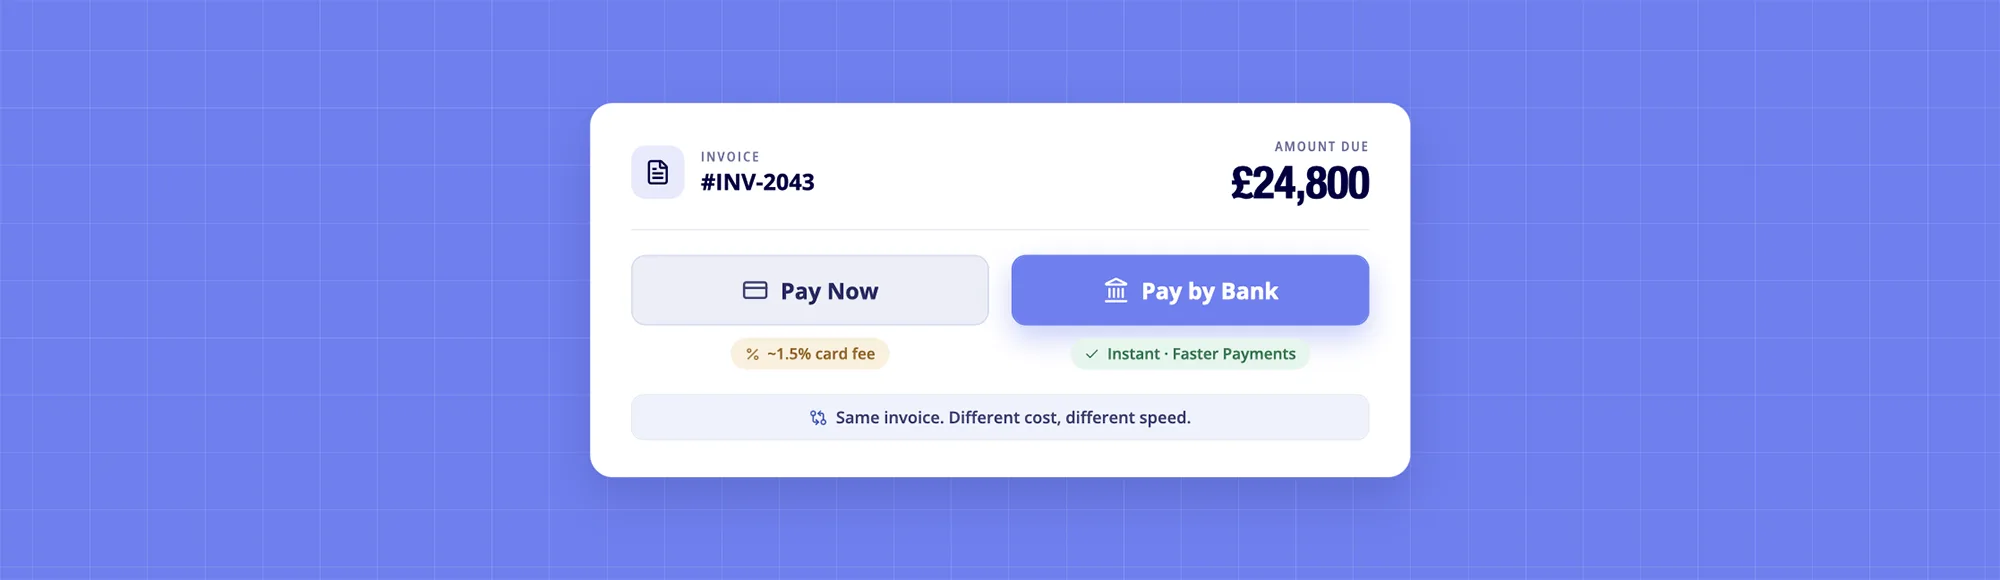
Online Invoice and Payment Processing UK: Beyond Card Fees
Discover how online invoice and payment processing using Open Banking replaces costly card-based Pay Now buttons with Pay by Bank. Learn how automated invoice processing, instant payment confirmation via Faster Payments and bank-data reconciliation reduce manual finance work, lower transaction costs and improve payment visibility for UK SaaS platforms while accelerating cash flow.
Transaction Monitoring Solutions: Scored Evaluation (UK)
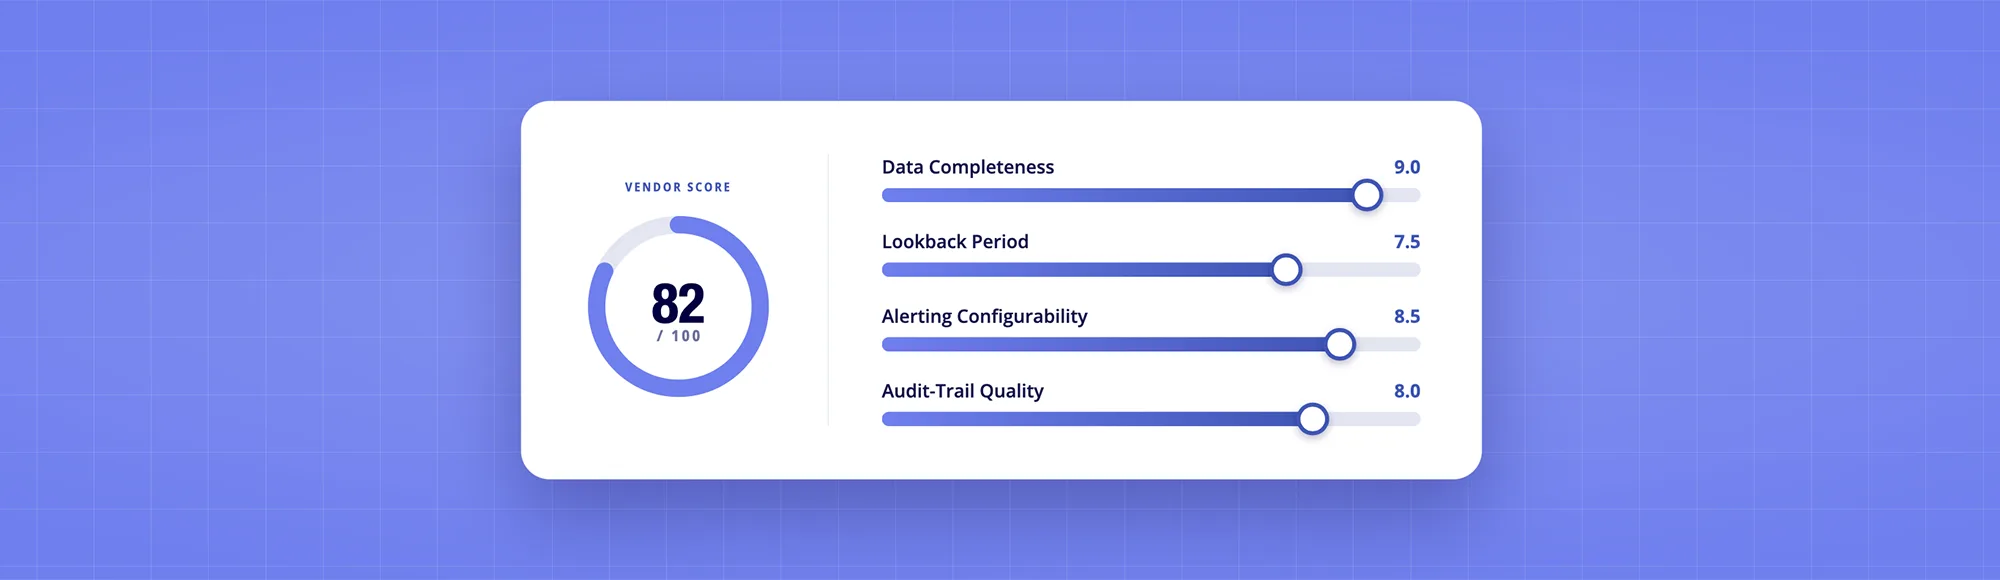
Most transaction monitoring solutions fail because of alert fatigue, not missing features. This guide scores vendors on data quality, lookback depth, alert configurability, and audit trails, helping UK compliance teams compare solutions using practical evaluation criteria and choose one that reduces false positives instead of creating more unnecessary alerts.
Plaid Pricing for UK Startups 2026
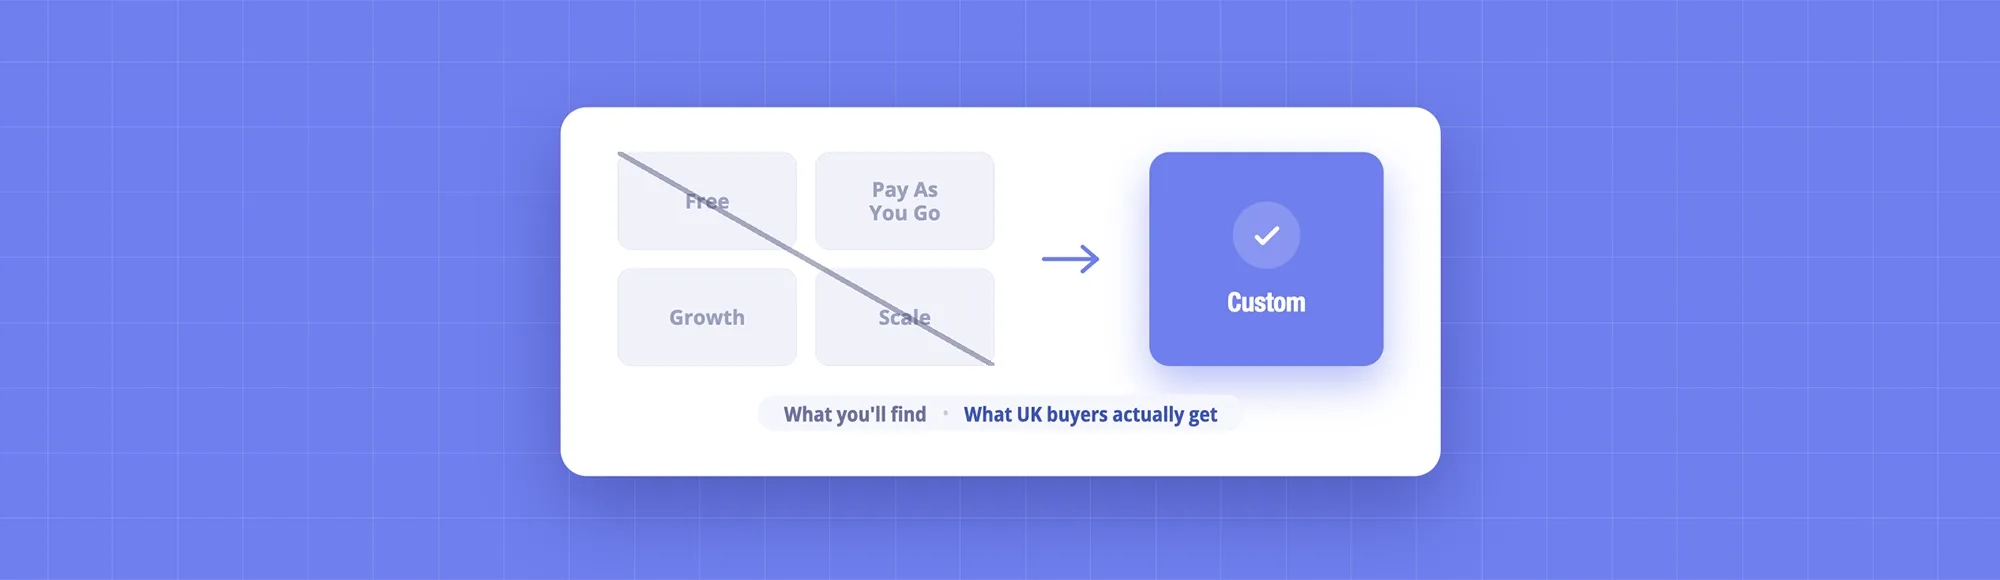
Plaid pricing looks straightforward until UK buyers request a quote. Unlike US customers, plaid api pricing and plaid pricing UK typically require custom contracts instead of self-serve plans. Learn what drives costs, how enterprise pricing works and what startups should evaluate before beginning an Open Banking procurement process with confidence today.