Category: Open Banking
Financial Advisory Services: Client Data Without Chasing
Financial advisory services firms need a current client financial picture without repeated statement requests. This guide shows how consented account access can replace document chasing, support corporate financial advisory services across multiple accounts and give platforms a stronger foundation for Open Banking financial services while keeping data quality, consent, coverage and regulatory requirements in view.
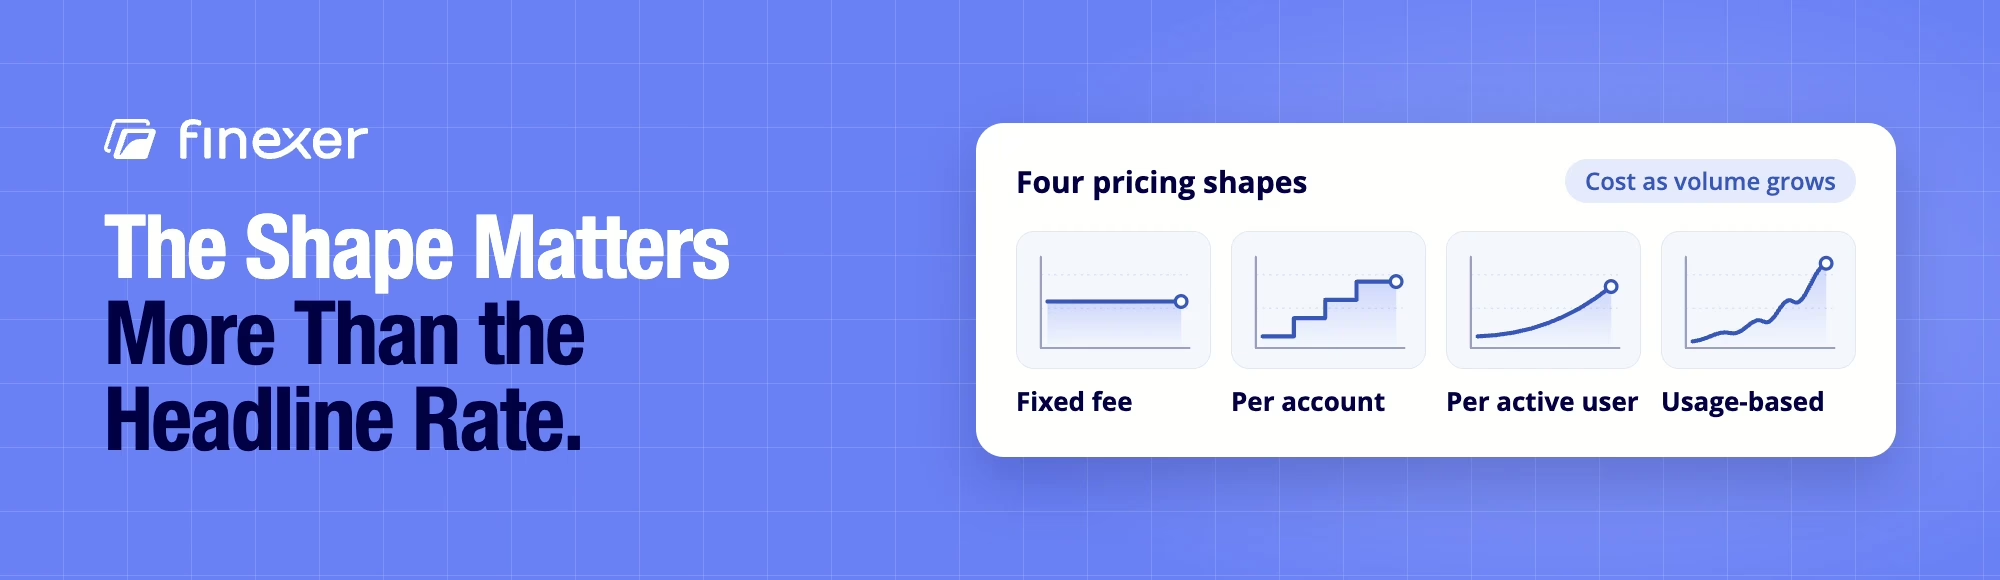
What pricing models do UK Open Banking providers use?
UK Open Banking providers use four pricing models: flat monthly fee, per connected account, per active user, or usage-based. Open banking pricing models differ in how they scale with volume, not what they claim to include. Here’s how to work out which structure actually fits your business.
Open Banking APIs for Developers: A Verified Build Guide
Which open banking APIs for developers are worth building against? The answer depends on documentation completeness, sandbox-to-production parity, auth model transparency, webhook reliability, and security handling,not marketing claims. This guide gives developers a verified audit framework before committing to a UK open banking integration.
Is Finexer suitable for a startup or only enterprise?
Finexer for startups means an agent route, sandbox access before contract, hands-on onboarding, and transparent pricing with no hidden charges. Built to work at enterprise scale too, here’s what a startup actually gets, what Finexer doesn’t do, and who it suits less well.
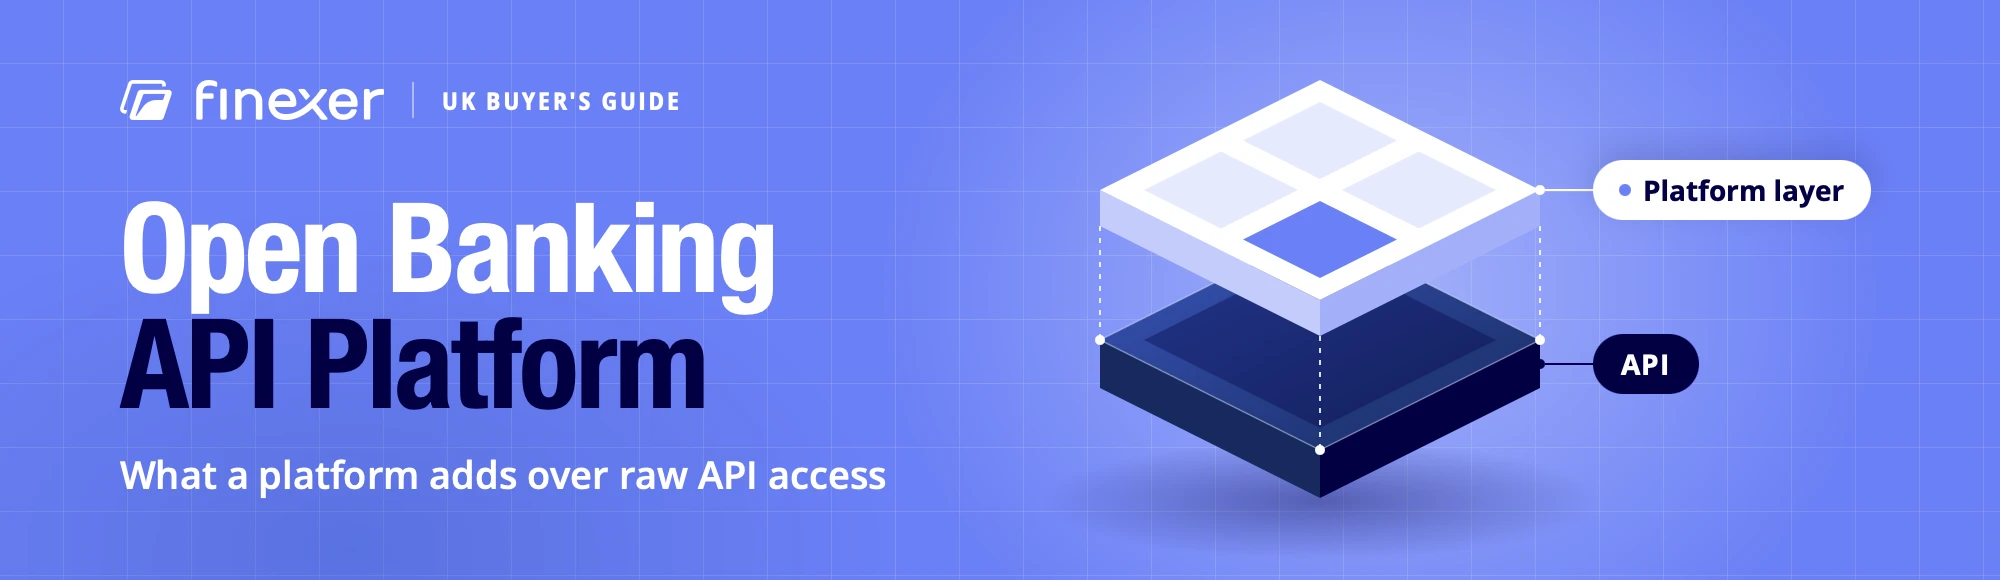
Open Banking API Platform: Complete UK Buyer’s Guide
An open banking API platform bundles the API with consent management, connection monitoring, dashboard visibility and support, the operational layer raw API access doesn’t include. This guide covers what a platform actually adds, who needs one versus who’s fine with an API alone, and how to verify a provider’s FCA authorisation before choosing.
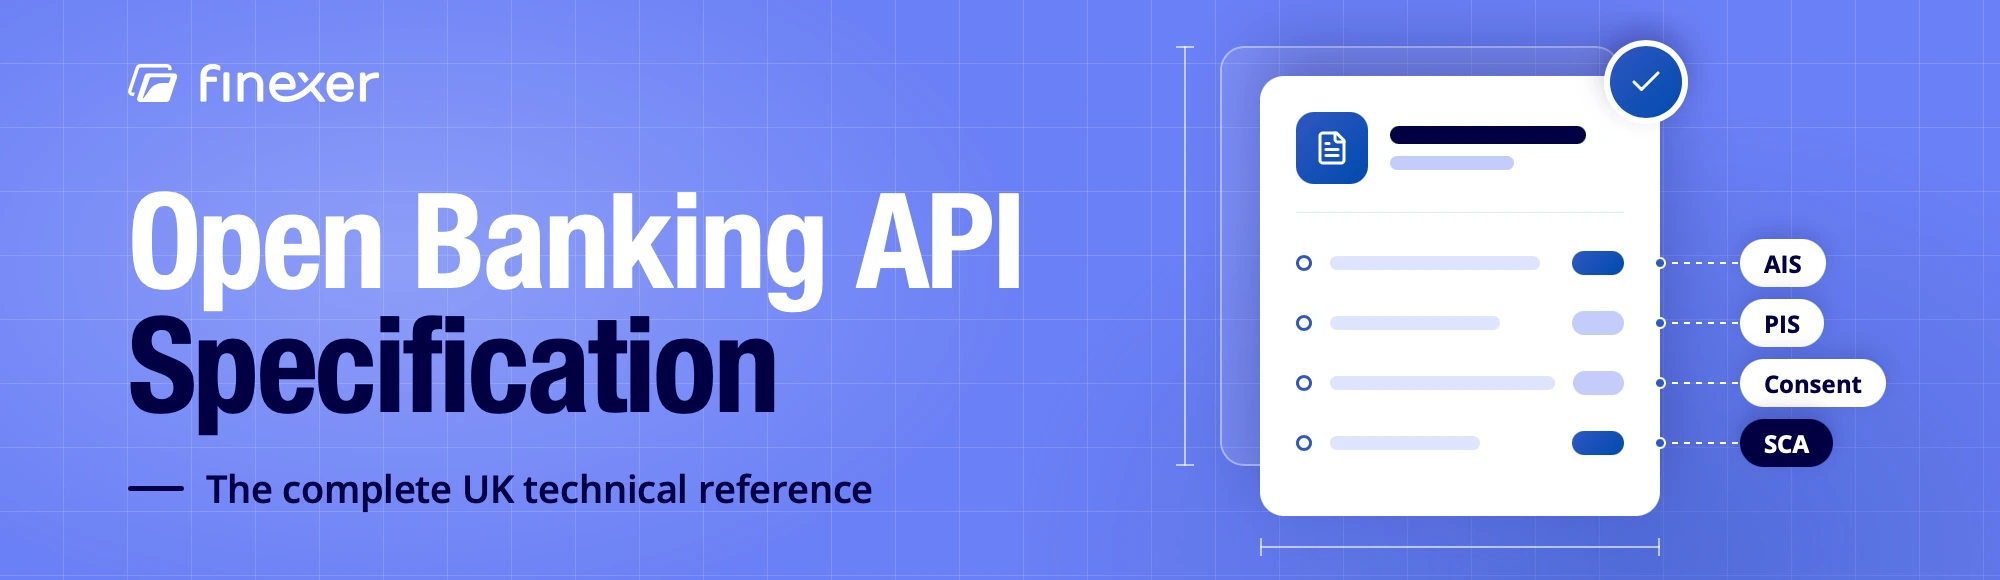
Open Banking API Specification: Complete UK Reference
The open banking API specification gives build teams a consistent contract across every UK bank. This reference covers AIS and PIS endpoint structure, consent model fields, SCA requirements, the PSD2-to-specification mapping, and versioning, so architects and compliance engineers have the detail needed before integration begins.
Client Money Protection Providers: Essential UK Guide
Letting agents in England who hold client money must belong to an approved, government-recognised client money protection scheme. This guide covers what “client money protect” actually means, the current approved client money protection providers, what day-to-day compliance genuinely requires and where clean, current client account data makes proving compliance considerably easier, not just theoretically sound.
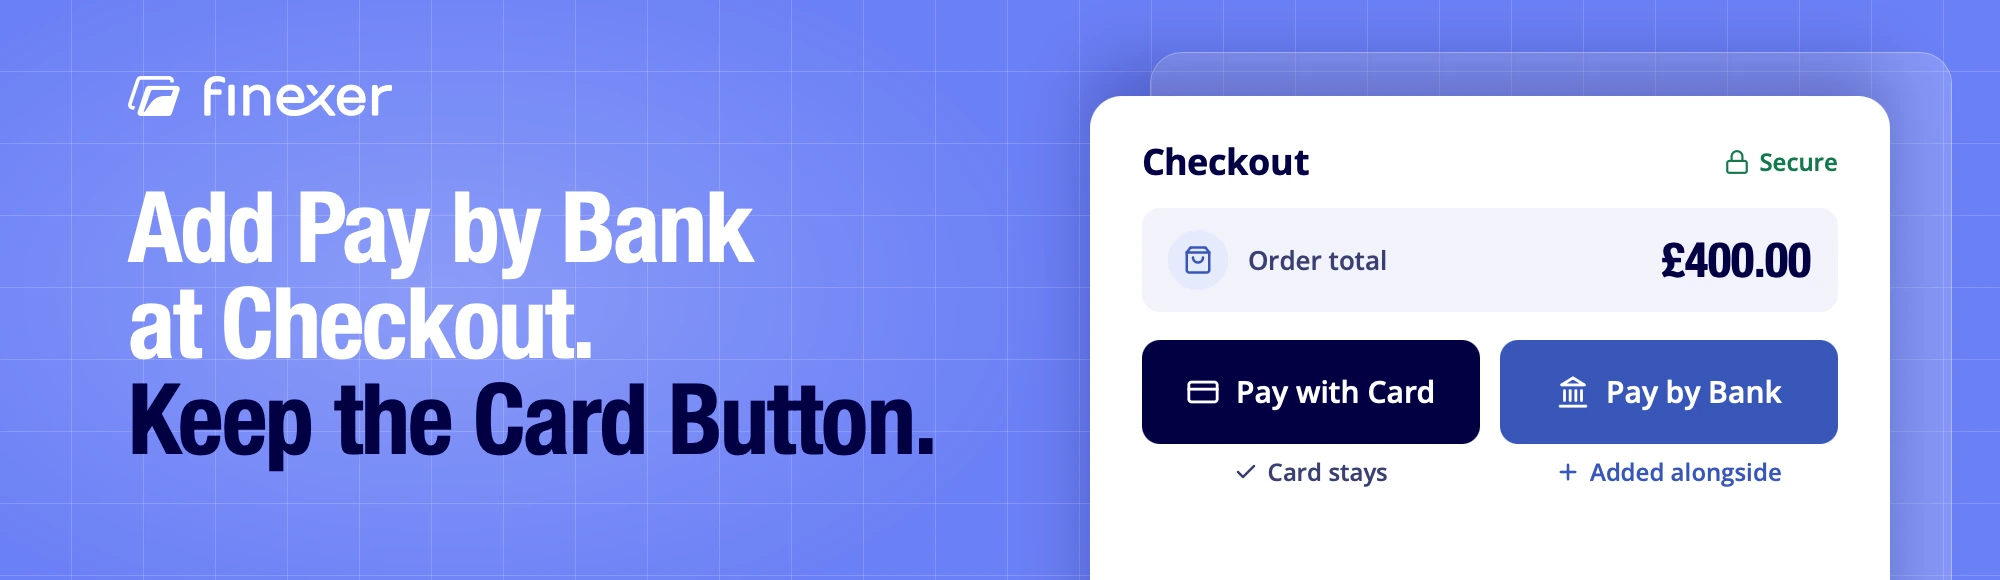
E-Commerce Payment Gateway: Best UK Options Compared
Choosing an e-commerce payment gateway means weighing pricing models, settlement timing and PCI scope, not just brand recognition. This guide compares the recognisable UK options merchants use as a payment gateway for e-commerce, then covers the methods worth adding alongside cards, including where a “payment gateway for e-commerce” setup benefits from Pay by Bank.
Source of Wealth Examples: What Evidence Should Firms Accept?
Source of wealth examples show how clients built overall wealth, while examples of source of wealth evidence link each claim to documents. Source of wealth and source of funds examples then separate wider wealth from transaction money, helping law firms, accountants, estate agents and financial services teams assess evidence and record reasoning carefully and consistently.
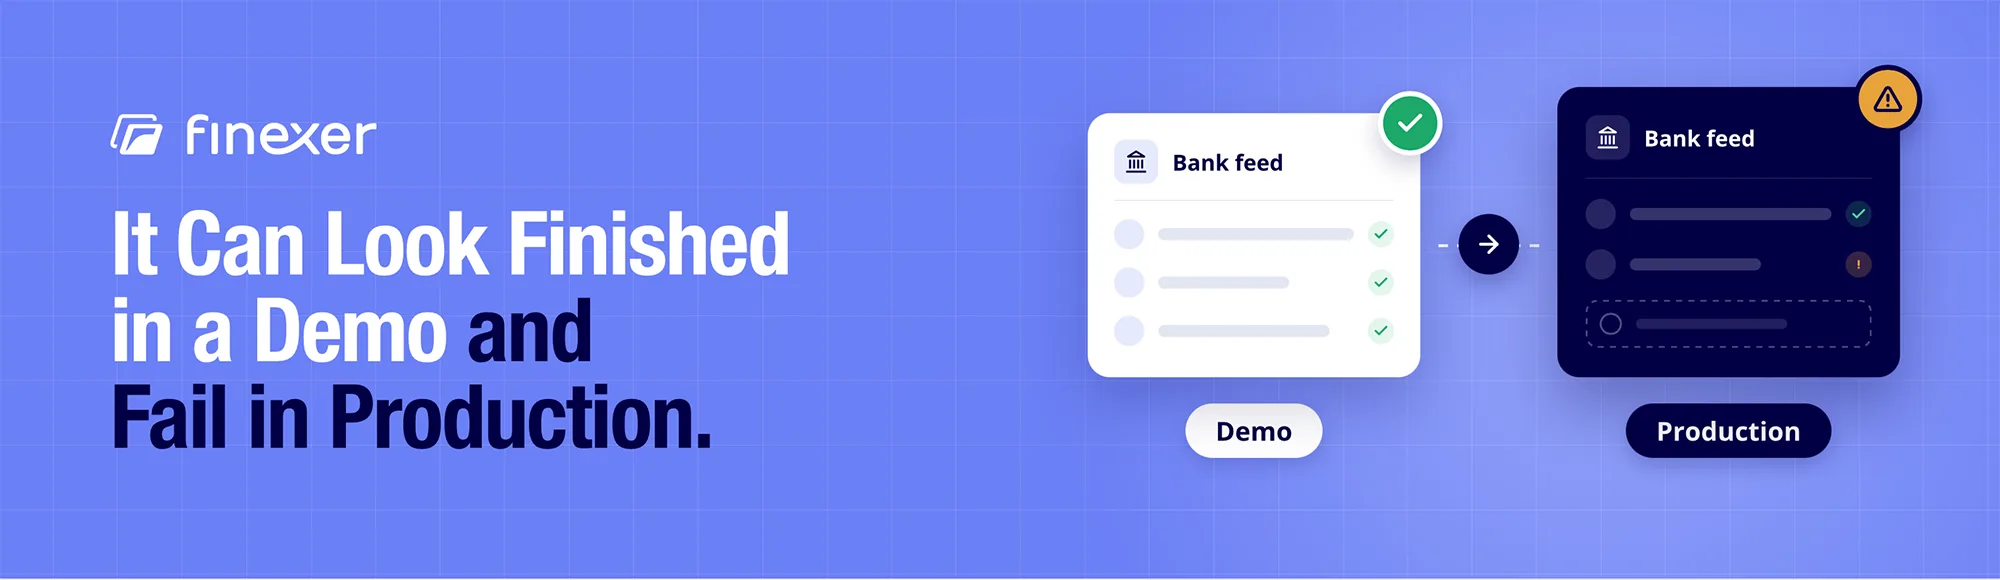
Account Information Services Provider: How to Choose
Choosing an account information services provider requires more than checking bank coverage. Compare account information service providers on FCA authorisation, AIS API quality, consent handling, webhooks, onboarding, data depth and pricing. This article shows what an AISP should deliver and the questions worth asking before committing to a contract for your platform today with confidence.
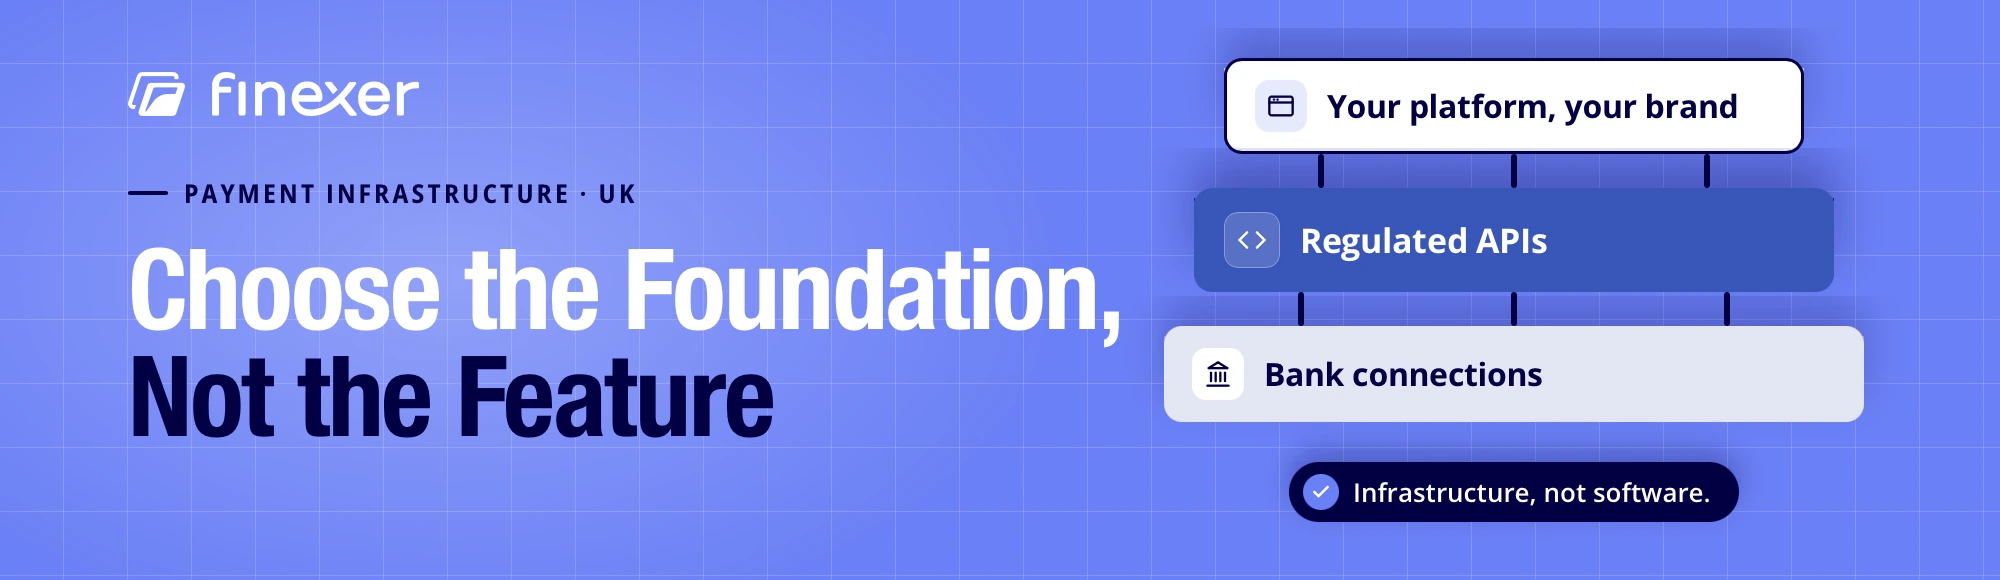
Payment Infrastructure Providers: Top UK Picks Compared
Choosing payment infrastructure providers is a foundation decision, not a feature decision. This guide distinguishes infrastructure from software, maps the four provider categories UK platforms evaluate, sets out the criteria that matter for this buying decision, and compares the recognisable UK-operating names so platform builders can shortlist with confidence.
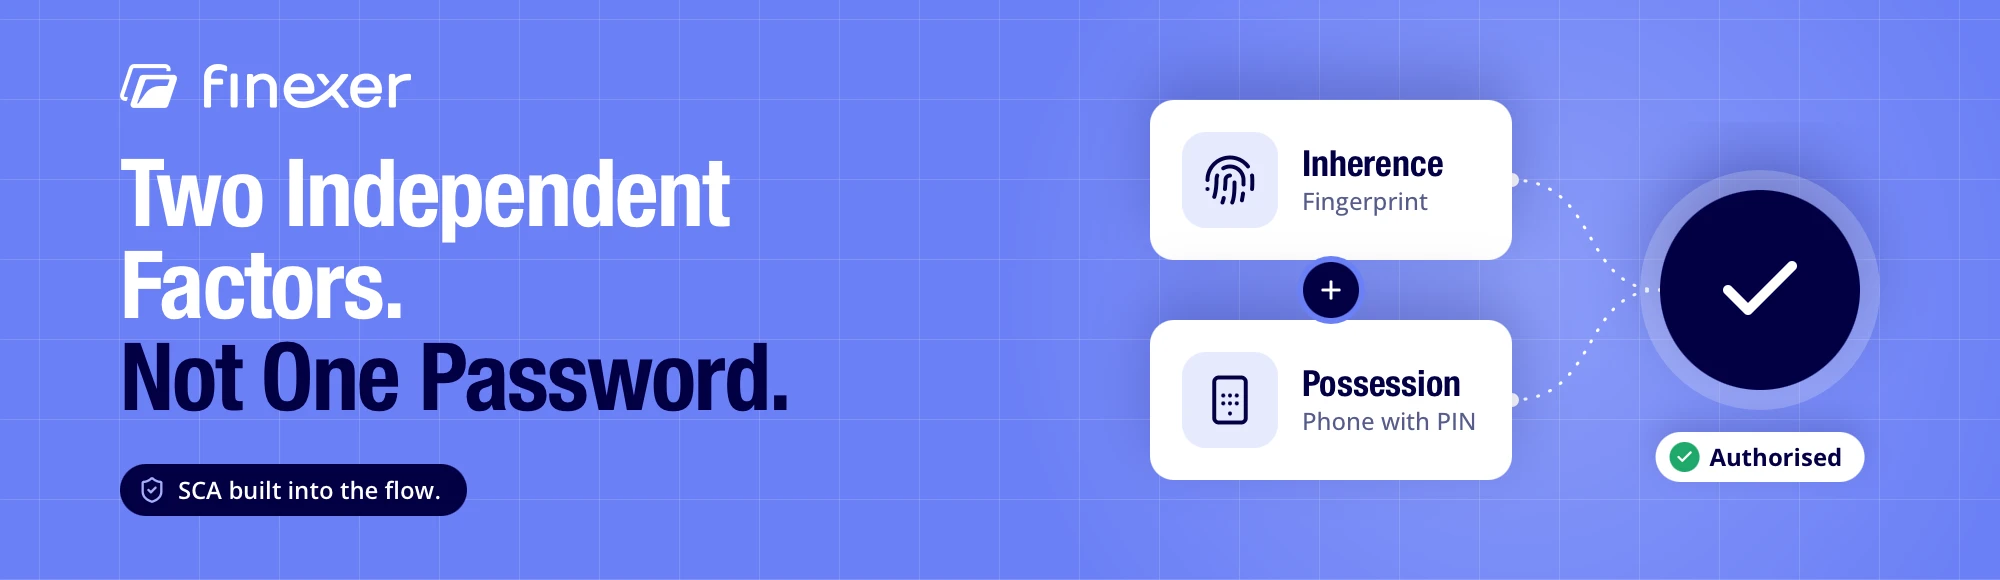
SCA Regulation UK: Complete Guide to Strong Auth
SCA regulation requires two independent identity factors before most payments are authorised. This guide explains the three factor categories, what the exemption categories cover without assuming specific thresholds, why open banking payments satisfy SCA natively, and what platforms must actually do to handle authorisation and failed attempts properly.
International Payroll Payments: A UK Guide to Cost, Timing and Payment Routes
International payroll payments can cost more and take longer than expected. This guide explains international payments processing, compares routes, shows where FX margins and bank deductions arise and covers payroll payments international timing, account details, returns and payment status, with practical guidance for UK businesses and platforms paying overseas employees and contractors across multiple destinations.
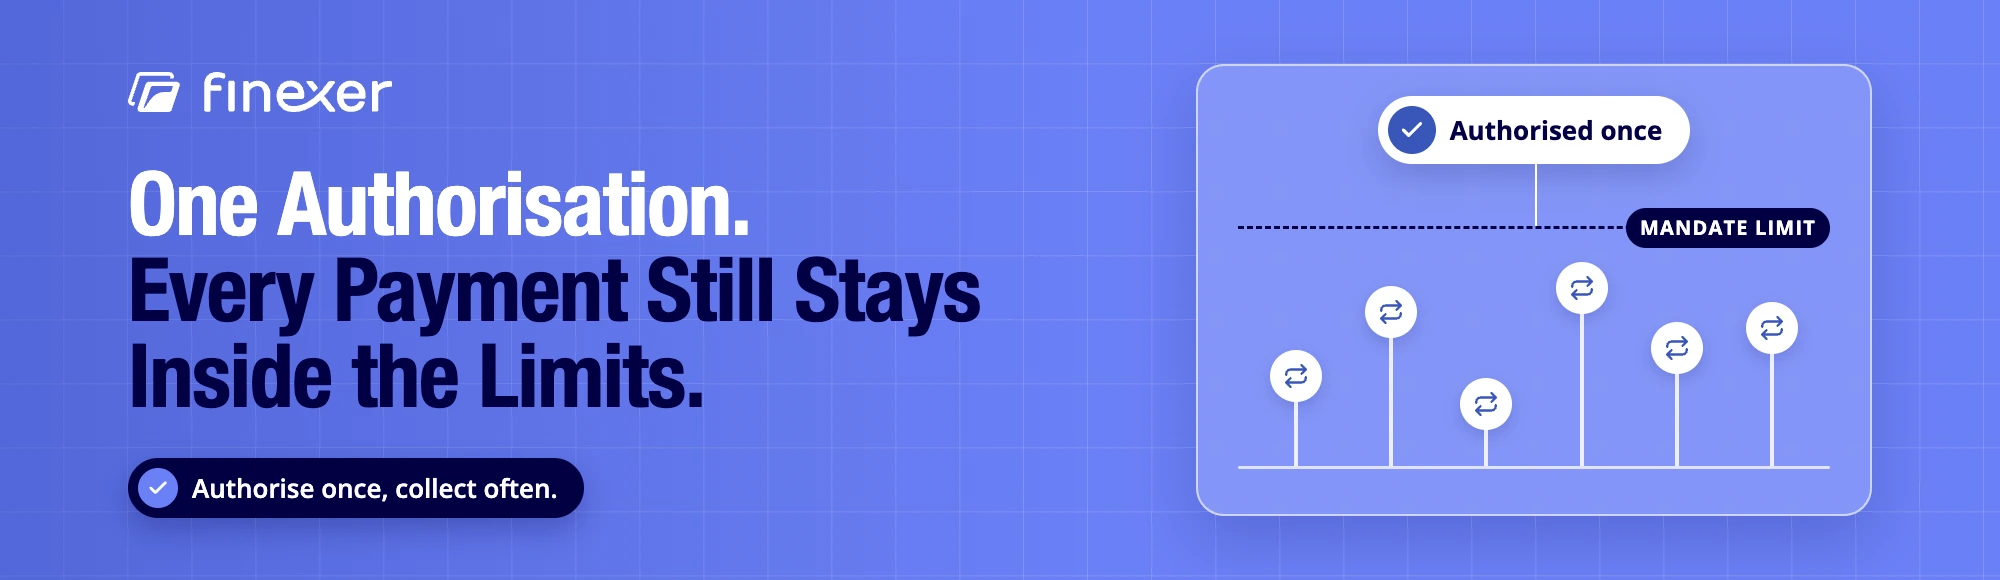
Variable Recurring Payments: Complete Open Banking Guide
Variable recurring payments open banking let a customer authorise future payments once, within limits they control and can revoke at any time. This guide covers how a VRP mandate works, sweeping versus commercial VRP, how it compares to Direct Debit and cards, and where Finexer fits with instant settlement.
Open Banking for Business Accounts: Complete UK Guide
Open banking for business accounts works across UK banks today, but coverage and consent rules differ from personal accounts. This guide covers signatory-based consent, real business account coverage, what access unlocks for platforms, and how Finexer handles business accounts through the same FCA-authorised integration used for personal ones.
What are the top Open Banking platforms for UK SMEs ?
SME buyers need: no long procurement cycles, sandbox access before contract, agent licensing to avoid FCA burden, dedicated support within a week. Discover which open banking platforms for SMEs skip lengthy sales cycles and friction. Learn why agent-route providers matter for teams. Find out what SMEs shouldn’t compromise on: FCA authorisation and account type coverage.
Open Banking API List: Top UK Providers Compared
This open banking API list compares UK and UK-operating providers on what actually matters: API scope, FCA authorisation, bank coverage and pricing model, not brand recognition. TrueLayer, Yapily, Tink, Plaid and Finexer are compared directly in one table, with guidance on how to read it before you shortlist a provider.
Which Open Banking APIs are easiest to integrate for a small dev team?
Ease of integration comes down to four testable things: documentation, sandbox parity, endpoint count, and whether data and payments sit in one API. Here’s a practical framework for evaluating the easiest open banking api for a small dev team, before committing build time.
Touchless Payment Options: Best Methods for UK Firms
Touchless payment options let customers pay without handling a terminal or entering card details manually. This guide compares contactless card, mobile wallet, QR-initiated bank payment, and payment link methods on cost, settlement, and sector fit, with the honest limitations of each, so UK merchants can decide which flexible payment options suit their customers best.
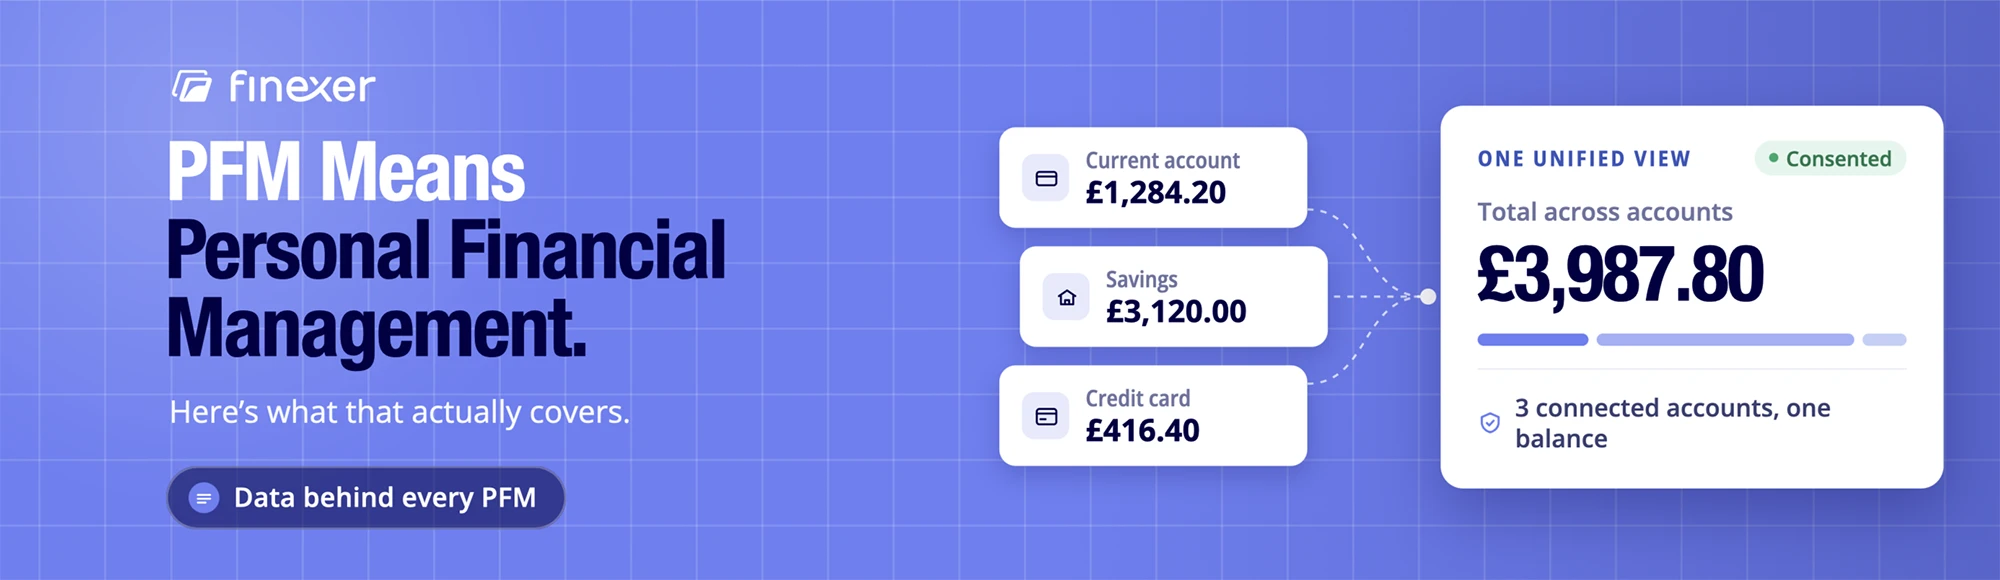
PFM Meaning: What Personal Financial Management Actually Covers
PFM, meaning Personal Financial Management, is a category of tools bringing forth account balances, categorising everyday spending and flagging upcoming bills before they land. This guide’s coverage extends to what PFM represents, ways a PFM tool reads banking data behind the scenes and the needs that a platform may have before it properly builds one.
Which Open Banking provider has the best UK bank coverage?
Headline bank counts look impressive but tell you little about real open banking bank coverage. The differences that matter sit in business accounts, challenger banks, and connection reliability. Here’s what to ask a provider before choosing, and where common coverage gaps actually appear.
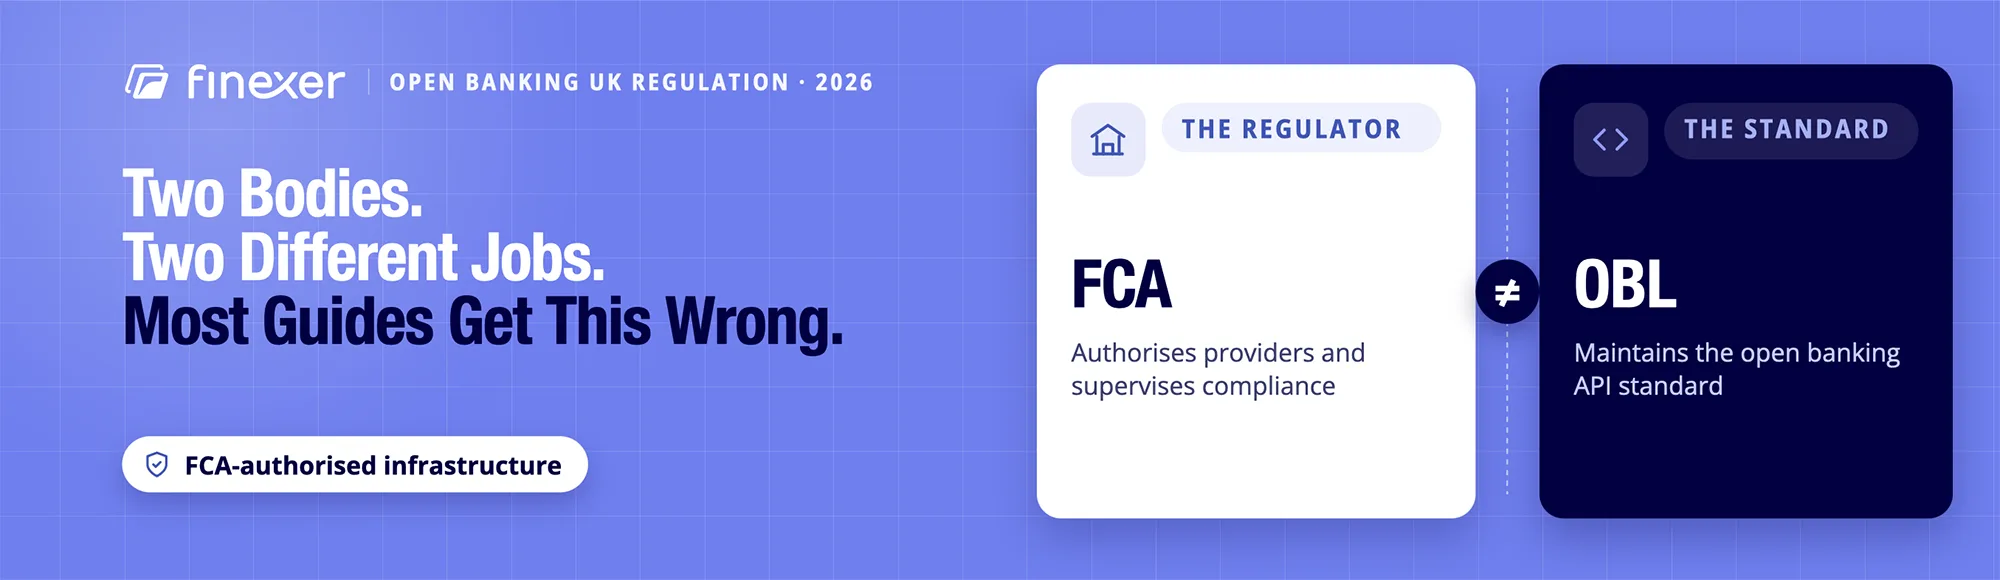
Open Banking UK Regulation: Essential 2026 Guide
Open banking UK regulation divides responsibility between the FCA and Open Banking Limited, with PSD2 as its legal foundation. This guide explains authorisation, AISP and PISP status, the 2026 regulatory changes, and what compliance leads and product managers should verify before building on an open banking provider.
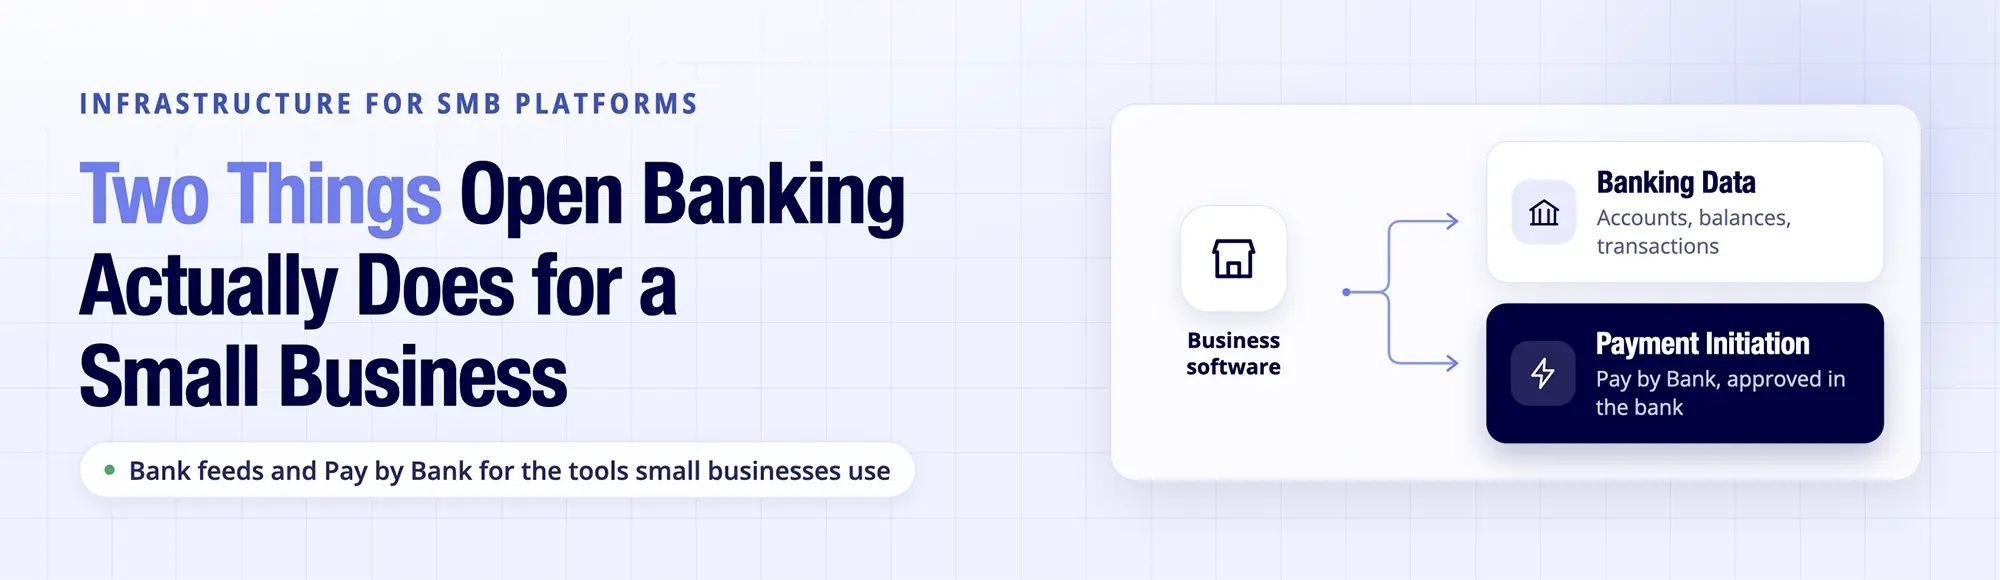
Open Banking for Small Businesses: A Practical UK Guide
Open banking for small business gives smaller firms access to banking data and account-to-account payments through regulated providers. This guide explains small business payment processing, Pay by Bank, reconciliation, cash visibility and open banking payment initiation, including what businesses need to get started and where platform providers such as Finexer fit into the picture.
Payroll Processing Software: 5 UK Tools Compared
Compare payroll processing software for UK practices and employers, including payroll processing software for accountants and payroll processing software for small business. This guide assesses HMRC recognition, bureau features, integrations, pricing models and the payment step after payroll. It also explains where payment execution, failed salary payments and reconciliation fit into the wider payroll workflow.
Open Banking for Payments: Proven Merchant Guide
Merchants evaluating open banking for payments want a direct comparison with cards on cost, settlement, and checkout experience. This guide covers how the open banking payment flow works, where it outperforms card rails, what its honest limitations are, and which UK business models get the most from it in 2026.
Payment Failure: Why It Keeps Happening and What Actually Fixes It
Every payment failure has a specific cause, and most payment failures follow familiar patterns across cards, Direct Debit and bank payments. This guide explains why they happen, how they affect revenue, and what to look for in a payment system for small businesses before failed collections become a recurring operational problem.
Build, Refer, or White Label: The Decision Most Platforms Get to Only Once
Choosing between building bank connectivity in-house, referring customers elsewhere or adopting white label finance solutions comes down to how much regulatory burden a platform wants to keep. This guide explains white label financial services against the other two routes, what regulatory reliance actually means and the criteria separating a strong provider from a weak one.
Alternative Payment Options: Best UK Methods Compared
Cards are not the only option for UK merchants. Alternative payment options -from Open Banking and Direct Debit to digital wallets and A2A -each offer different trade-offs on cost, settlement speed, and chargeback exposure. This guide compares the most relevant UK payment methods so merchants can evaluate what fits their business model.
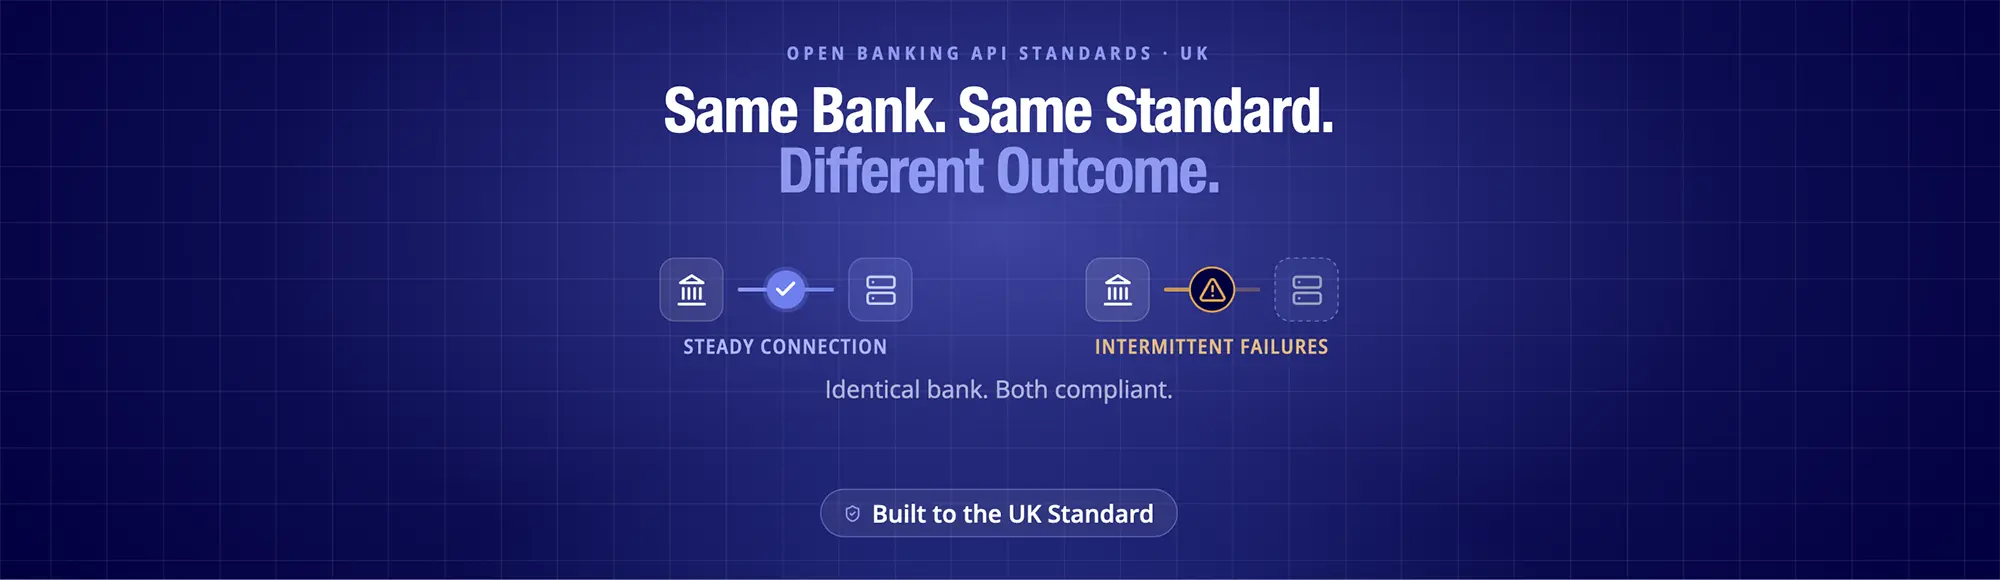
Open Banking APIs: UK Standards and Specs Explained
Two providers connecting to the same bank can behave differently, even though both follow open banking api standards. This guide explains what the UK Open Banking Standard actually mandates, what is left to each provider’s implementation, and how to read API documentation against the spec before you commit to an integration.
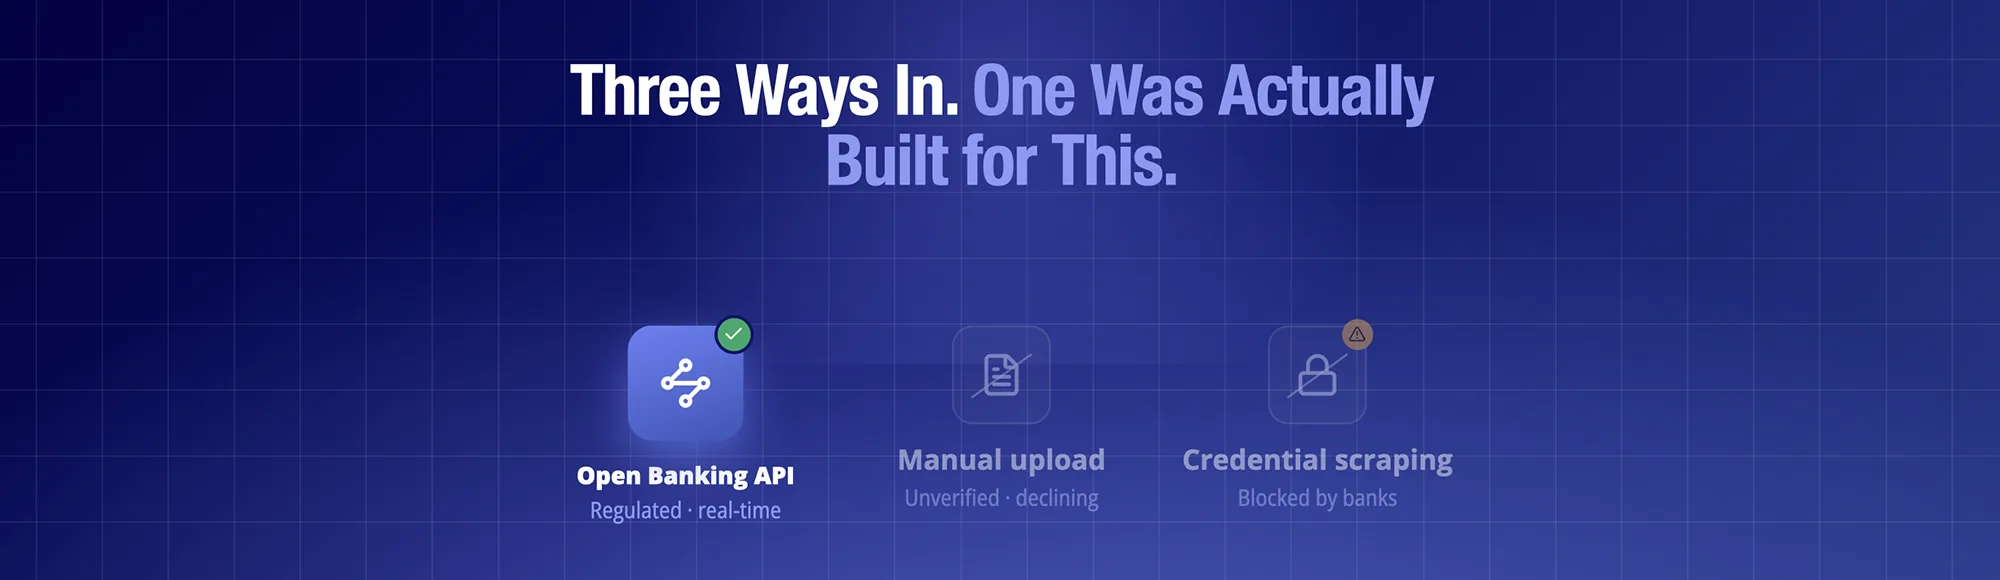
UK Financial Data: Verified Access Routes Explained
UK financial data can be accessed three ways: manual upload, credential scraping, or consented Open Banking connections. Only one is built for regulated, verified access at scale. This guide covers what UK financial data actually includes, how consent works, and what separates a legitimate access route from a declining one.