Category: Open Banking
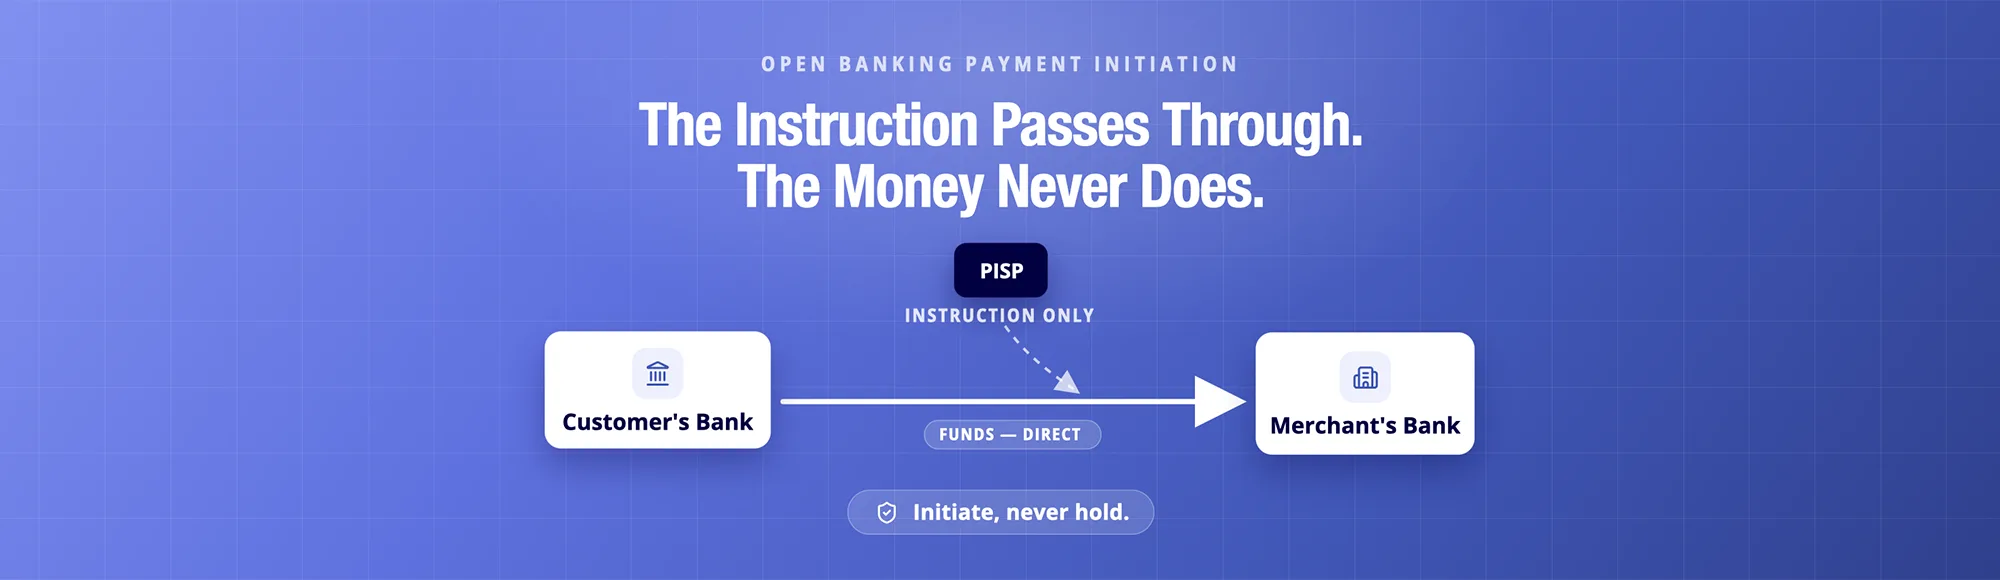
Open Banking Payment Initiation: How PIS Actually Works
Open banking payment initiation lets businesses collect bank payments directly through a regulated payment initiation service, without card networks or intermediaries. Learn how PIS works, how Strong Customer Authentication protects every payment, and what to evaluate before choosing a provider for Pay by Bank integration.
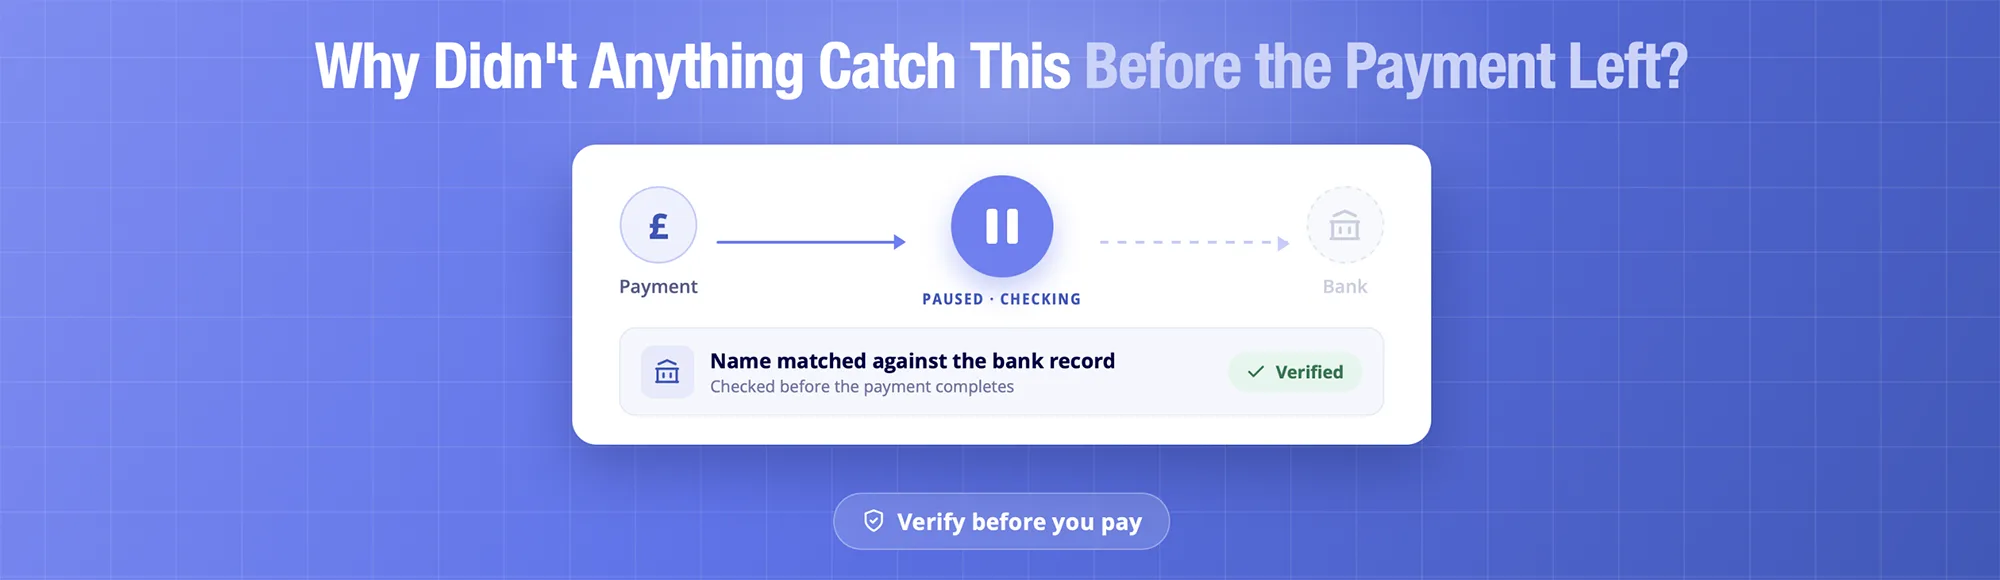
What a Bank Account Verification API Actually Returns
A bank account verification api checks that an account exists and that the name on it matches the expected payee before money moves. This guide covers UK bank account verification match outcomes, full match, close match, no match, where the check belongs in a payment flow, and what to evaluate before choosing an API provider.
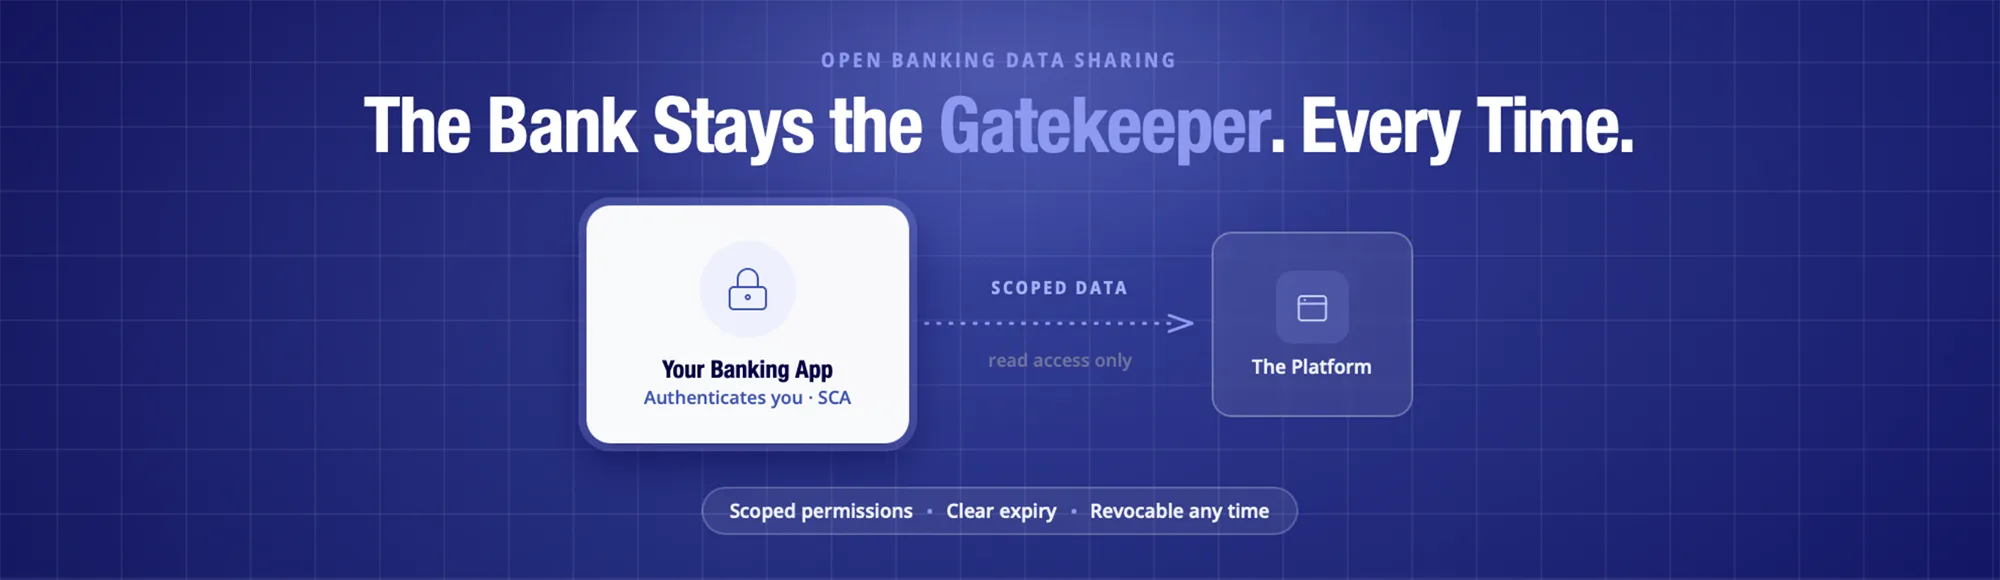
Open Banking Data Sharing: How Secure Consent Works
Open banking data sharing lets customers grant regulated third parties read access to specific bank data, for a defined period, without ever sharing login credentials. This guide walks through the consent journey step by step, what permissions actually mean, and the privacy protections built into the model by design.
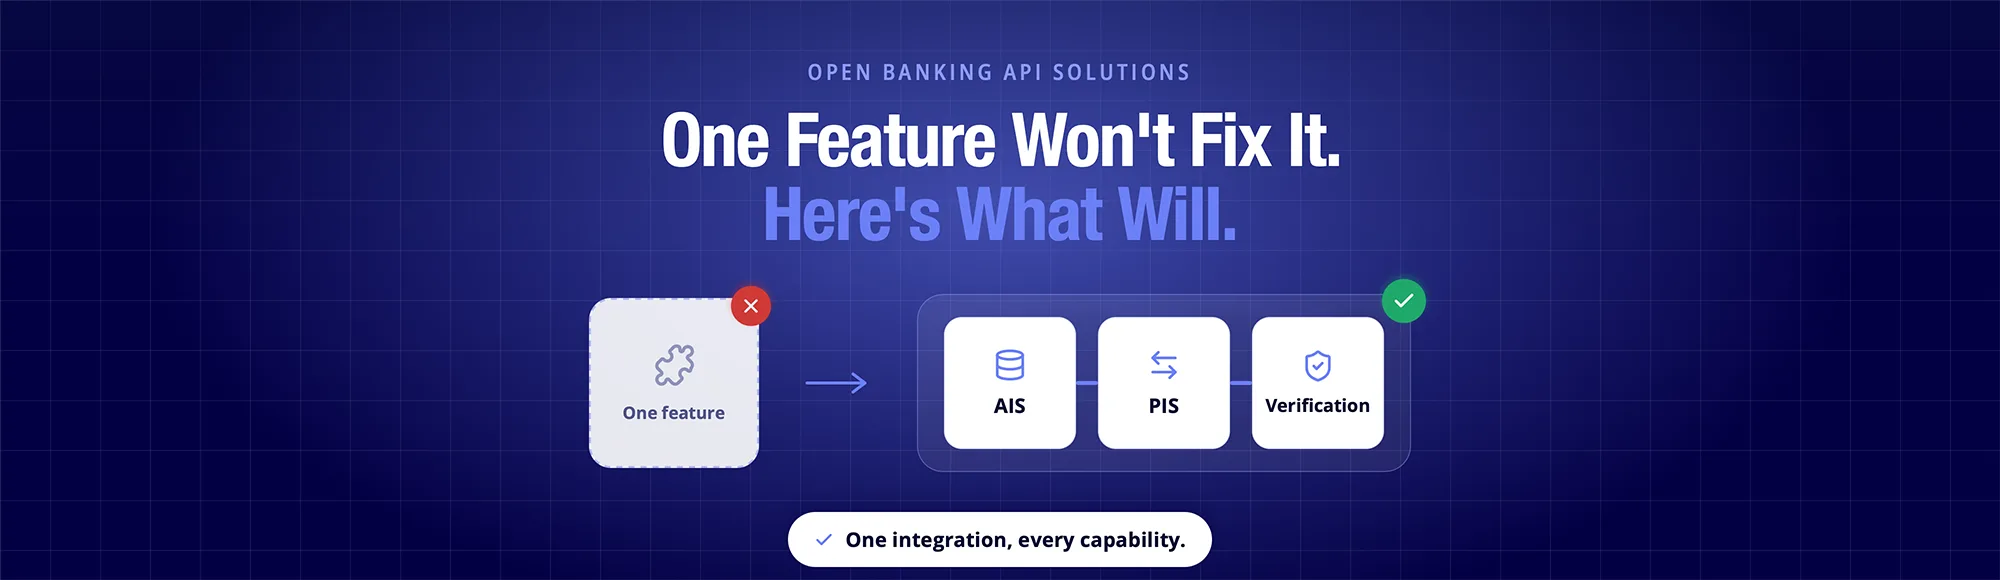
Open Banking API Solutions: Solve Real Business Problems
Open banking API solutions are not one feature. This guide maps specific business problems, manual reconciliation, high card fees, payment fraud, to the exact capability that solves each one, and explains why most real fixes need two or more capabilities working together, not a single API call.
Open Banking API Examples: Real API Calls Explained
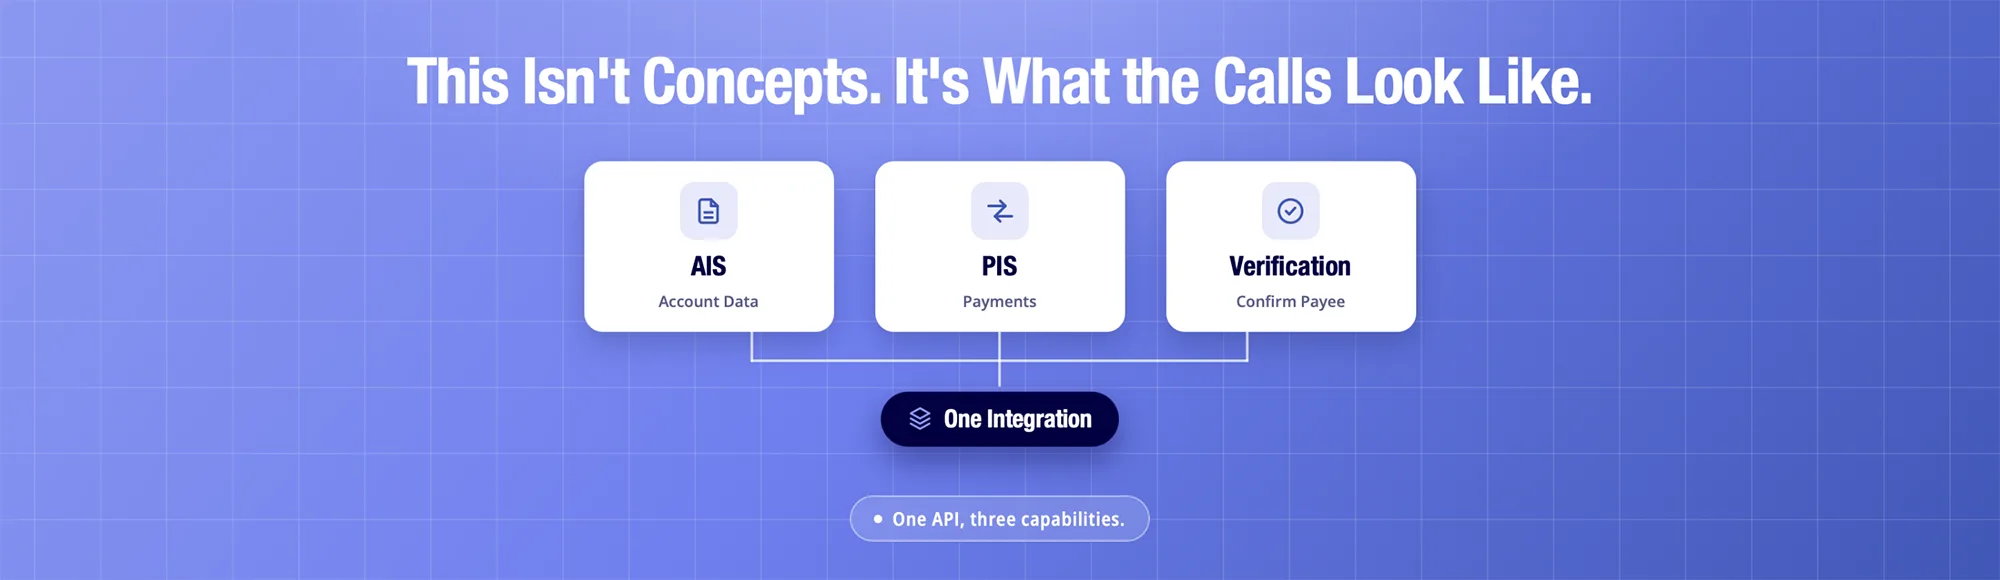
Open banking API examples walk developers through three core workflows: retrieving account data, initiating payments, and verifying account holders. This guide shows real request shapes, response structures, authentication flows, and the integration realities that separate documentation from production code you can actually ship.
Open Banking Payments: A Guide for UK Businesses
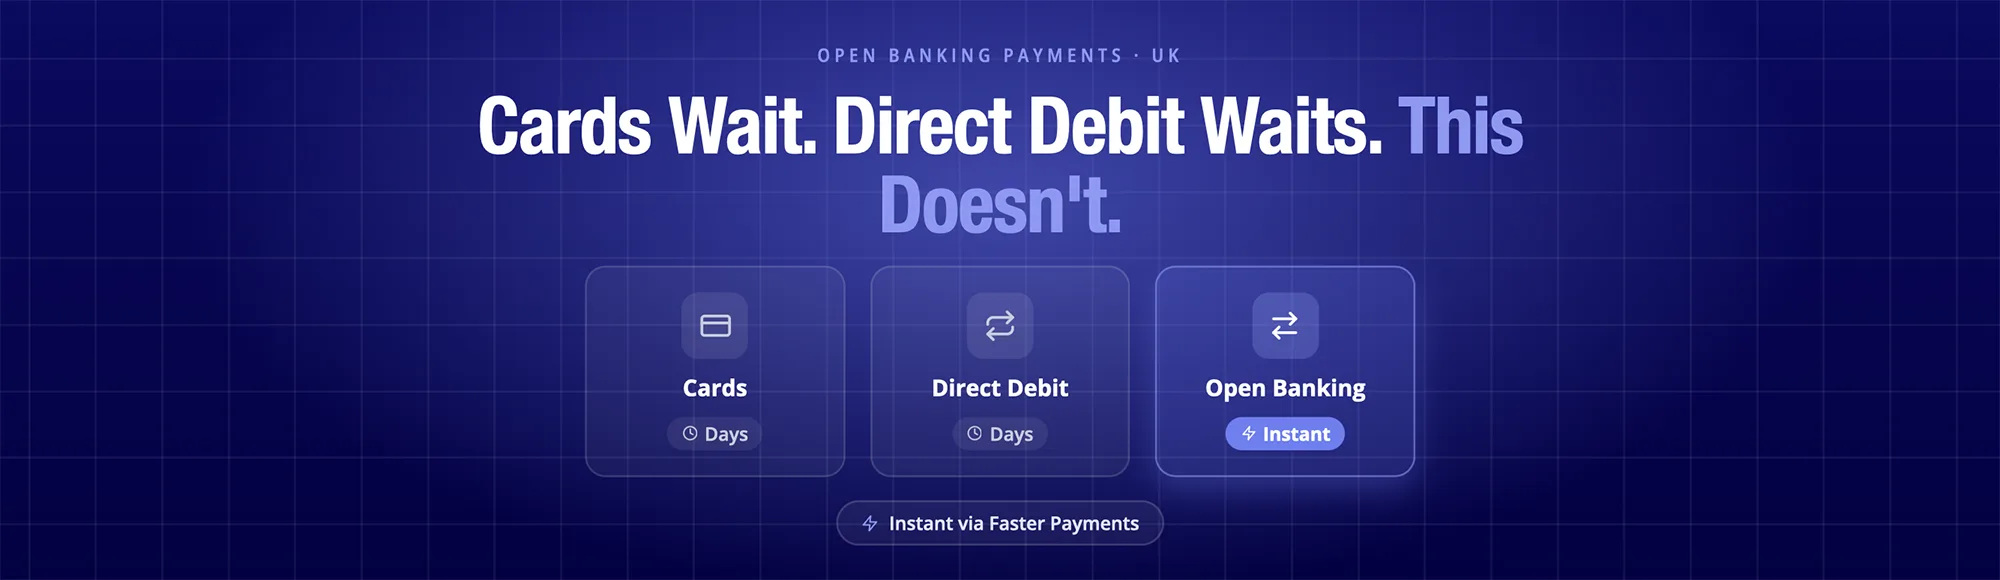
Open banking payments move money directly between bank accounts, authorised by the customer and settled via Faster Payments. This guide explains how they work, compares them with cards and Direct Debit, covers variable recurring payments for subscriptions, and outlines what to evaluate before choosing an Open Banking payments provider.
6 Open Banking API Use Cases: What Developers Actually Build
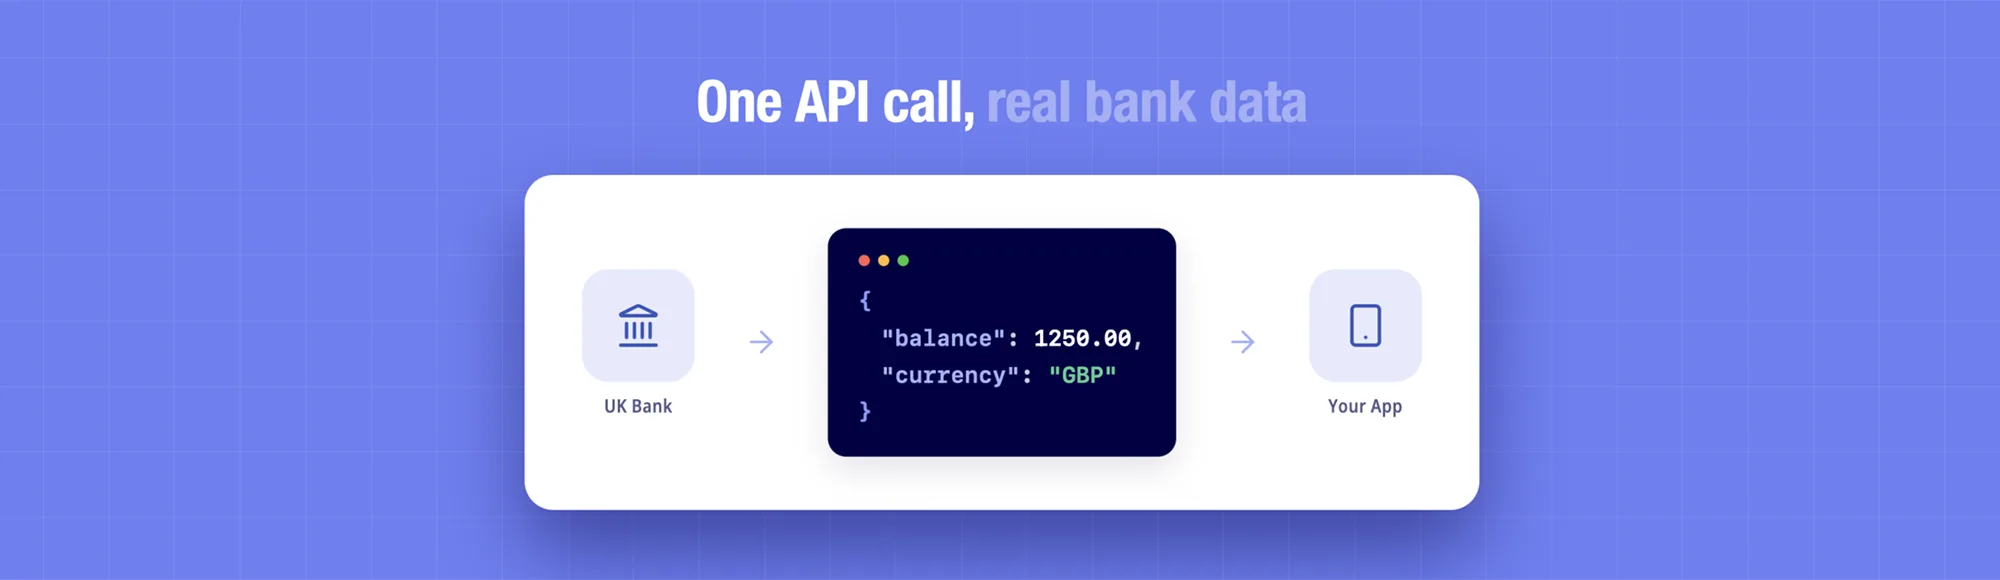
Most guides show business outcomes. This one shows what developers actually integrate. Concrete AIS endpoint structures, PIS payment flows, real data schemas, and worked examples of account aggregation, affordability checks, and Pay by Bank checkouts – the technical depth developers need before writing their first API call.
Top 5 Tink Alternatives for UK Businesses in 2026
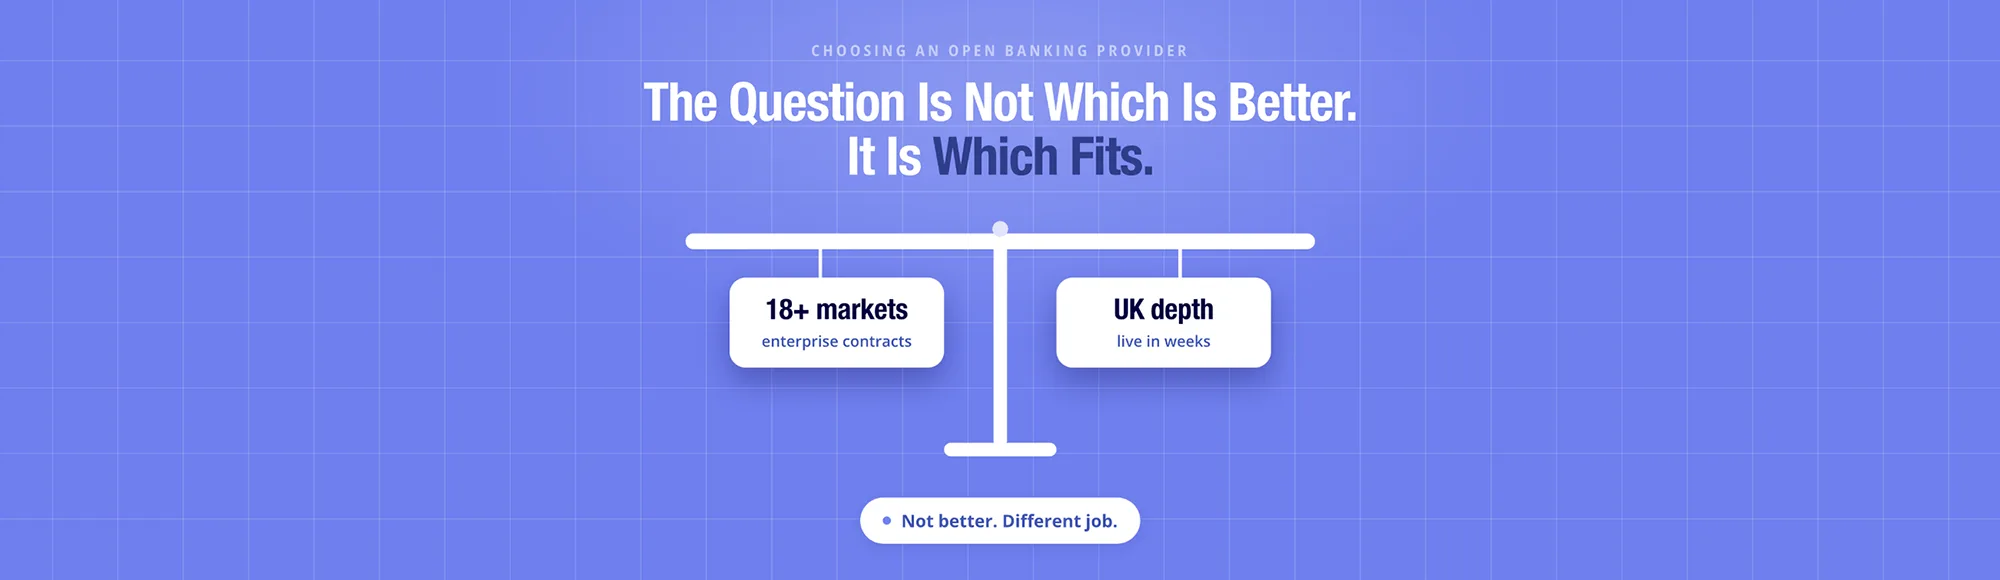
Searching for Tink alternatives usually starts with a mismatch: you need UK coverage and a fast integration, and an enterprise pan-European platform is more than the job requires. This guide compares five credible options on coverage, deployment speed and bundled capabilities, so that you can shortlist the provider that actually fits your product and timeline.
UK Open Banking Security: 5 Myths About Consent
Open banking security is often misunderstood because many businesses still believe outdated myths about consent and data sharing. This guide explains how open banking API security protects financial information, who controls access, and why regulated APIs provide stronger safeguards than older methods used before Open Banking became widely available in the UK.
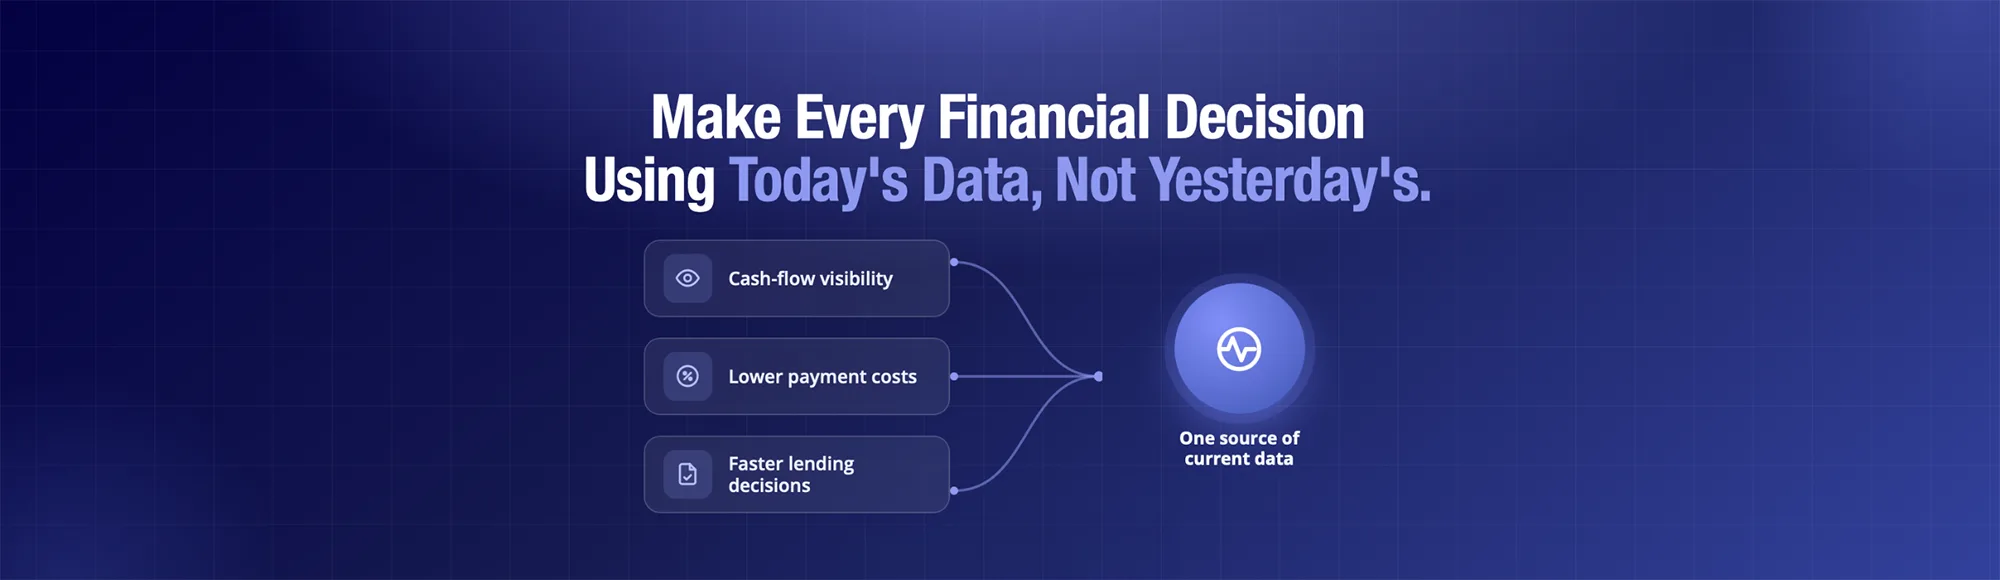
Open Banking for Businesses: Why UK Companies Are Adopting It Faster Than Ever
Open banking for businesses gives organisations secure access to current banking data, account-to-account payments and faster financial decisions. This guide explains why open banking for small businesses’ adoption continues to grow, what commercial value it delivers and how to evaluate an FCA-authorised provider before selecting Open Banking infrastructure for long-term growth.
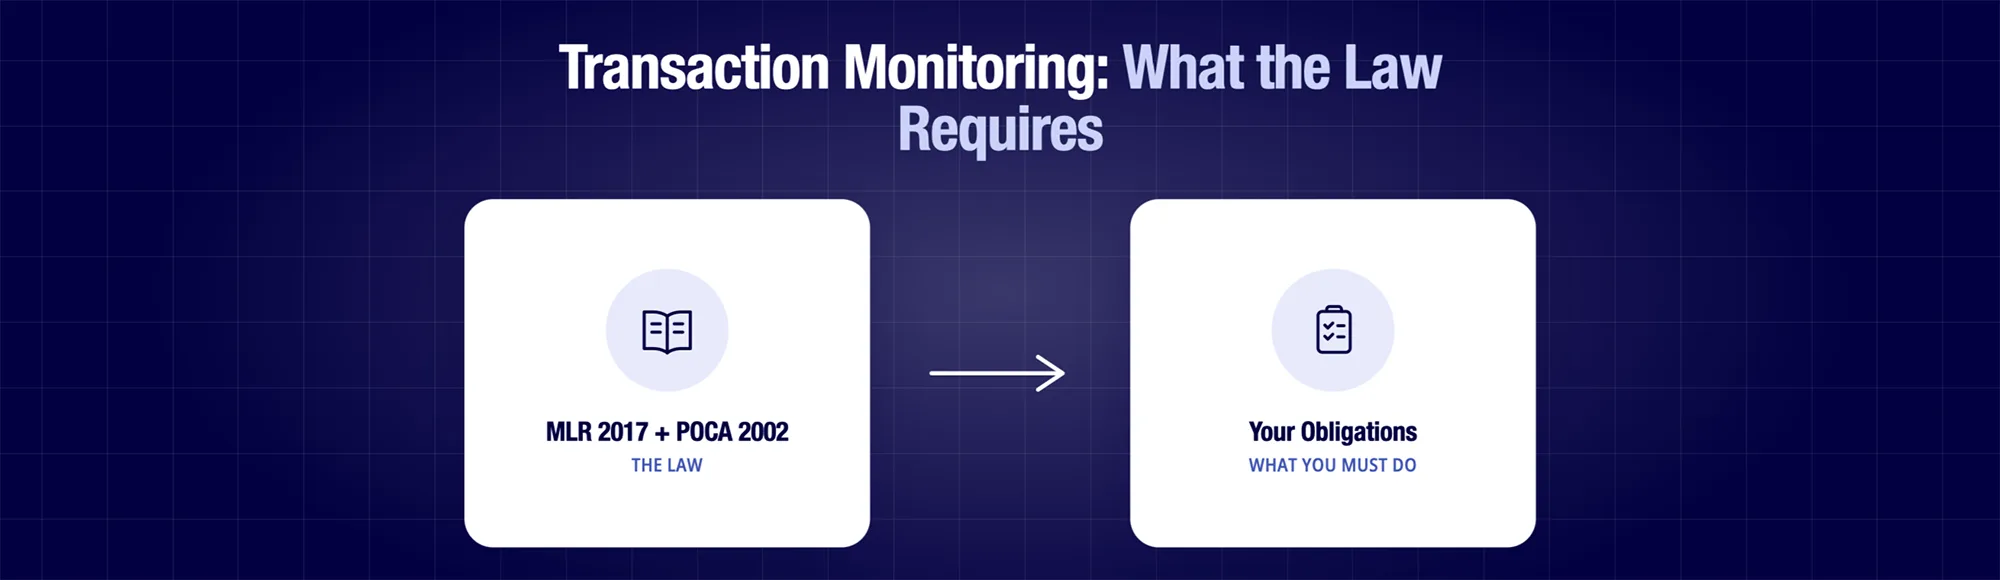
Transaction Monitoring Process UK: What the Law Requires
Most guides to the transaction monitoring process jump straight to software. This one starts where your obligations actually start: the regulatory text itself. In plain, practical terms, it covers exactly what MLR 2017 and POCA 2002 require, what triggers a SAR, how often monitoring should run, and the documentation HMRC expects to see on file.
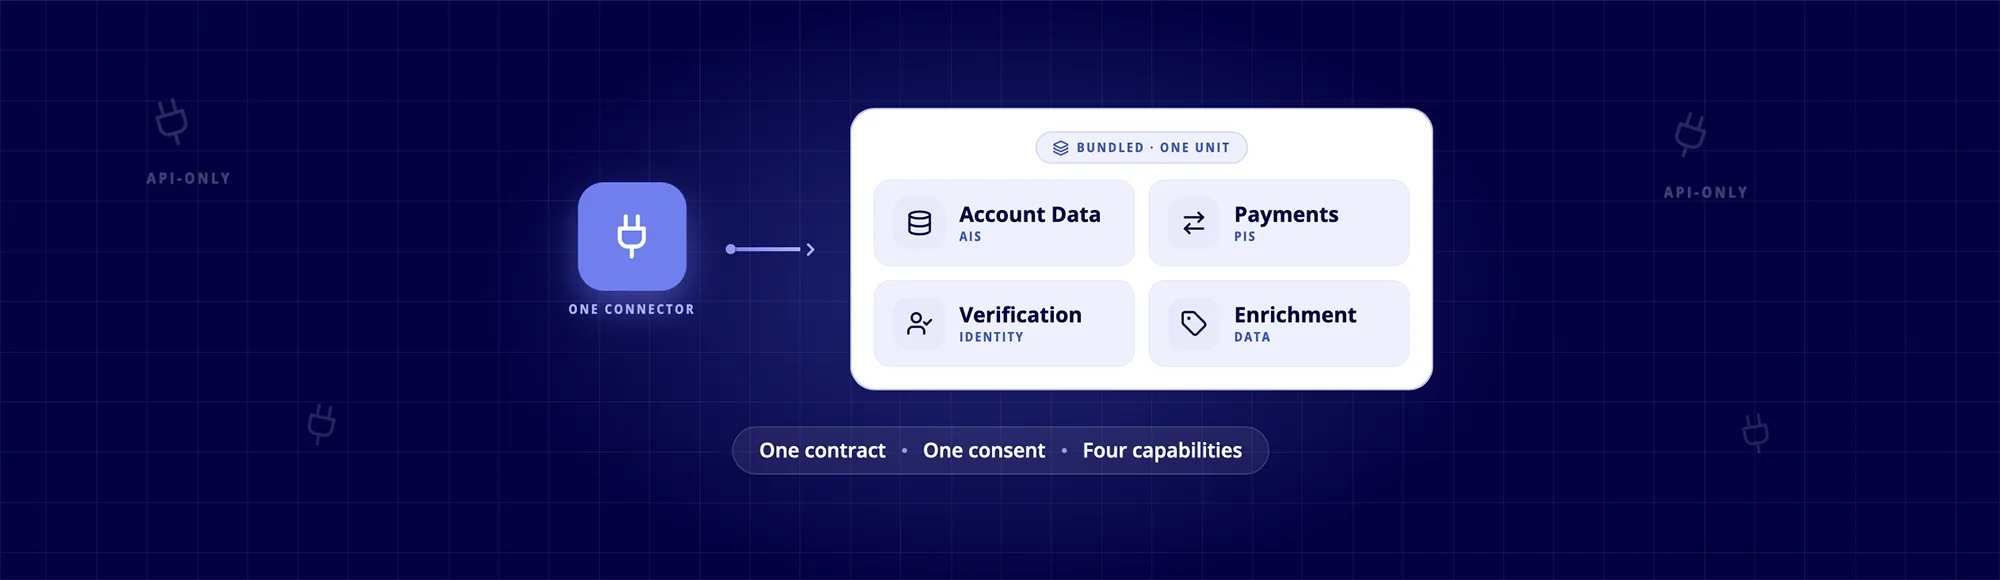
6 Best Open Banking Solution Providers UK 2026
Expense management automation goes beyond OCR receipt capture. This guide compares receipt-only workflows with bank-verified matching, showing how UK finance teams can use real bank transaction data to improve reconciliation, policy checks, GL-code automation, and audit readiness. Learn what to evaluate before choosing an expense management automation solution
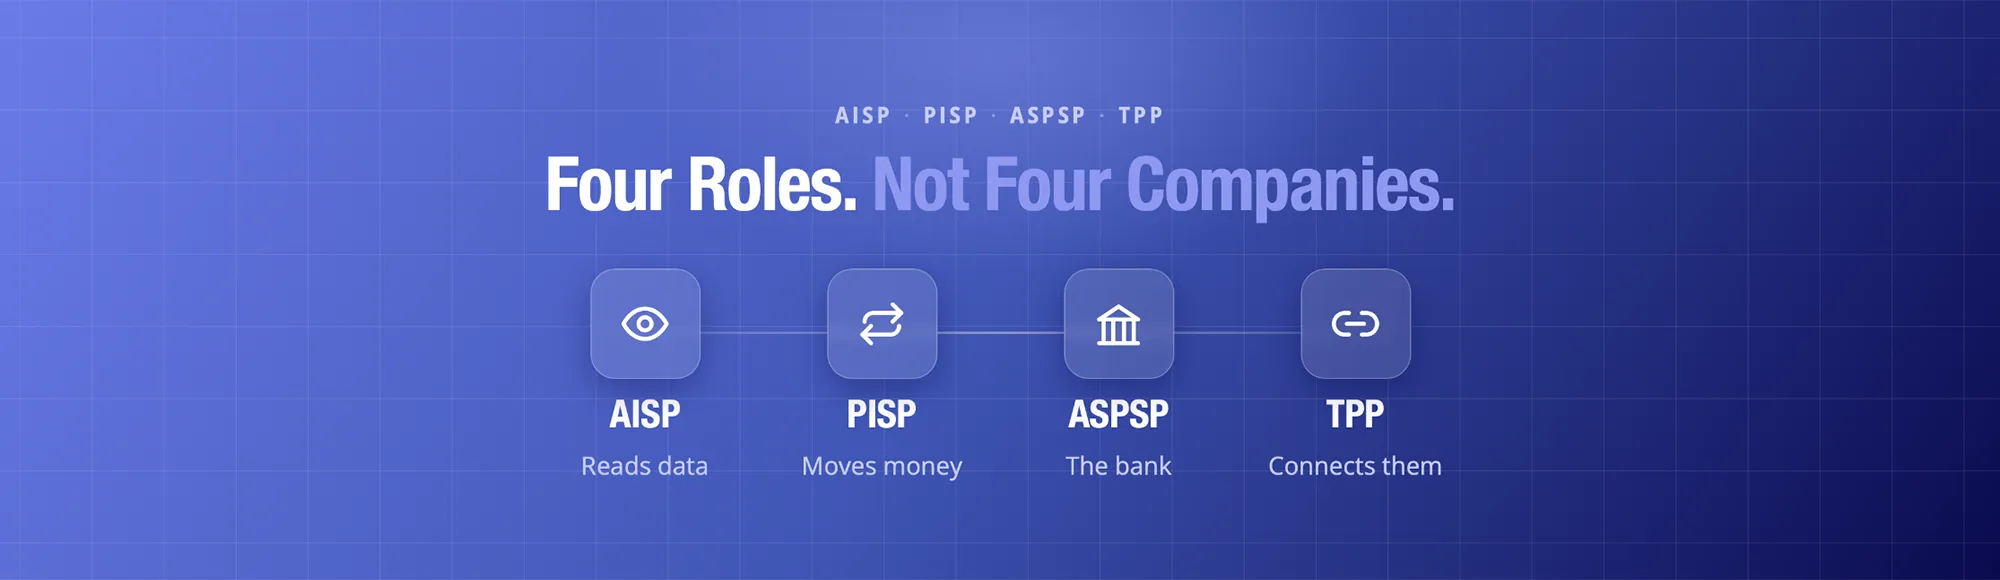
AISP Meaning: AISP vs PISP vs ASPSP Explained (UK)
AISP, PISP, ASPSP and TPP can look like alphabet soup, but the ideas behind them are genuinely simple. This plain-English guide explains what an AISP does, how it differs from a PISP and an ASPSP, why many providers hold both licences, and how to check any UK provider on the FCA register before you integrate.
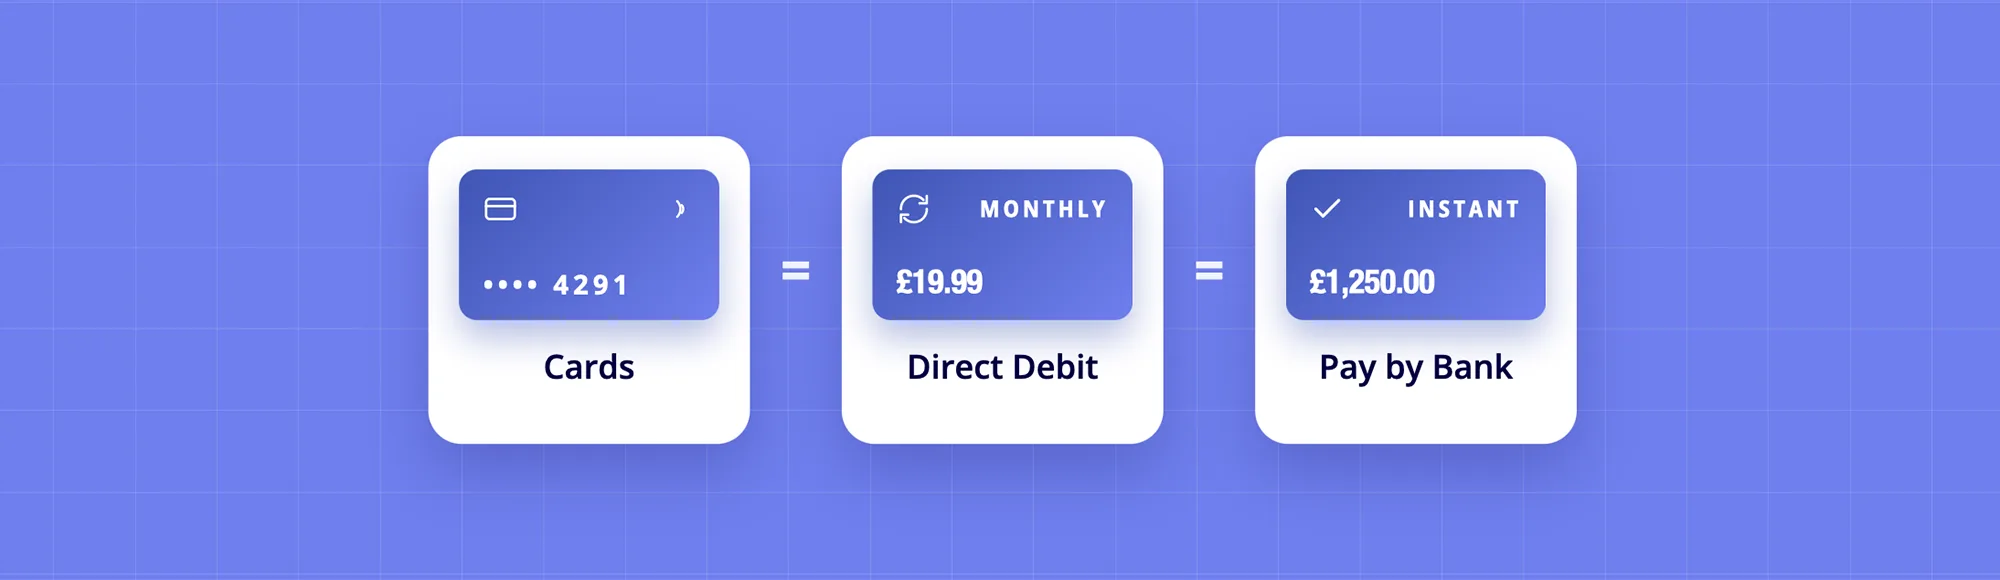
Online Payment Systems UK: Cards vs Bank Transfer 2026
Online payment systems in the UK now span cards, bank transfers, and Open Banking. Each suits different use cases-cards dominate by volume, Direct Debit by recurring bills, and Open Banking by speed. This guide compares all three, so you pick the right system for your business.
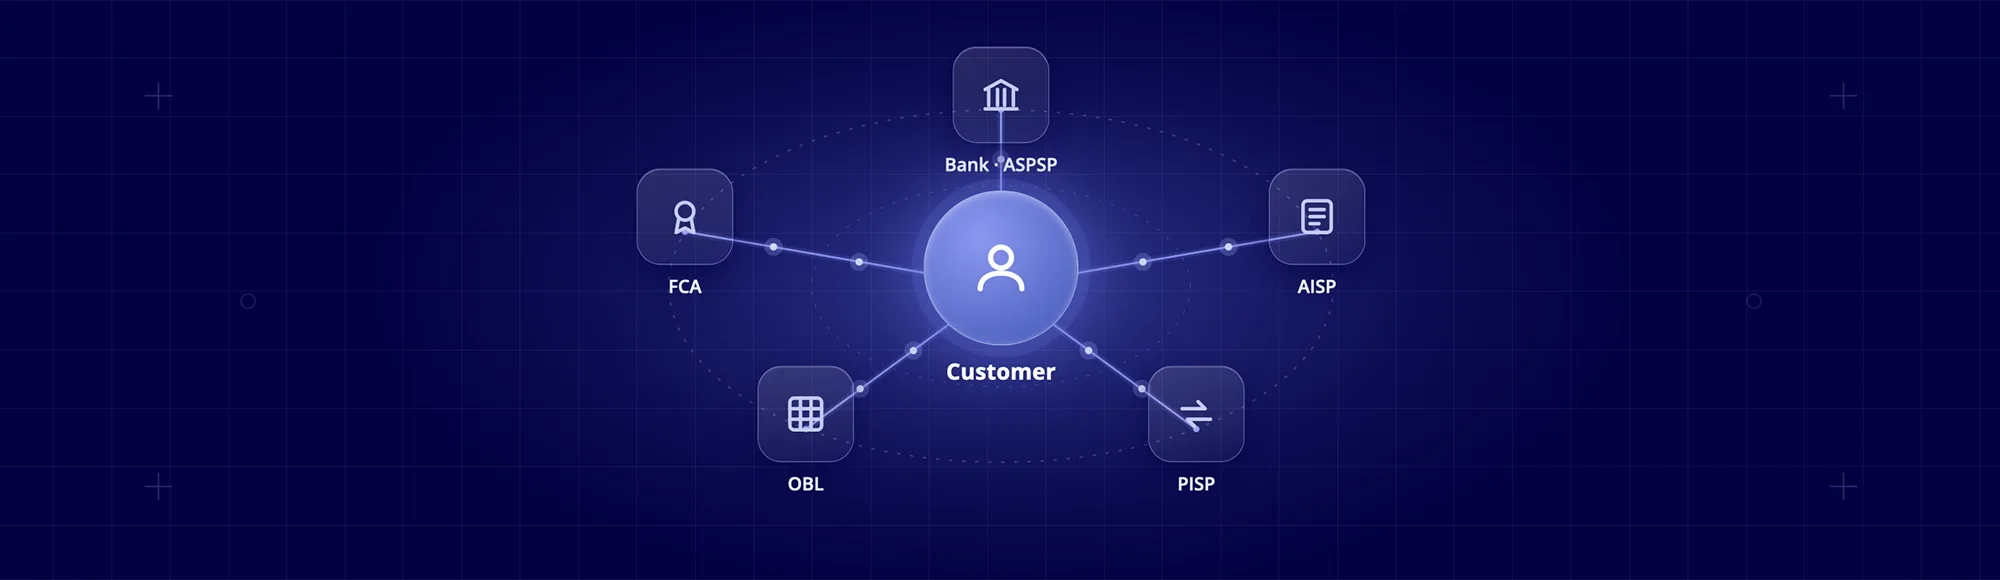
Open Banking Ecosystem: Who the Players Actually Are (and How They Work Together)
Understanding the open banking ecosystem begins with knowing who participates, why they exist and how data moves securely between them. This guide explains banks, AISPs, PISPs, regulators and open banking infrastructure using practical examples, helping buyers understand the UK’s Open Banking landscape without needing multiple resources or technical documentation.
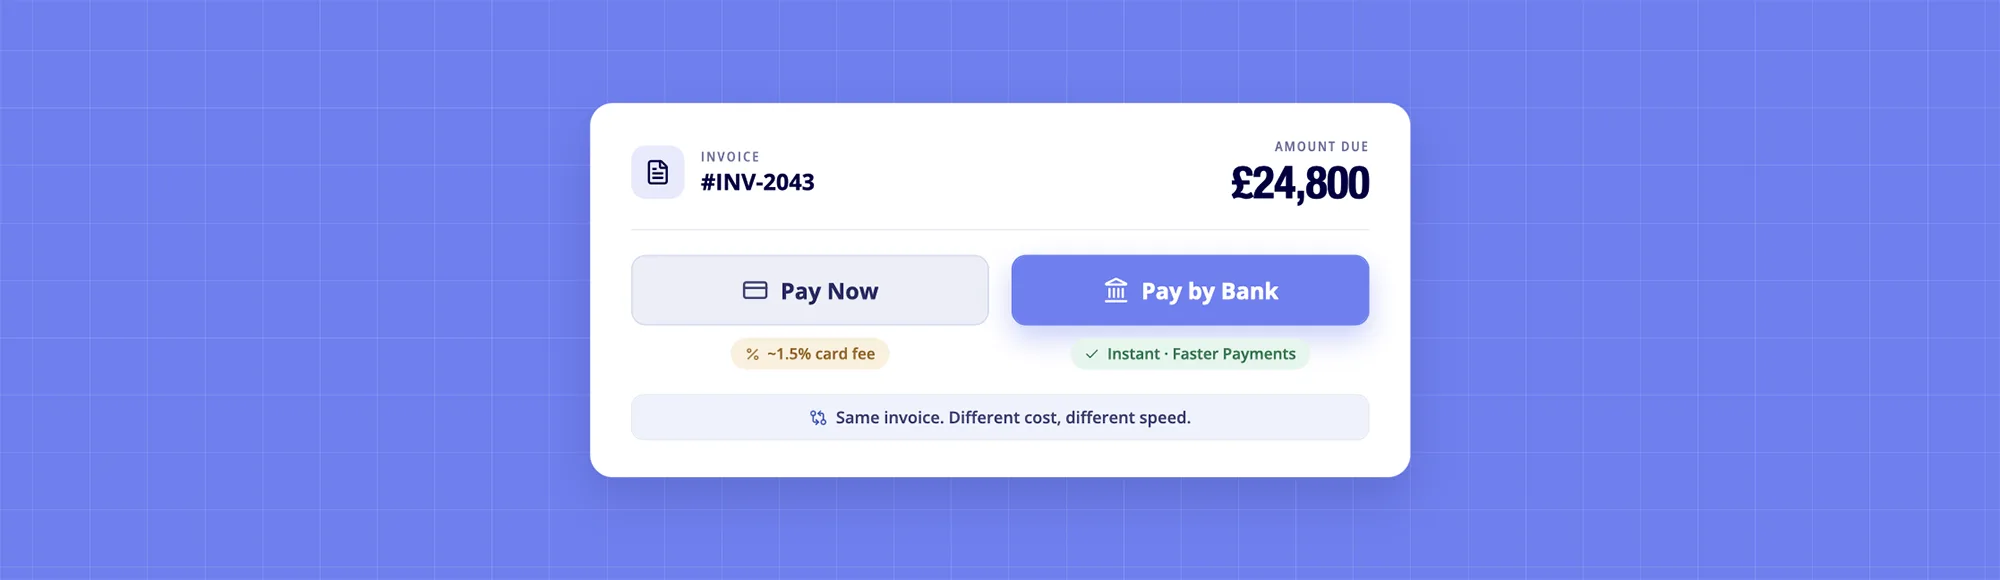
Online Invoice and Payment Processing UK: Beyond Card Fees
Discover how online invoice and payment processing using Open Banking replaces costly card-based Pay Now buttons with Pay by Bank. Learn how automated invoice processing, instant payment confirmation via Faster Payments and bank-data reconciliation reduce manual finance work, lower transaction costs and improve payment visibility for UK SaaS platforms while accelerating cash flow.
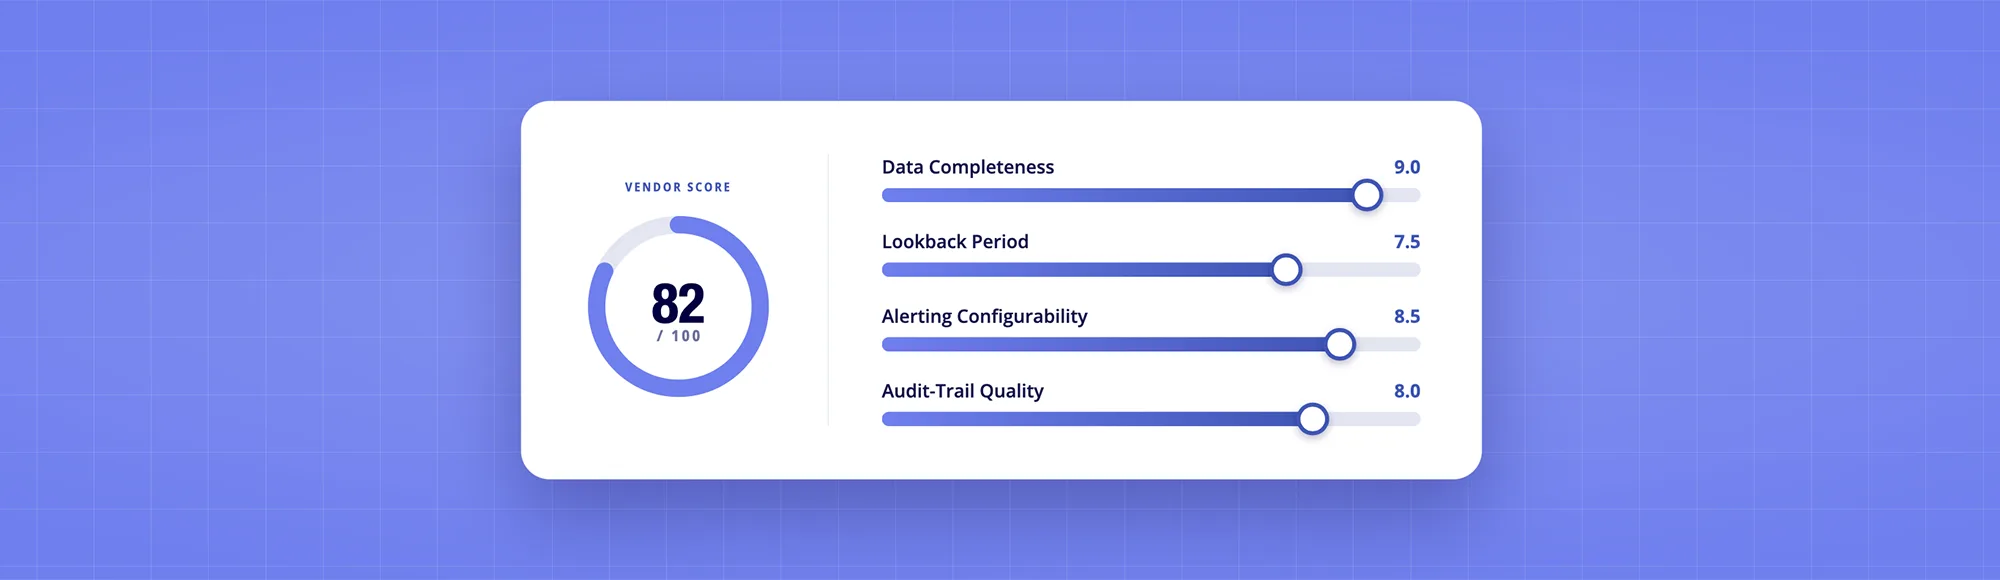
Transaction Monitoring Solutions: Scored Evaluation (UK)
Most transaction monitoring solutions fail because of alert fatigue, not missing features. This guide scores vendors on data quality, lookback depth, alert configurability, and audit trails, helping UK compliance teams compare solutions using practical evaluation criteria and choose one that reduces false positives instead of creating more unnecessary alerts.
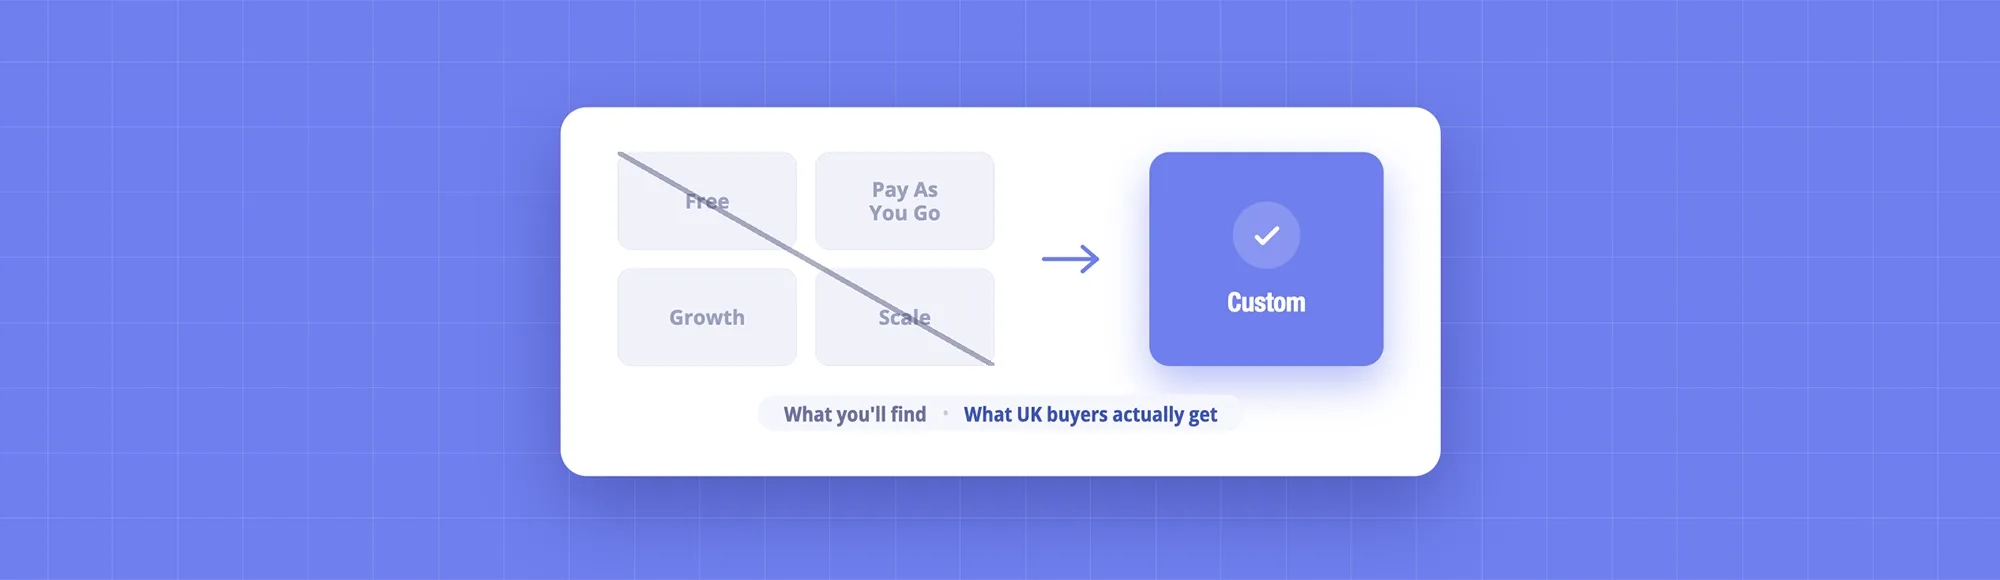
Plaid Pricing for UK Startups 2026
Plaid pricing looks straightforward until UK buyers request a quote. Unlike US customers, plaid api pricing and plaid pricing UK typically require custom contracts instead of self-serve plans. Learn what drives costs, how enterprise pricing works and what startups should evaluate before beginning an Open Banking procurement process with confidence today.
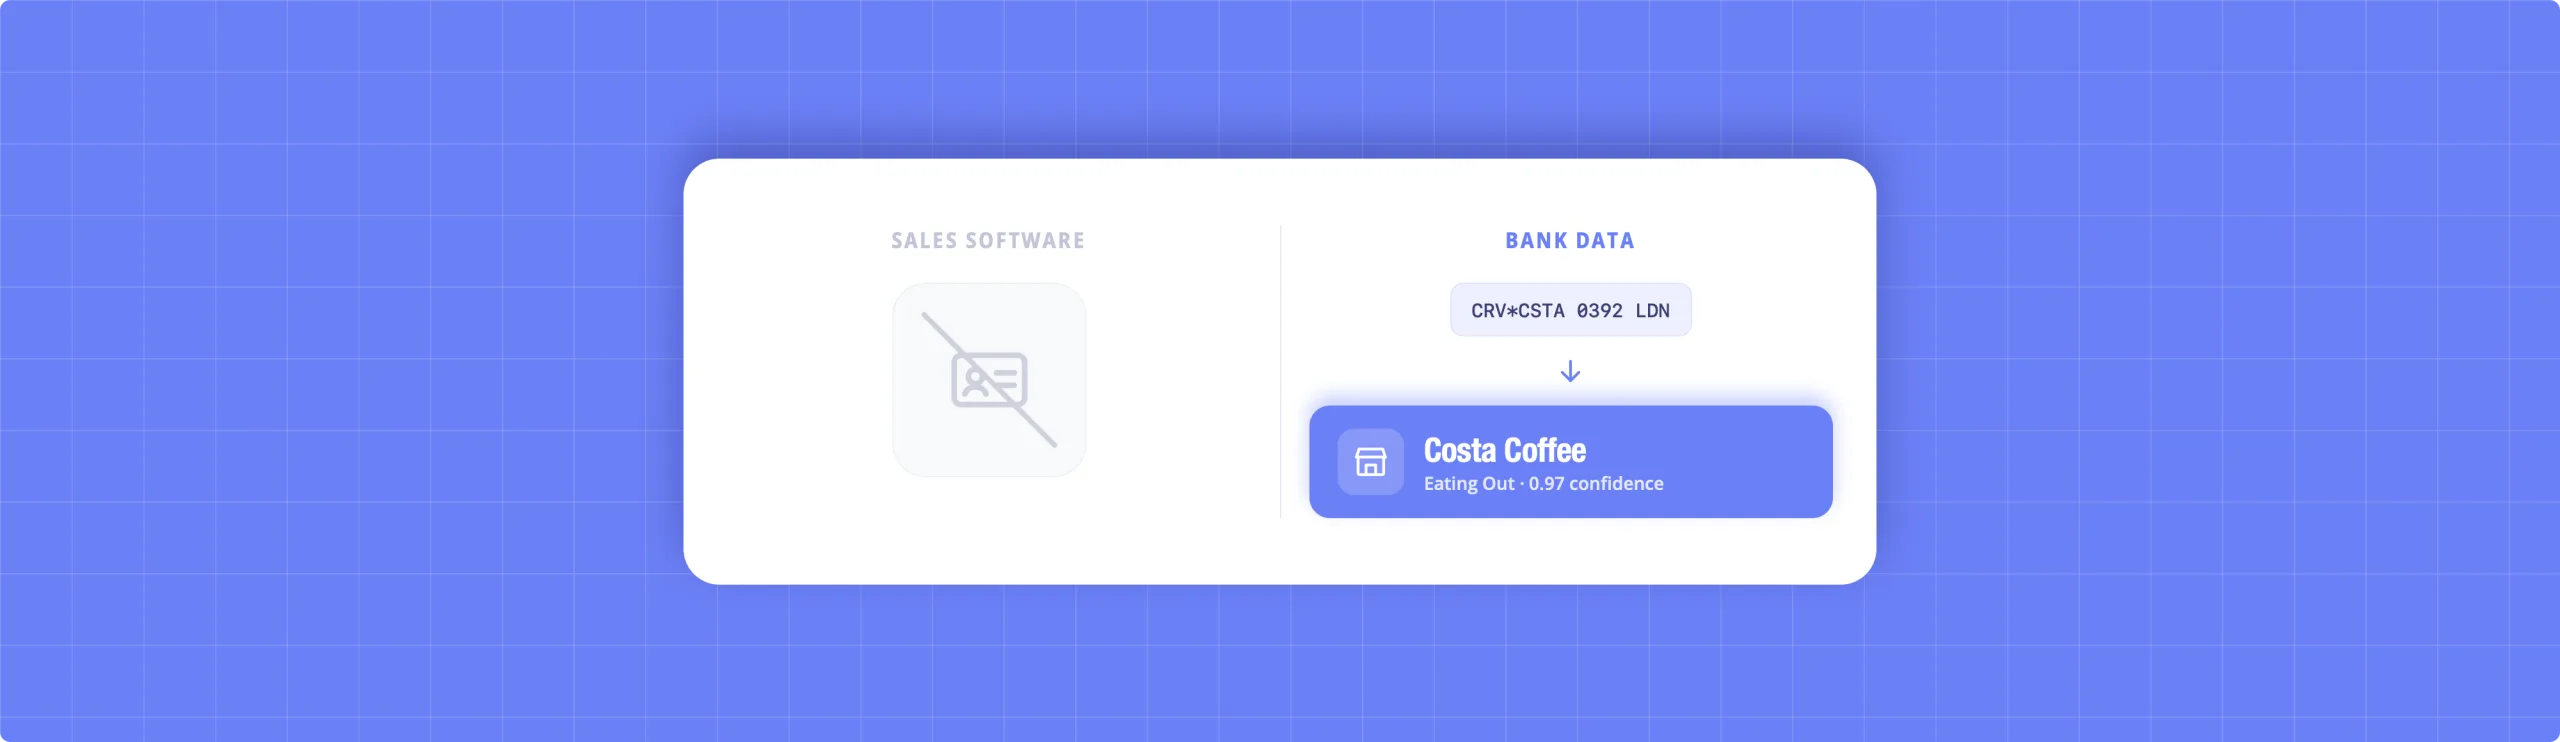
Bank Transaction Data Enrichment Tools: UK Comparison
Bank transaction data enrichment tools do a different job from the ZoomInfo-style results that dominate this search. This UK comparison covers the six tools that turn raw bank descriptors into verified merchants and categories: Finexer, Bud, Plaid Enrich, Tink, Yapily Data Plus and Salt Edge, and how to choose.
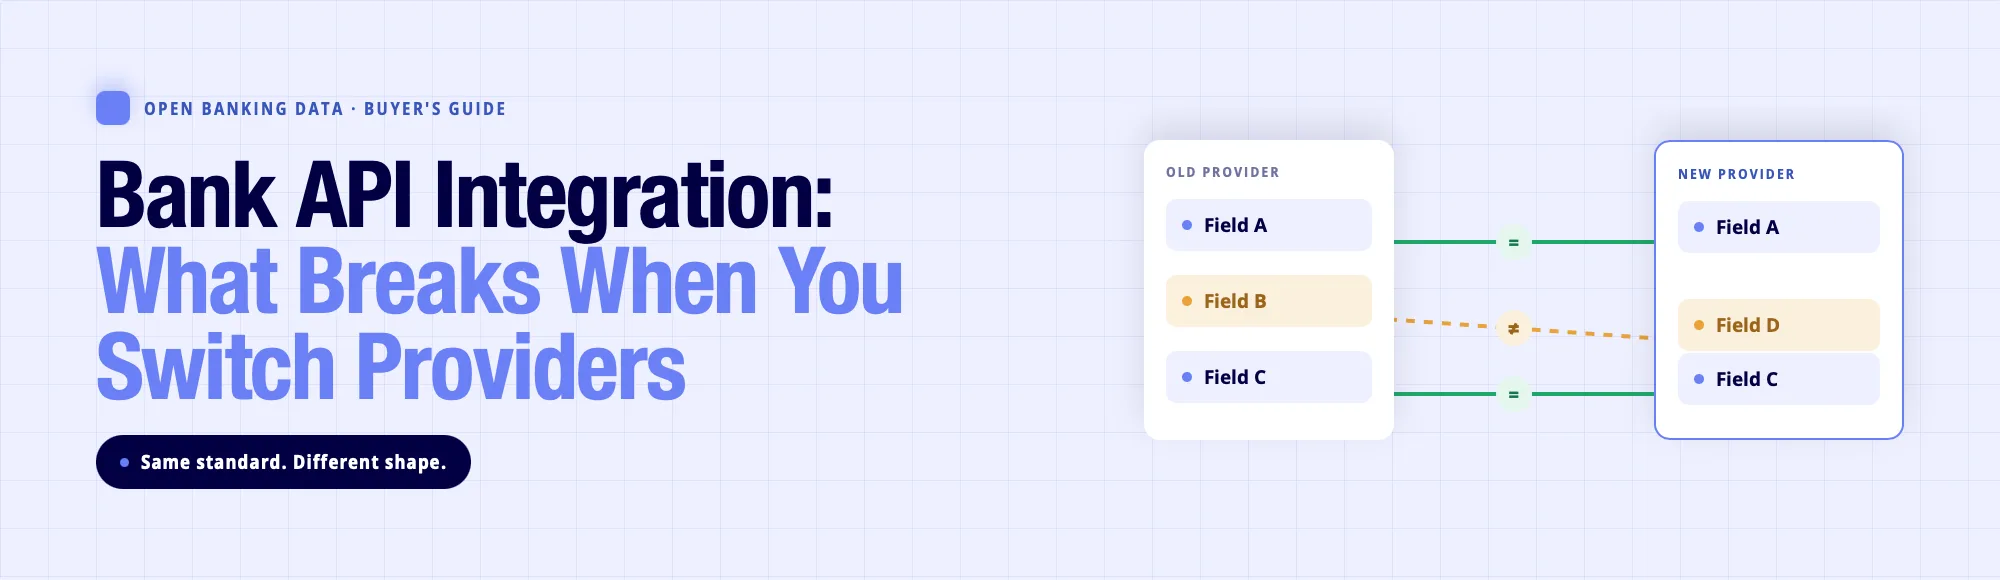
Bank API Integration: What Breaks When You Switch Providers
Switching bank API integration providers is riskier than a first-time build, because ten banks return ten variations of the same data standard, and migrations inherit whatever format quirks the old provider was quietly absorbing. This guide covers what breaks during a bank integration API migration, why format mismatches cause roughly a third of failures and…
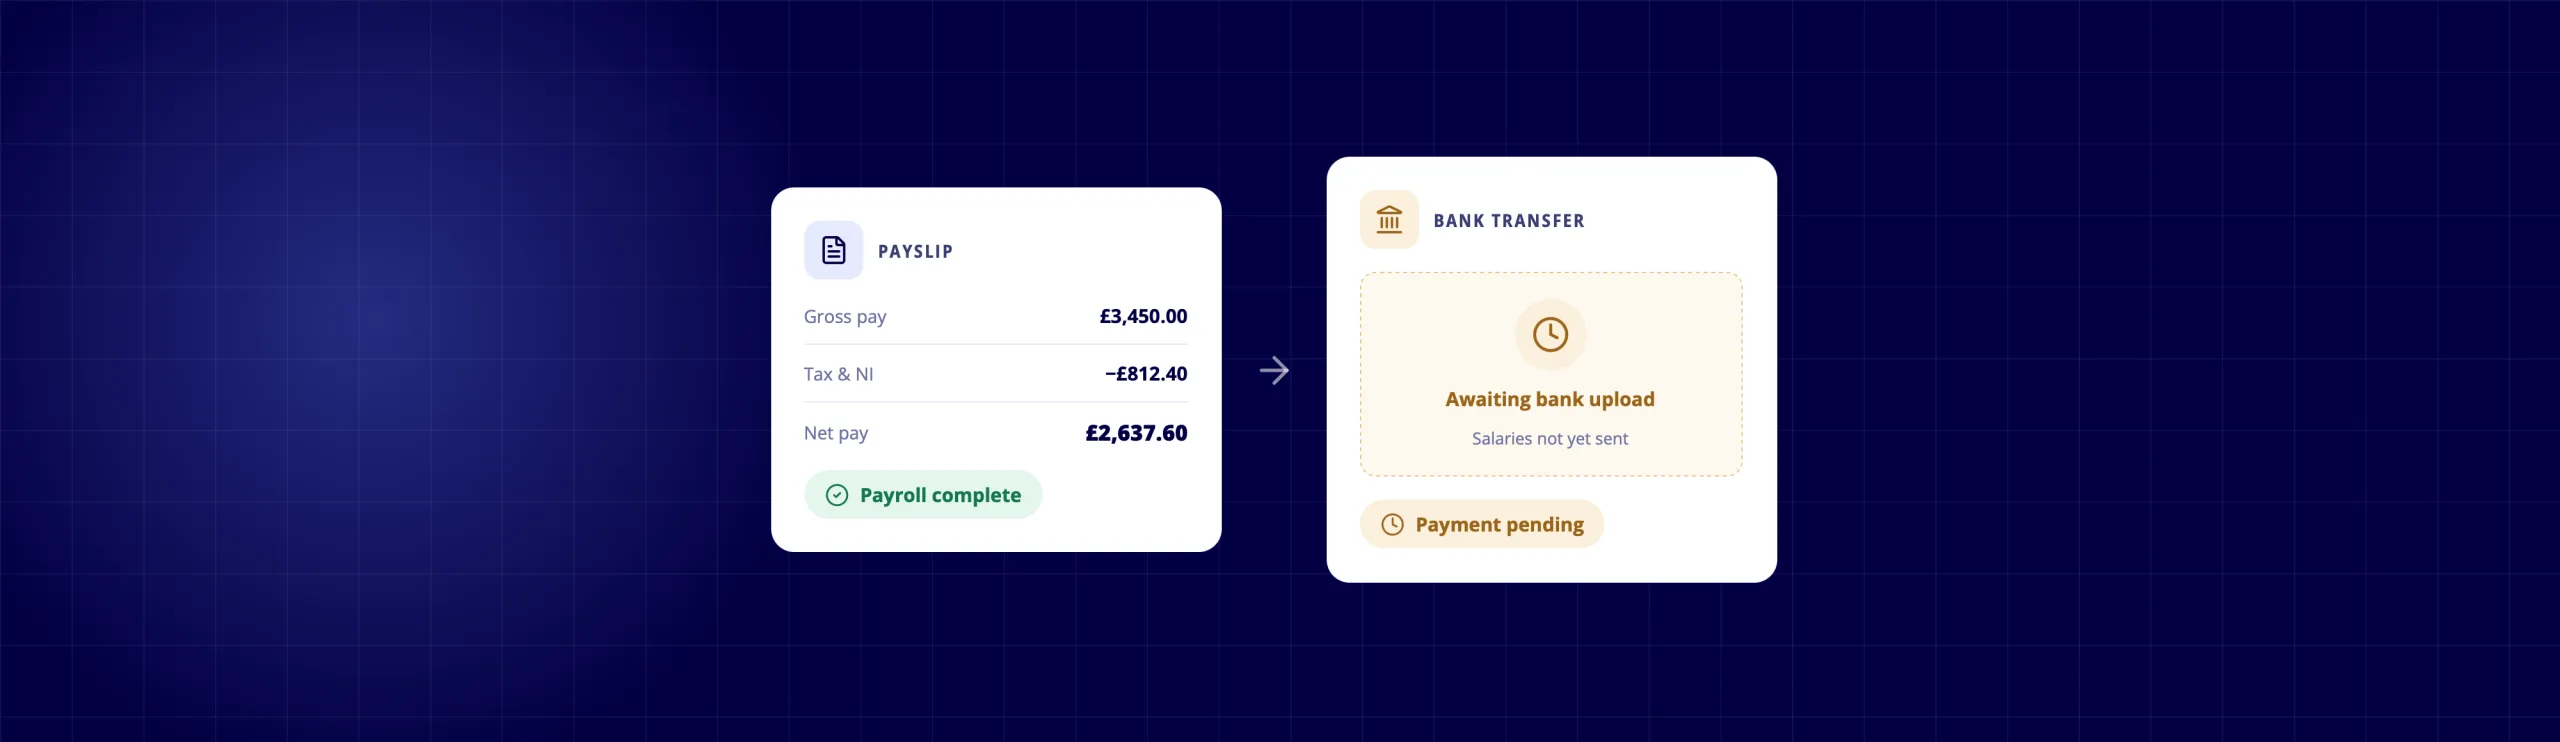
Smart Payroll Processing Payments: Automate Salary Payouts via Bank APIs
Compare Payroll Processing methods, from HMRC reporting to salary payments, and learn how modern payroll processing software automates calculations, RTI submissions and payment execution. Discover when BACS is sufficient, when Faster Payments adds value, and what employers should evaluate before choosing payroll software that grows with their business needs.
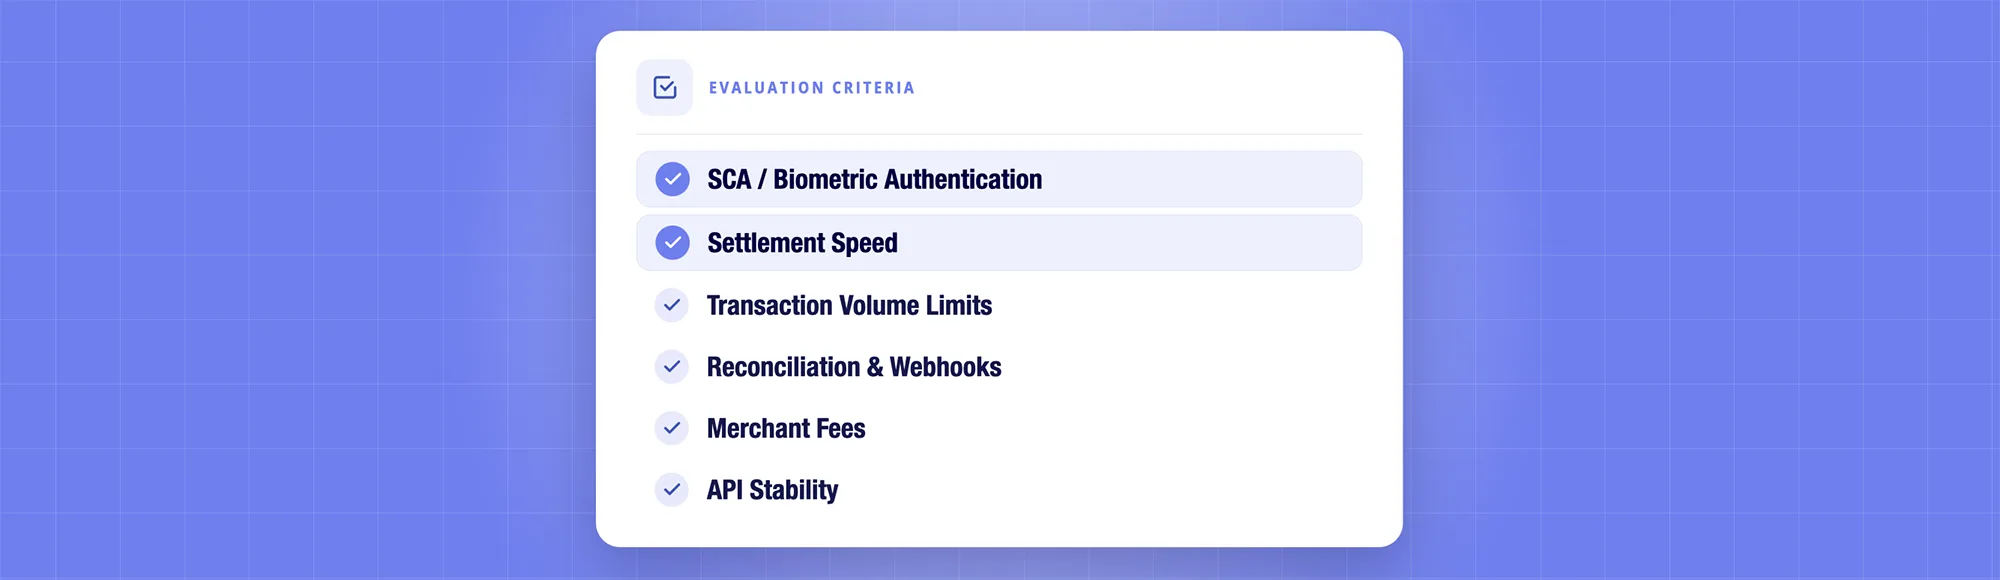
How to Compare Pay by Bank Providers in the UK
Not all Pay by Bank providers deliver the same experience. Learn how to compare settlement speed, authentication, API quality, merchant fees, and operational reliability before choosing a provider for your business.
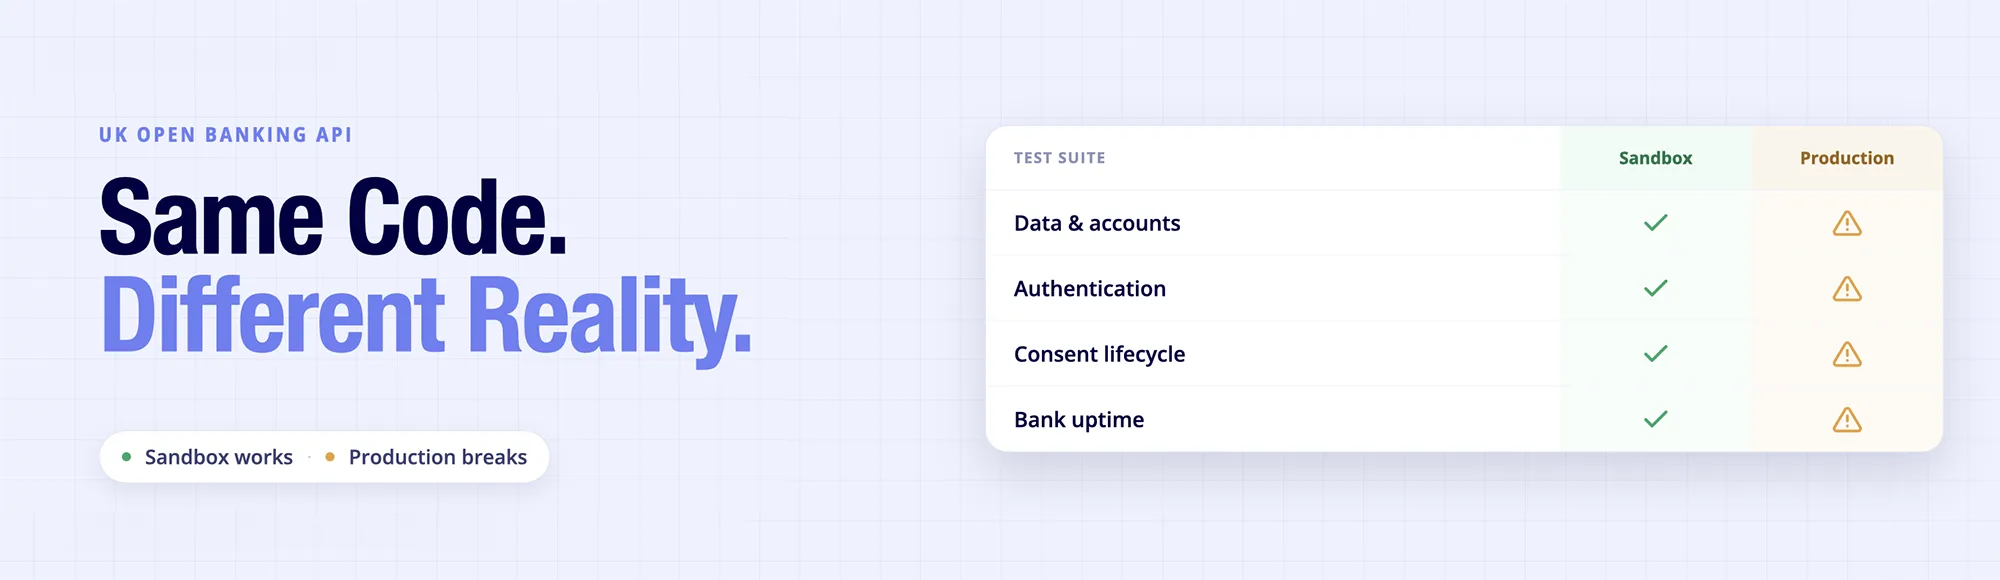
UK Open Banking API: Why Sandbox Works, Production Breaks
UK open banking API integrations pass every sandbox test and still break in production. The reason: sandbox tests your code, production tests the banks, and banks vary. This guide covers the CMA9 gap, the six differences that cause real failures, and the reliability checklist that closes them.
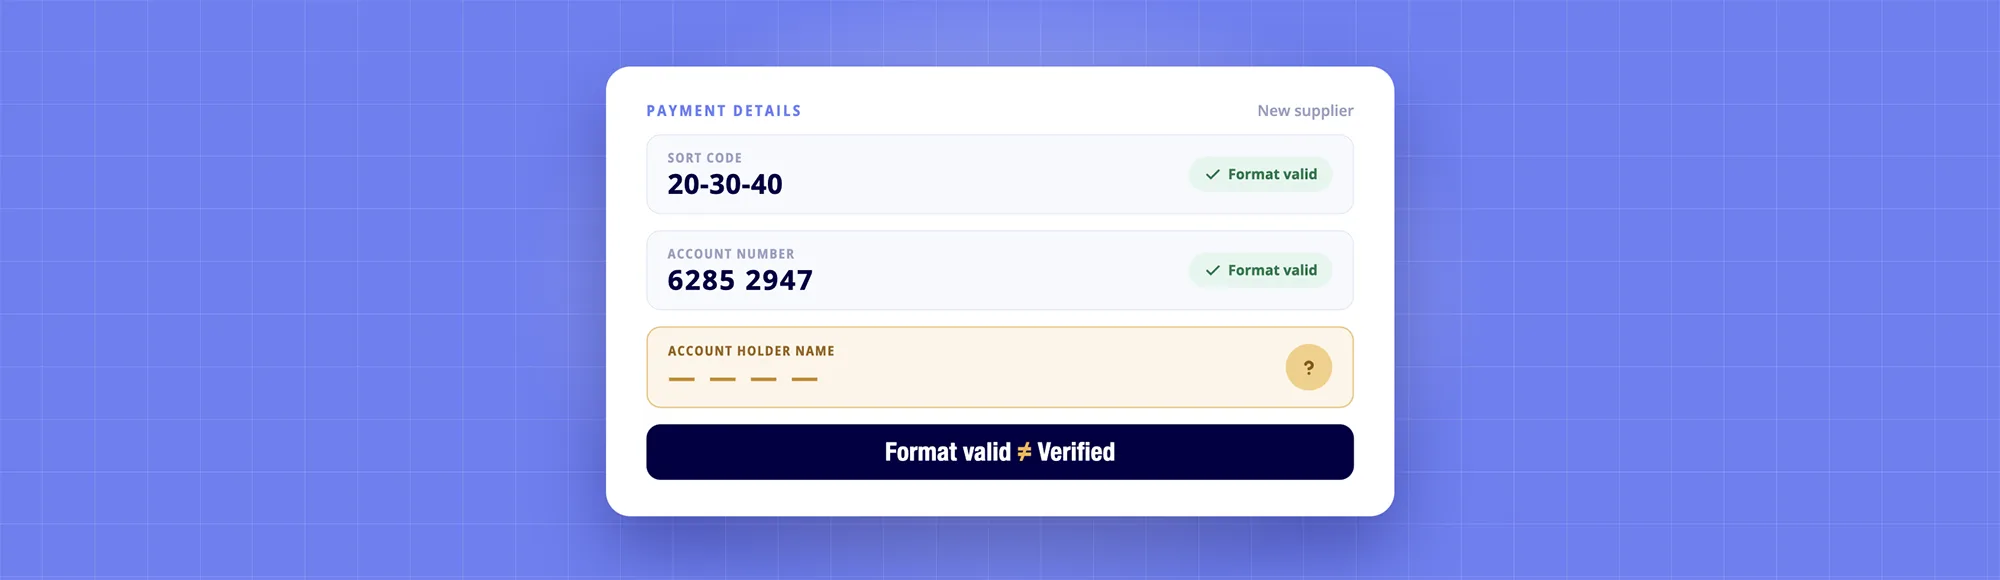
Bank Account Verification in the UK: How to Confirm Customer Details Instantly (Without Manual Checks)
A misdirected payment doesn’t announce itself, it just leaves quietly into an account that looks legitimate until it’s gone. This guide compares bank account verification methods pitted head to head: micro-deposits, Confirmation of Payee and instant bank account verification via Open Banking, so businesses choosing a bank account verification service know which one actually catches…
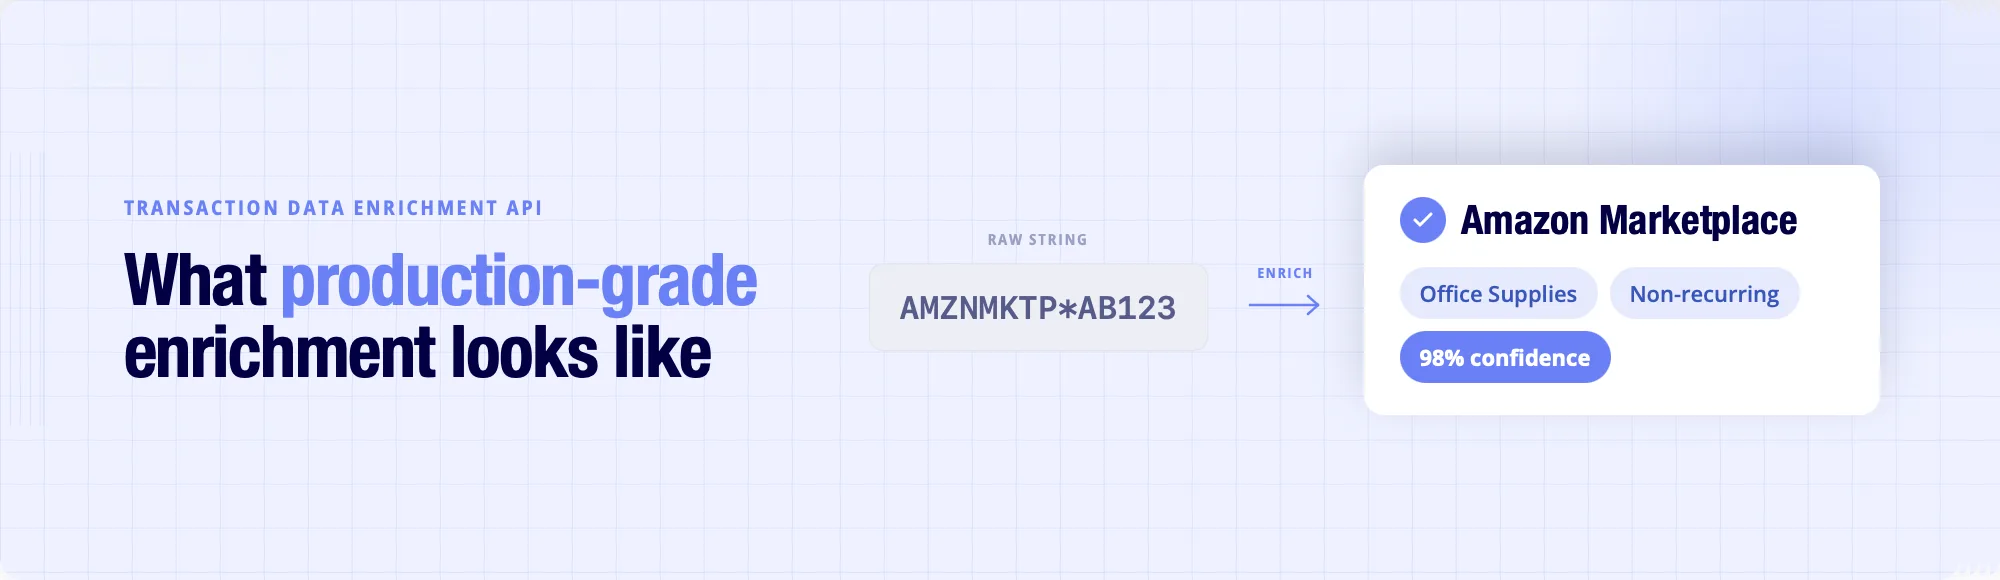
UK Transaction Data Enrichment API: Pricing & Accuracy
“AMZNMKTP*AB123” tells your reconciliation engine nothing. A transaction data enrichment API turns that string into Amazon Marketplace, Office Supplies, non-recurring, in one API call. This guide covers merchant-match accuracy, data enrichment API pricing models, structured JSON schema across UK banks and what separates production-grade enrichment from a categorisation feature bolted onto a data feed.
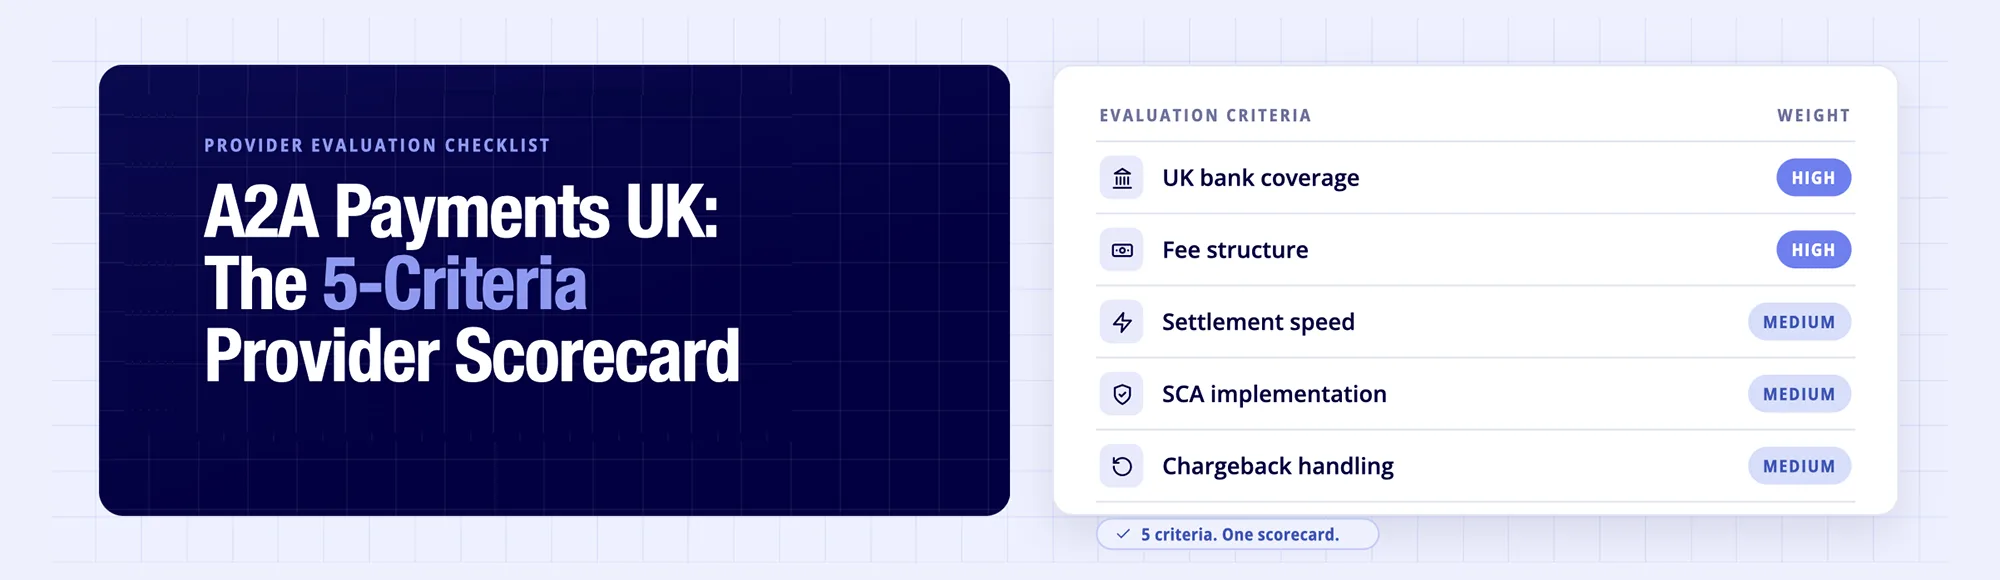
A2A Payments UK: Provider Evaluation Checklist
UK A2A adoption trails the EU significantly, and the gap usually comes down to picking the wrong provider. This checklist scores account-to-account payments providers on fee structure, settlement speed, chargeback handling and SCA implementation, so platforms can compare account-to-account (A2A) payments options on evidence, not marketing copy.
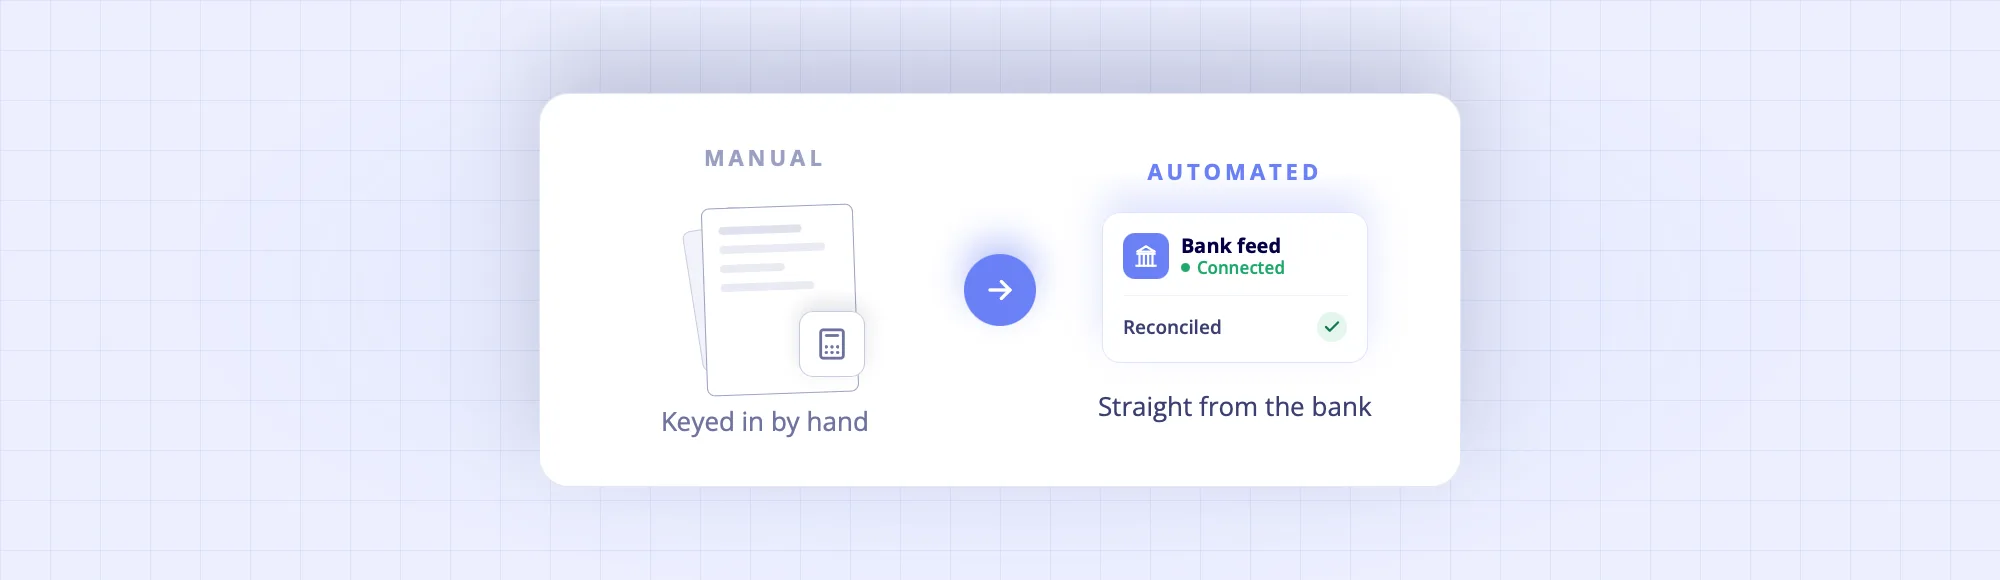
Bookkeeping Automation Software in the UK: What Actually Powers It
Compare bookkeeping automation software with manual bookkeeping to see how OCR receipt capture, bank-feed reconciliation and MTD compliance reduce repetitive work. Learn why accounting process automation increasingly depends on reliable bank data, helping UK businesses spend less time on admin and more time running their business with confidence.
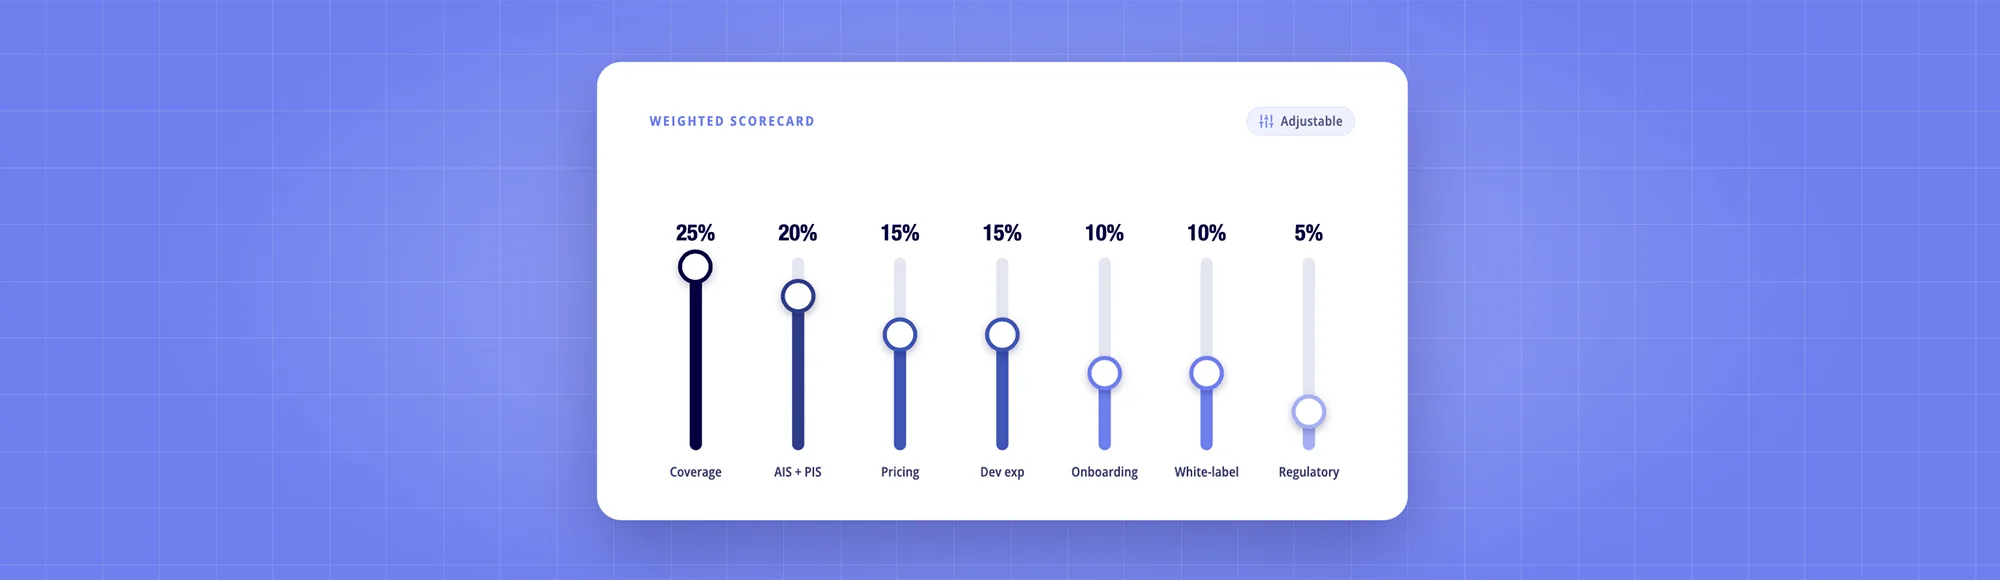
Open Banking Providers UK: The Evaluation Framework Buyers Actually Need
Compare open banking providers using a practical evaluation framework instead of another vendor list. Learn how open banking solution providers differ across bank coverage, AIS and PIS capabilities, onboarding, pricing, and white-label deployment so your team can shortlist providers with confidence and choose infrastructure that matches long-term product goals.
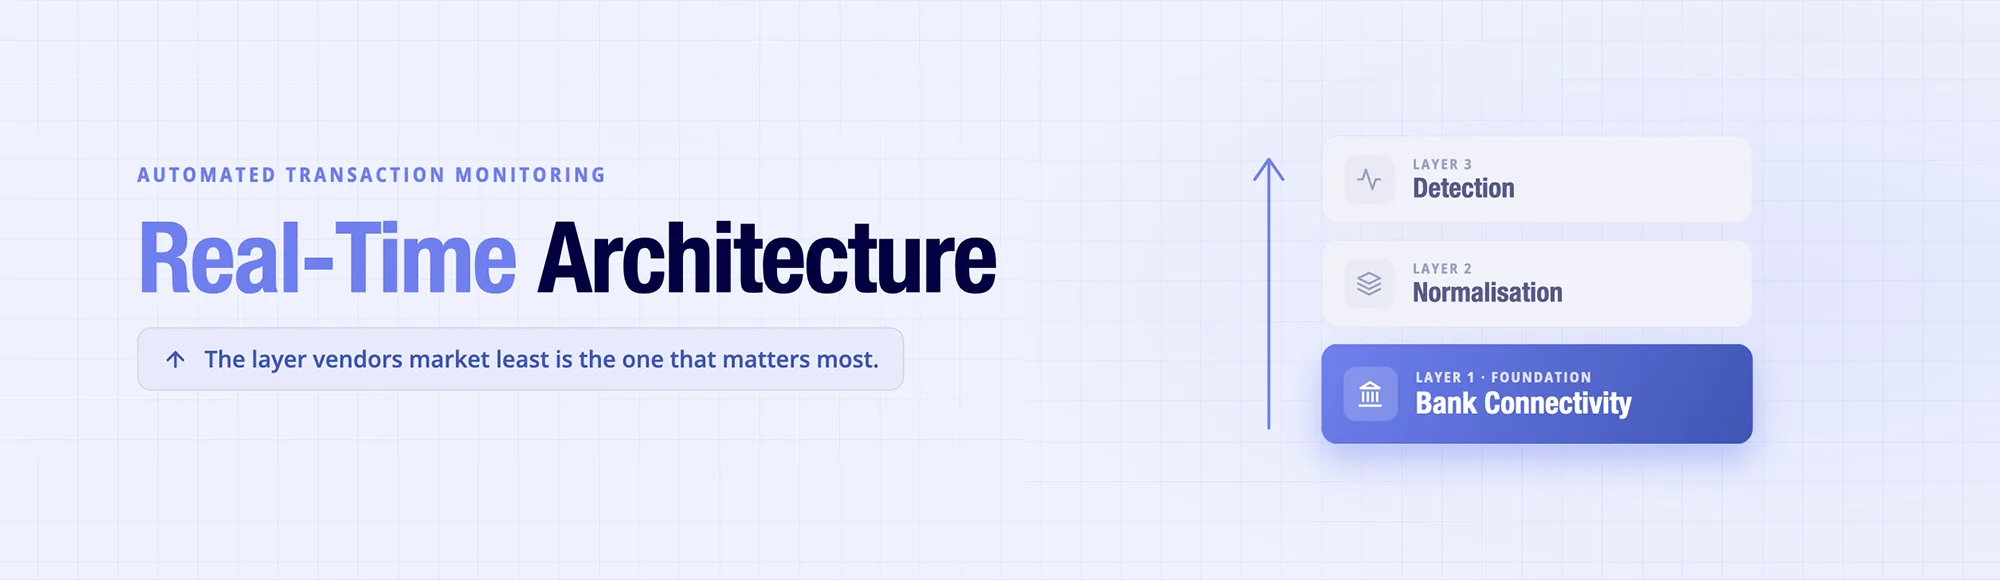
Automated Transaction Monitoring: Real-Time Architecture
Automated transaction monitoring only works if the bank data arriving is complete and current, not a batch file from last night. This guide breaks down the webhook architecture behind real production automated transaction monitoring systems, from payload structure to latency, and why partial bank coverage quietly degrades detection regardless of how sophisticated the monitoring logic…
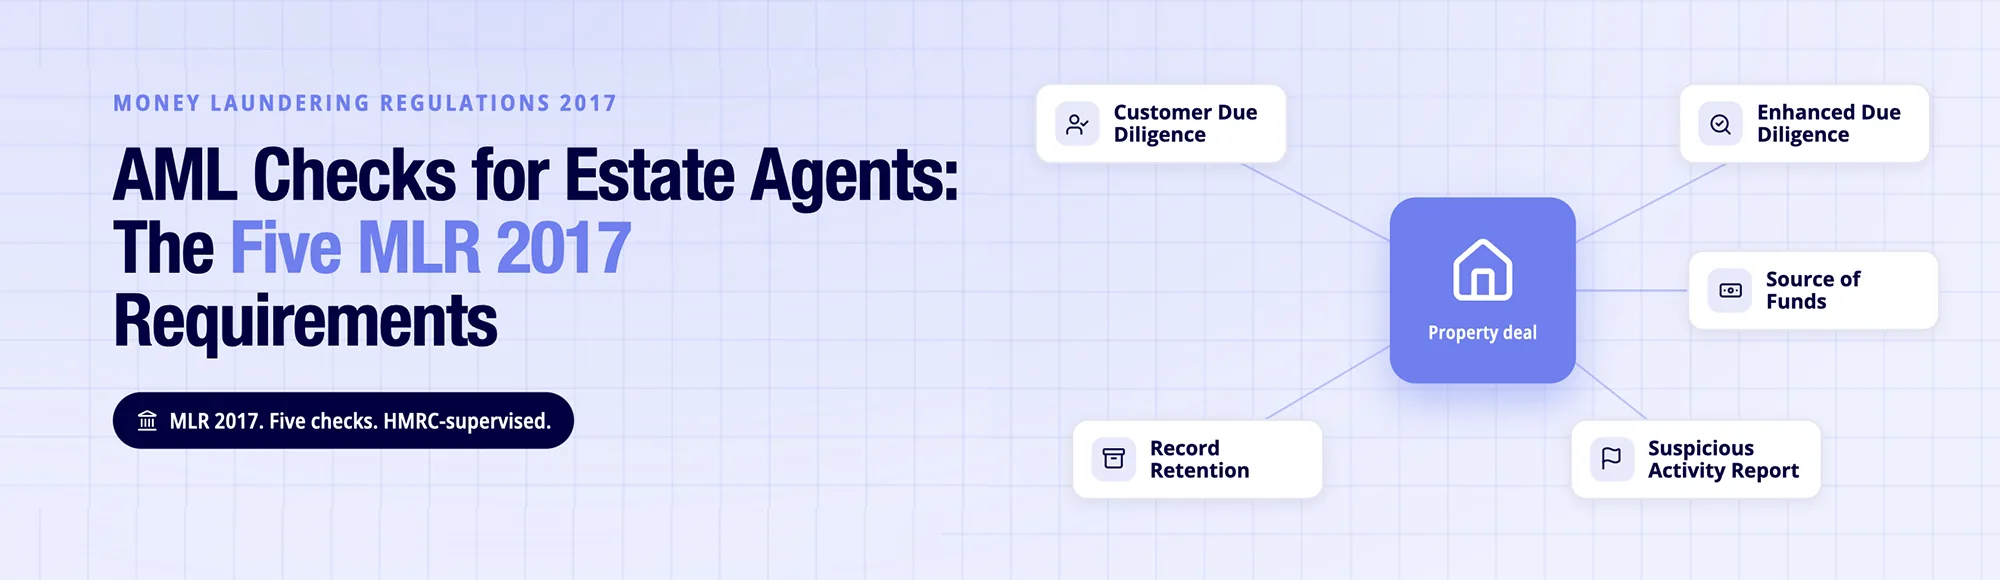
AML Checks for Estate Agents: MLR 2017 Requirements
AML checks for estate agents are set by MLR 2017: customer due diligence, enhanced due diligence, source of funds and 5-year records, supervised by HMRC. This guide covers the exact triggers, the red flags inspectors expect you to catch, current penalty rounds, and what changes in 2026 for UK property firms.