Category: Open Banking
API for Bank Transactions: Evaluation Guide (UK 2026)
Choosing an API for bank transactions requires understanding failure modes, not just comparing features. This guide explores how providers differ in coverage gaps, webhook consistency, data quality, regulatory licensing, and real-world reliability, helping you build an integration that continues to perform when transactions, customers, and compliance are on the line.
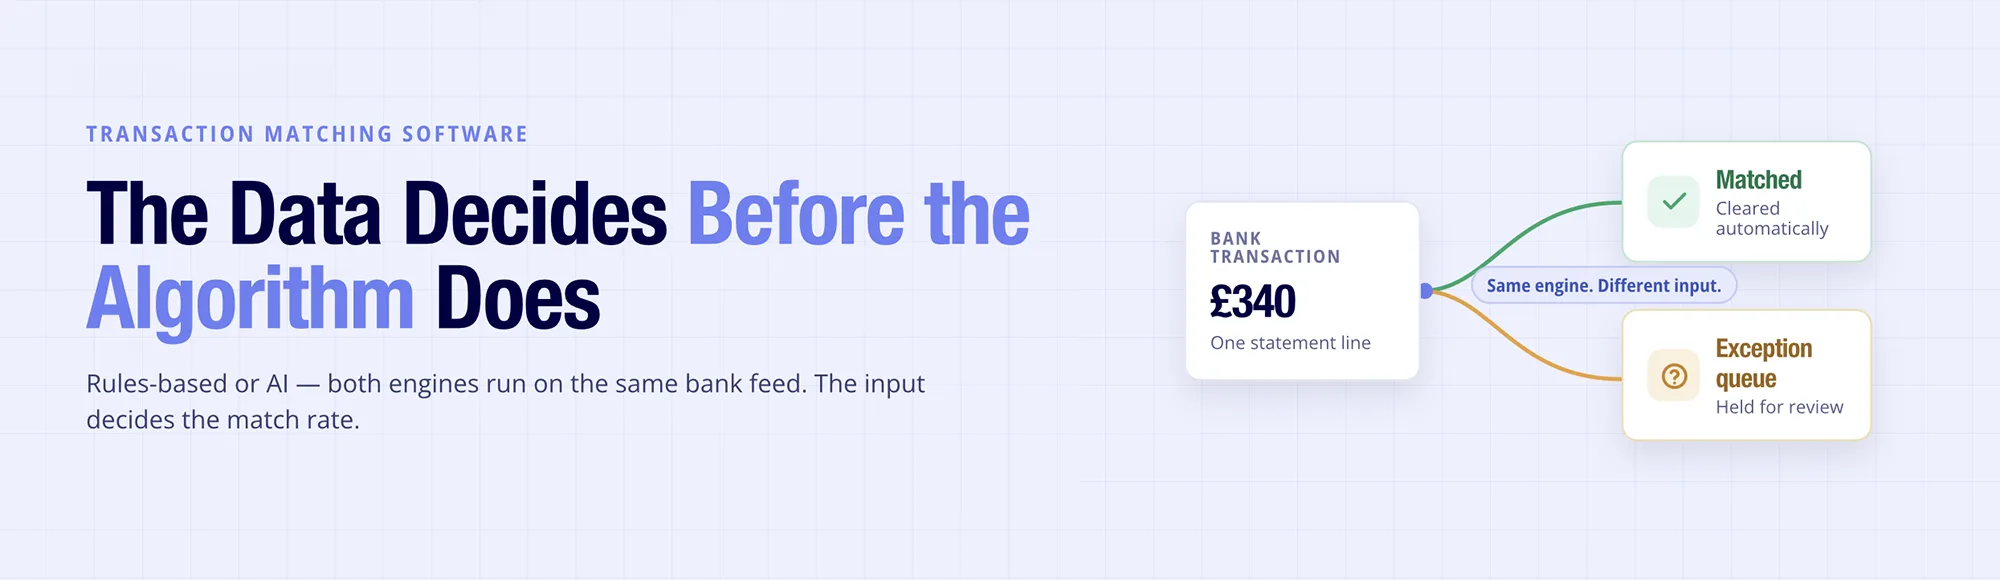
Why AI Transaction Matching Still Fails Without Structured Bank Data
Transaction matching software fails on data before it fails on logic. This technical explainer covers rules-based versus AI matching, why partial payments and batches break deterministic engines, the clean-data assumption enterprise close tools make, and why fixing the bank-data layer lifts every matching engine on your shortlist at once.
Bulk Payments UK: A Buying Checklist for Platforms
Bulk payments let a platform send one instruction and pay hundreds of recipients, but the provider you choose decides whether your users get per-payment status or a three-day wait. This UK buying checklist covers rails, coverage, pricing and integration, so platform teams can evaluate providers with the right questions.
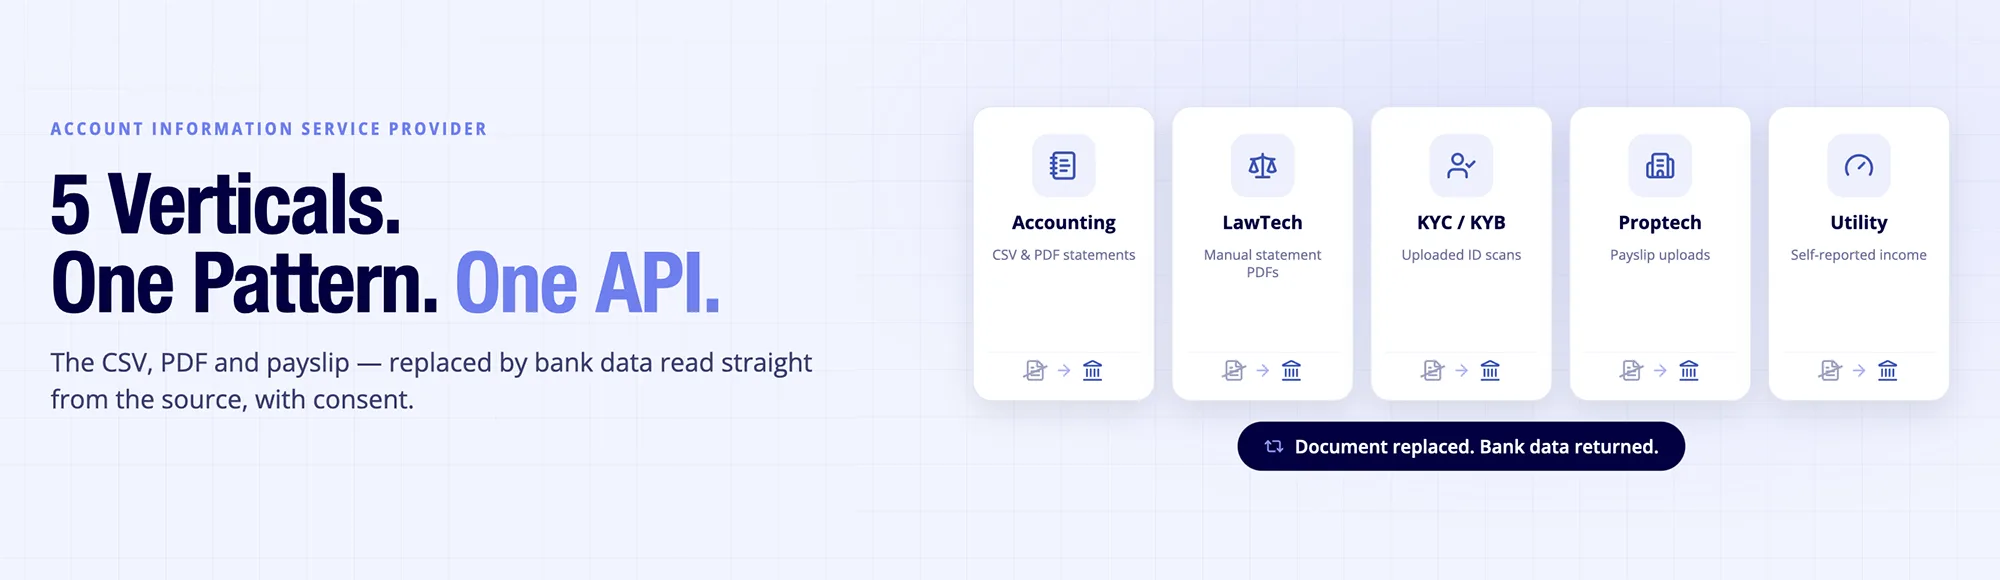
Account Information Service Provider: 5 Real Examples
Every account information service provider example you’ve read stops at the regulatory definition. This guide skips that and shows five real ones: an accounting SaaS reconciling client transactions, a LawTech platform verifying source of funds, and three more. See exactly what an account information services provider returns, and where it fits your stack.
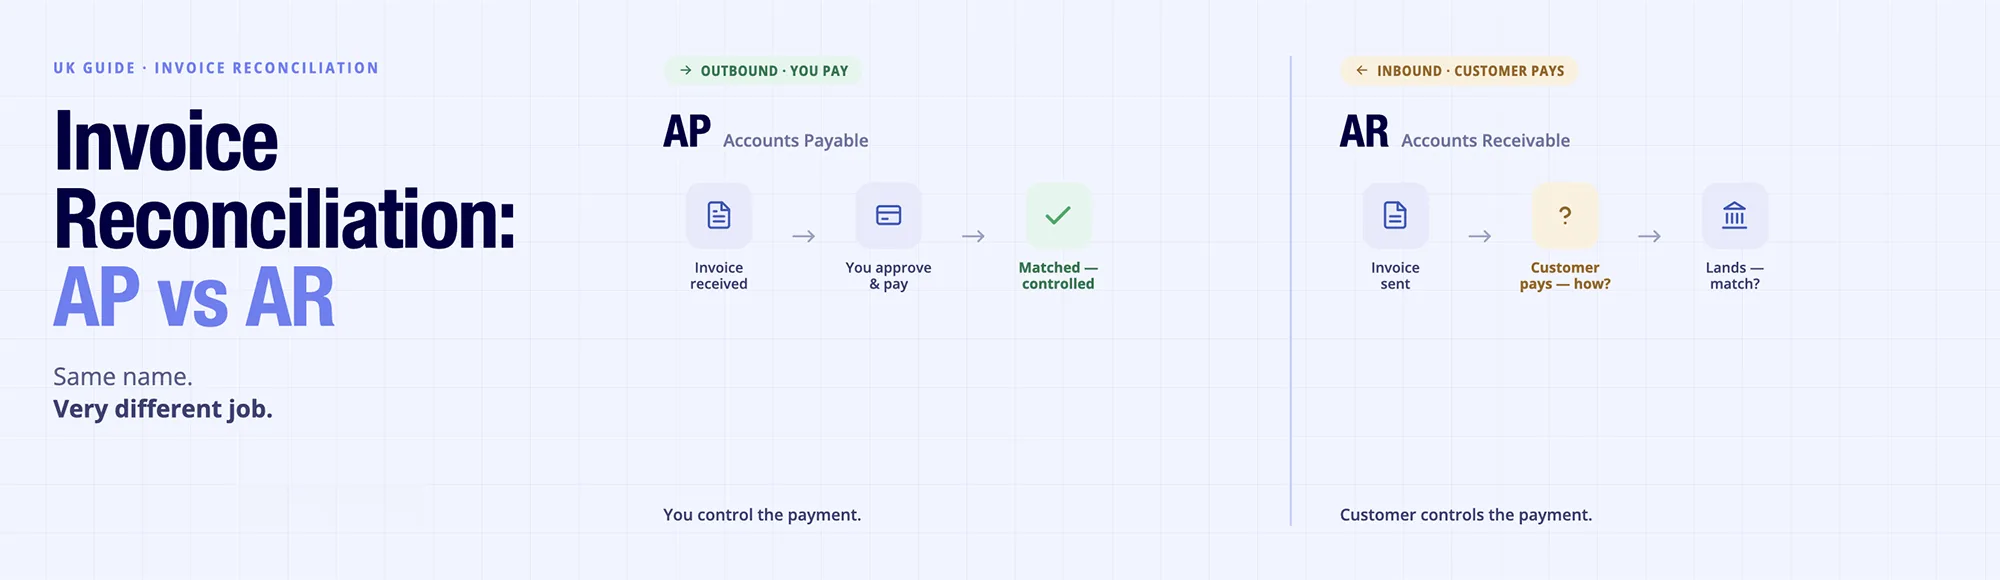
Why Invoice Reconciliation Still Breaks in Modern Finance Workflows
Invoice reconciliation covers two different jobs: checking supplier invoices before you pay them (AP) and matching incoming payments to the invoices you’ve issued (AR). This UK guide explains both sides, the matching methods involved, and a step-by-step process for reconciling invoices accurately with current government data and the 2026 MTD context.
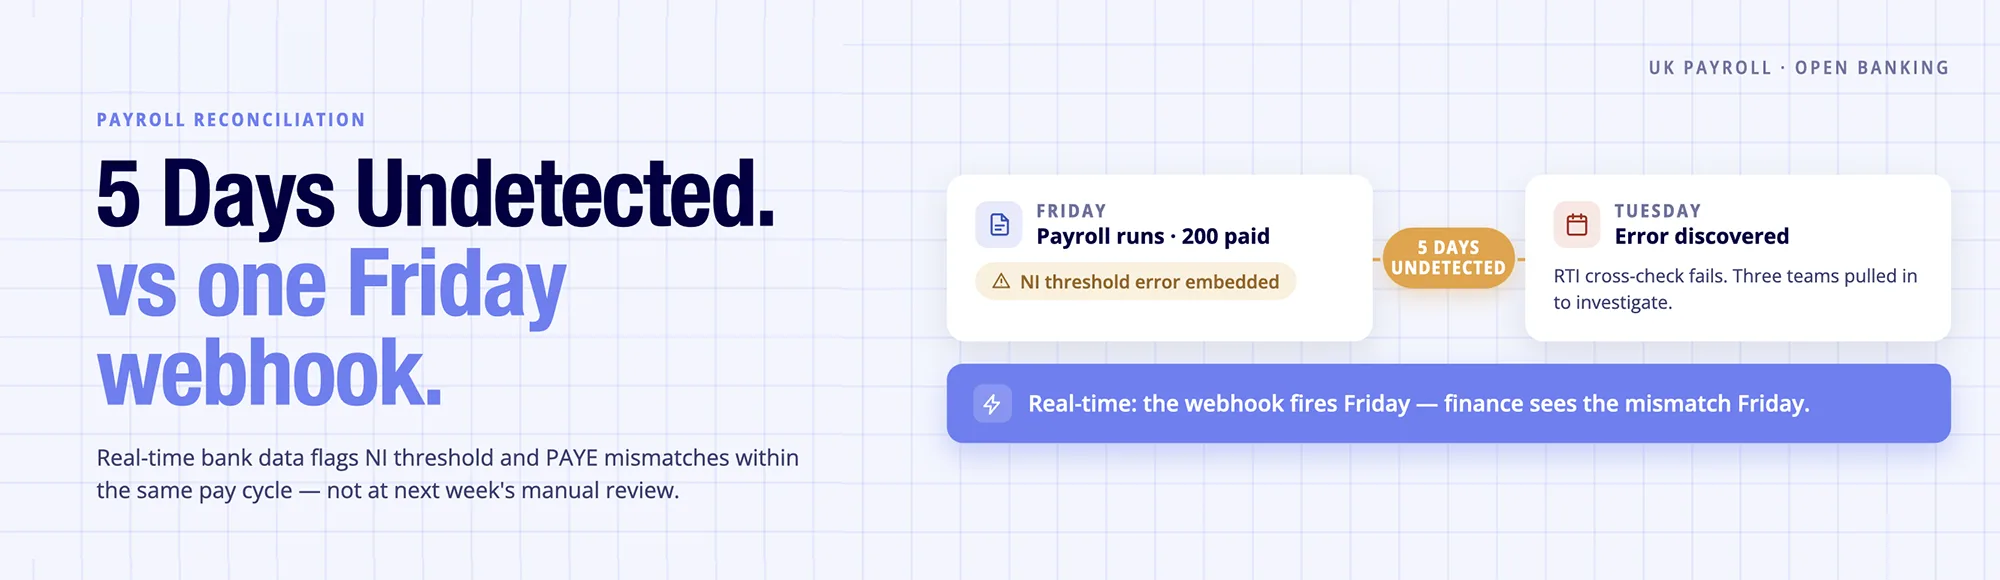
Payroll Reconciliation: Real-Time Bank Data Fixes This
A miscalculated NI threshold sends one employee’s payroll reconciliation into a three-hour manual investigation. This guide walks you through how payroll reconciliation actually breaks, checkpoints to run before, during and after each pay cycle and how real-time bank data helps teams automate payroll payments and confirm PAYE and RTI matches without waiting for next-day bank…
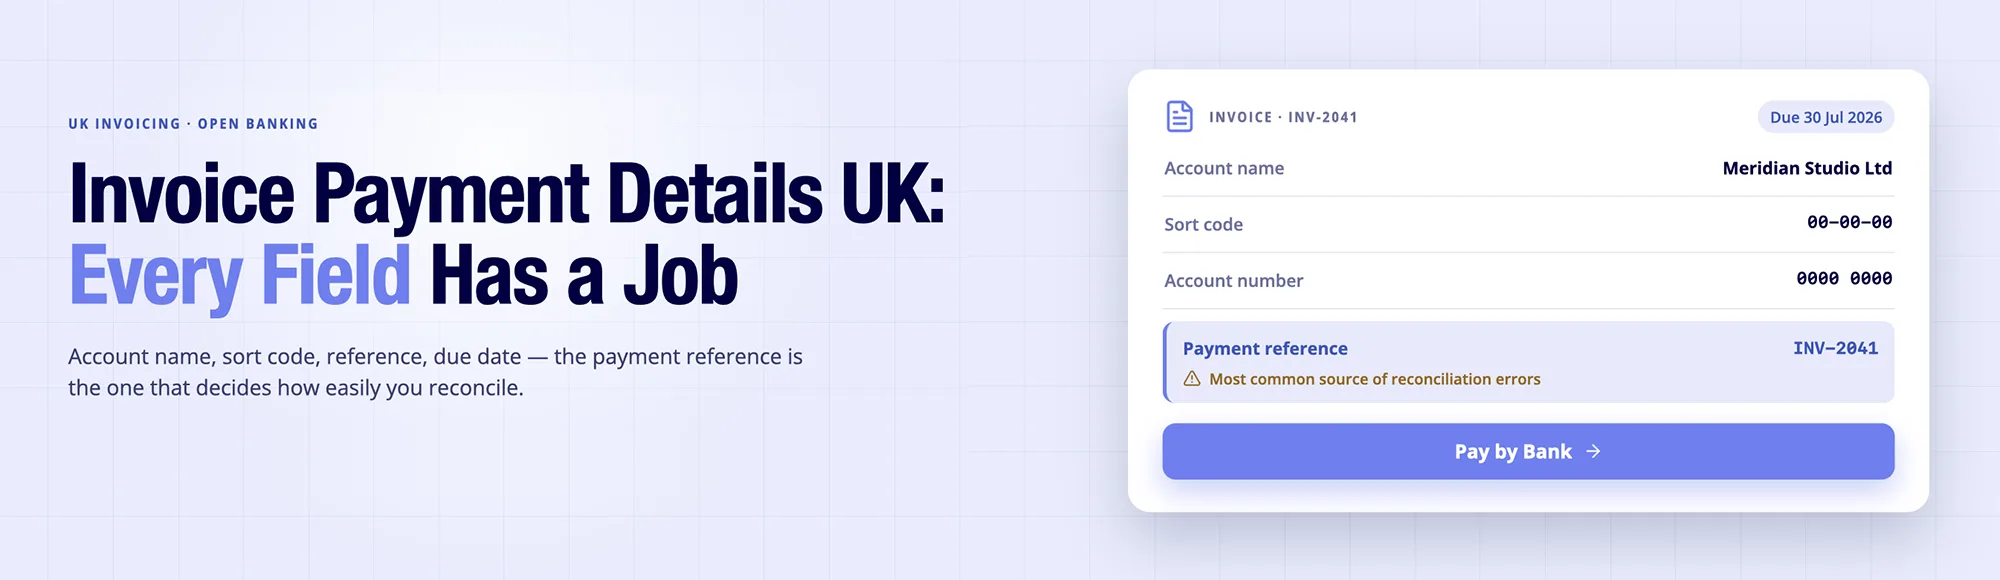
Invoice Payment Details UK: What Every Invoice Must Include
Invoice payment details explain exactly how customers should pay an invoice. Learn which invoice bank details UK businesses should include, why payment references matter for accurate reconciliation, what information every invoice should contain, and how Open Banking Pay by Bank reduces manual payment errors while simplifying customer payments.
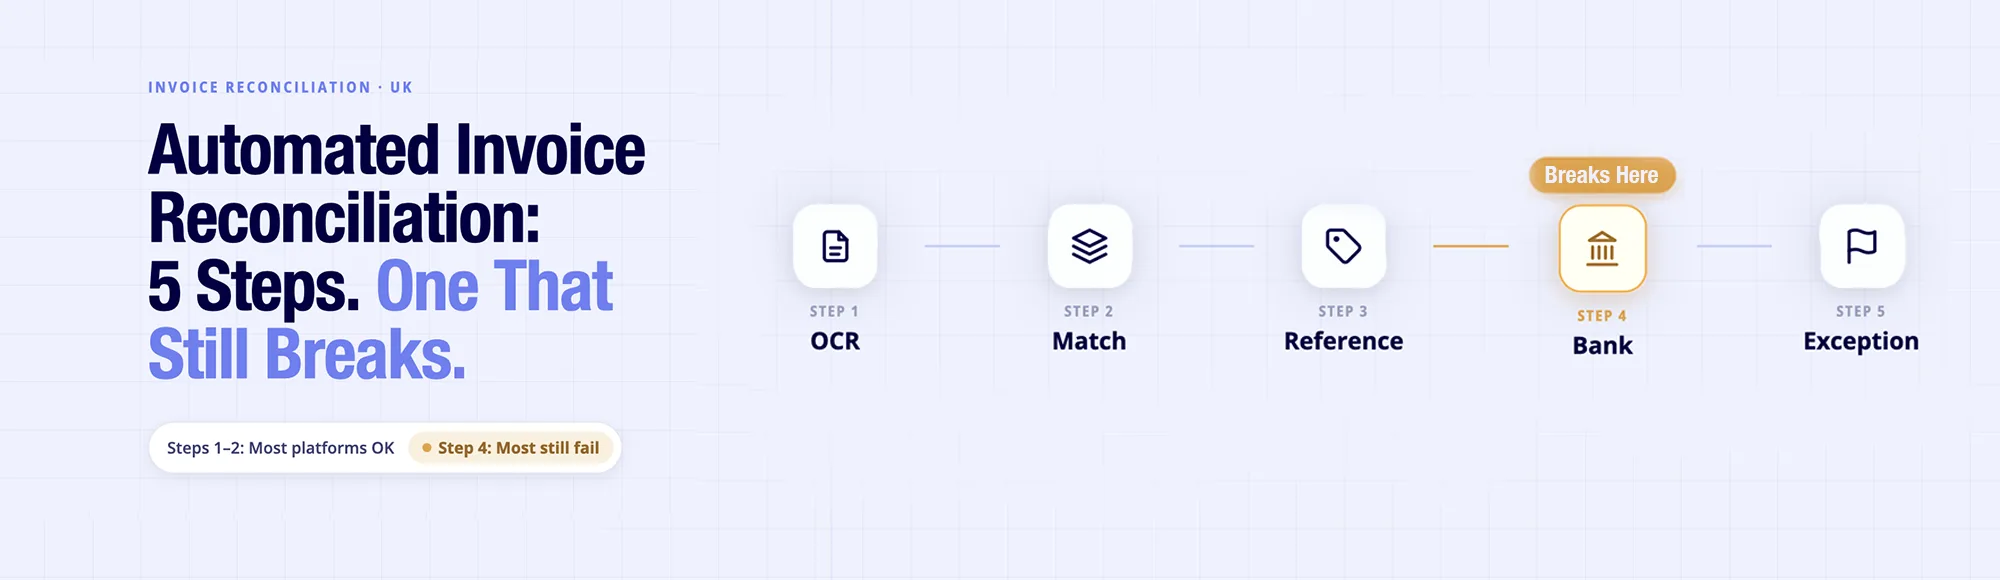
Automated Invoice Reconciliation: The 5-Step UK Process Flow
Automated invoice reconciliation only works when the invoice reconciliation process flow is built correctly from the start. This guide breaks the process into five numbered steps: OCR extraction, three-way matching, payment initiation, bank confirmation, and exception routing, so UK finance teams can see exactly where automation succeeds and where most platforms still fail.
Global Payout Solution: UK Platform Infrastructure Guide
Choosing the right global payout solution affects settlement speed, FX costs, and payment visibility. Compare five leading providers, including Tipalti, Trolley, Wise, Airwallex, and Finexer, across API capabilities, supported corridors, per-payout tracking, and infrastructure to find the best fit for your platform.
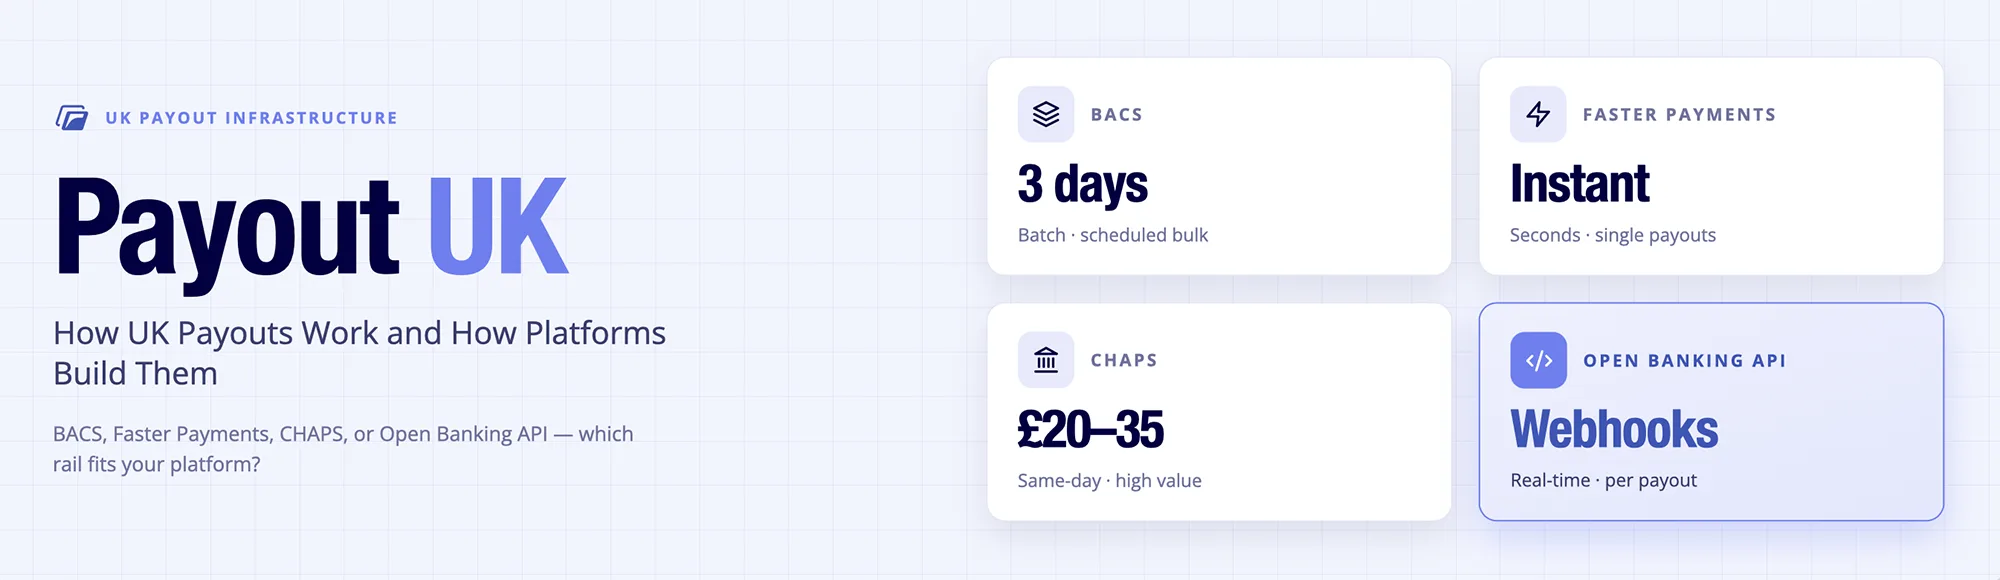
Payout UK: How UK Payouts Work and How Platforms Build Them
Discover how payout UK infrastructure works for businesses and platform builders. Compare BACS, Faster Payments, CHAPS, and Open Banking APIs to understand settlement speeds, payment visibility, and automation, helping you choose the right approach for high-volume, scalable payouts across the UK.
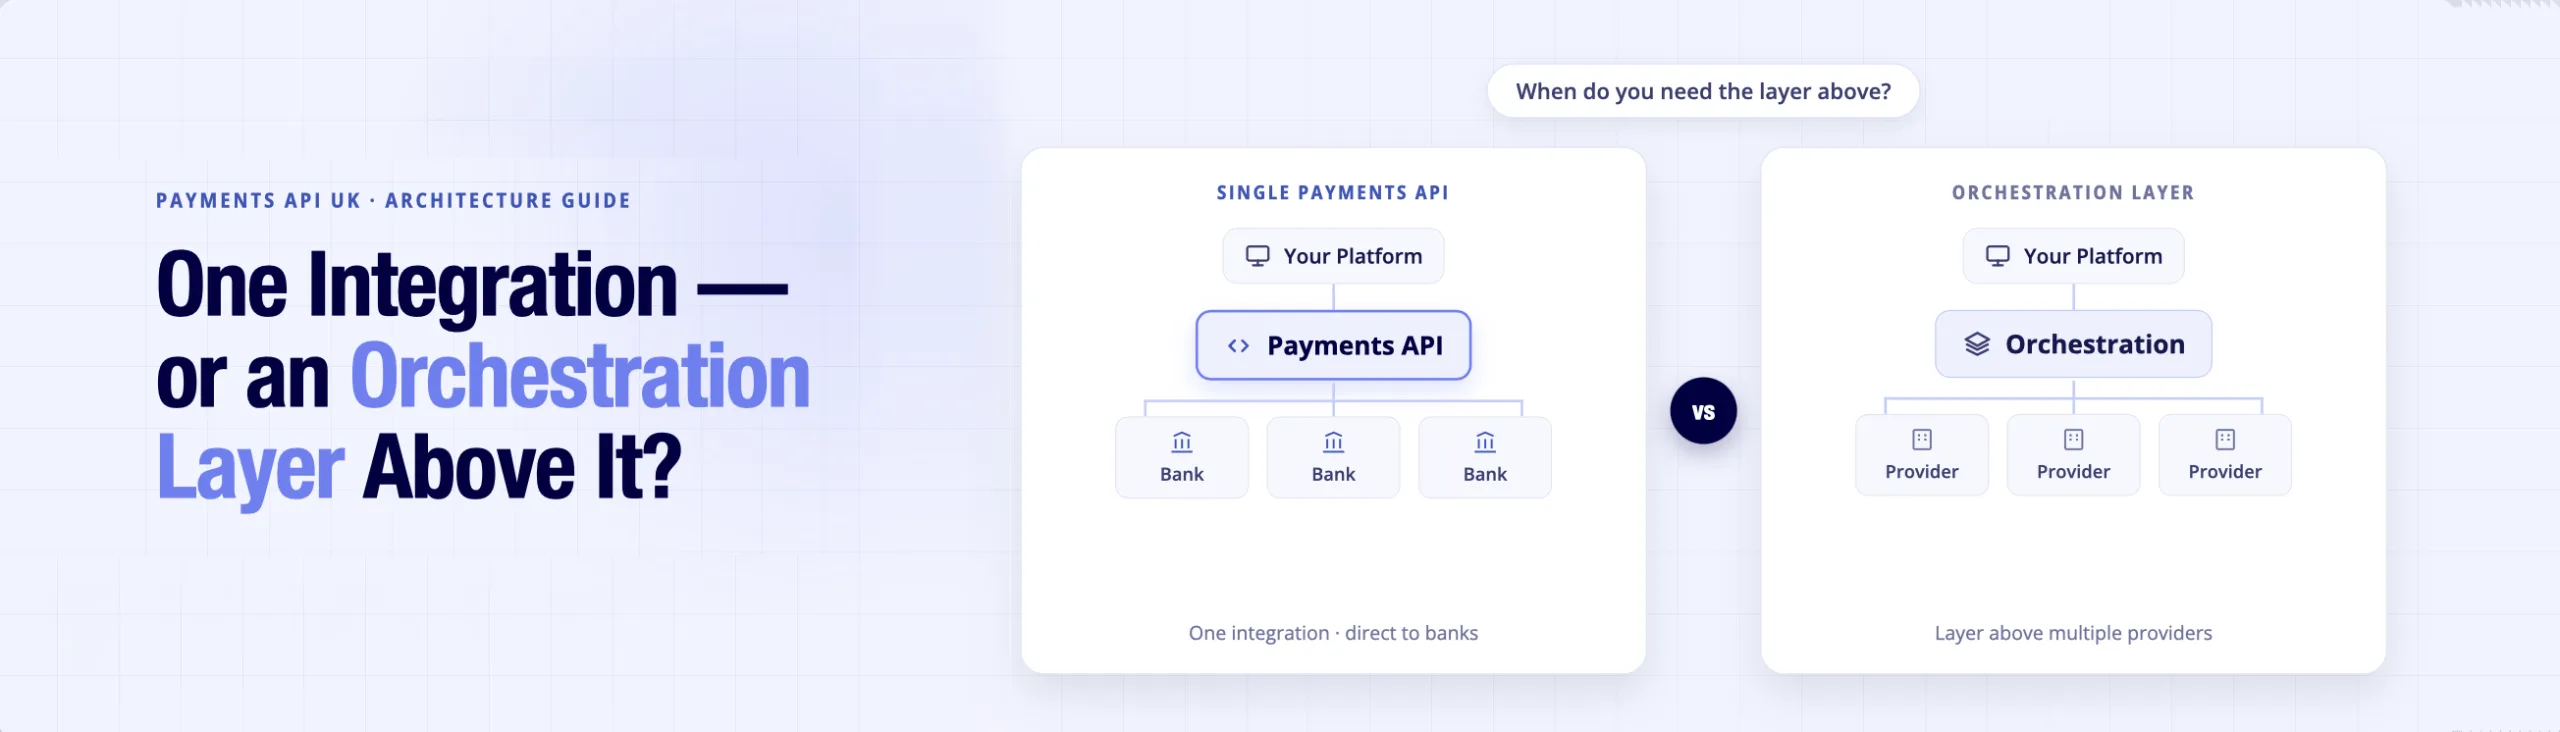
Payments API UK: What It Is and How Orchestration Extends It
Not every platform needs payment orchestration from day one. Learn the difference between a payments API and an orchestration layer, how each fits into your payment architecture, and when UK businesses should move beyond a single provider for greater resilience and scalability.
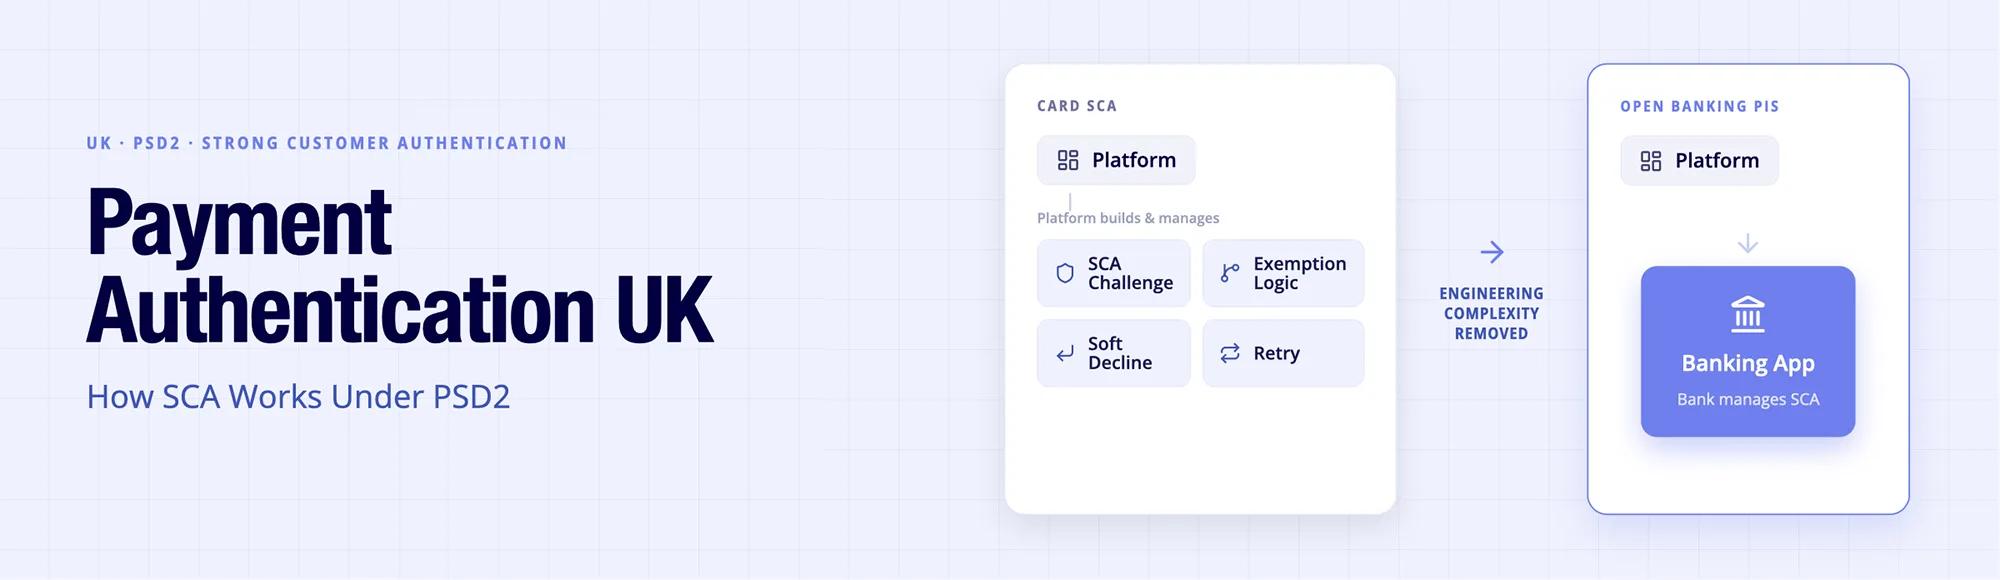
Payment Authentication UK: How SCA Works Under PSD2
Learn how payment authentication works under PSD2, when strong customer authentication (SCA) is required for UK electronic payments, and how card payments differ from Open Banking Pay by Bank. Understand platform responsibilities, SCA exemptions and why bank-managed authentication simplifies Open Banking payment flows.
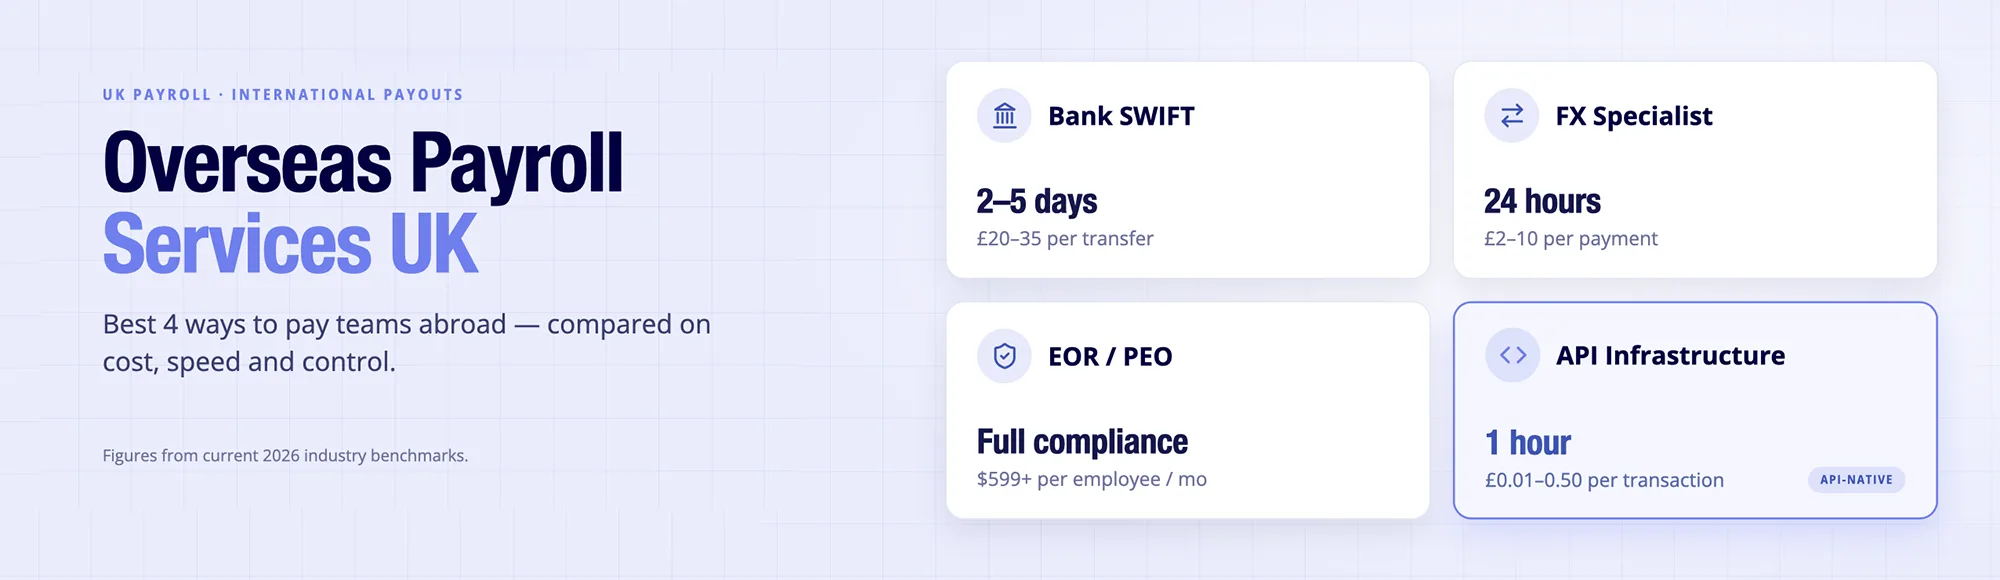
Overseas Payroll Services UK: Best 4 Ways to Pay Teams Abroad
Paying international employees and contractors involves more than simply sending money abroad. Compare four overseas payroll payment methods, including SWIFT, Wise, Airwallex, and Open Banking APIs to understand their costs, settlement speed, payment visibility, and suitability for UK businesses managing global teams.
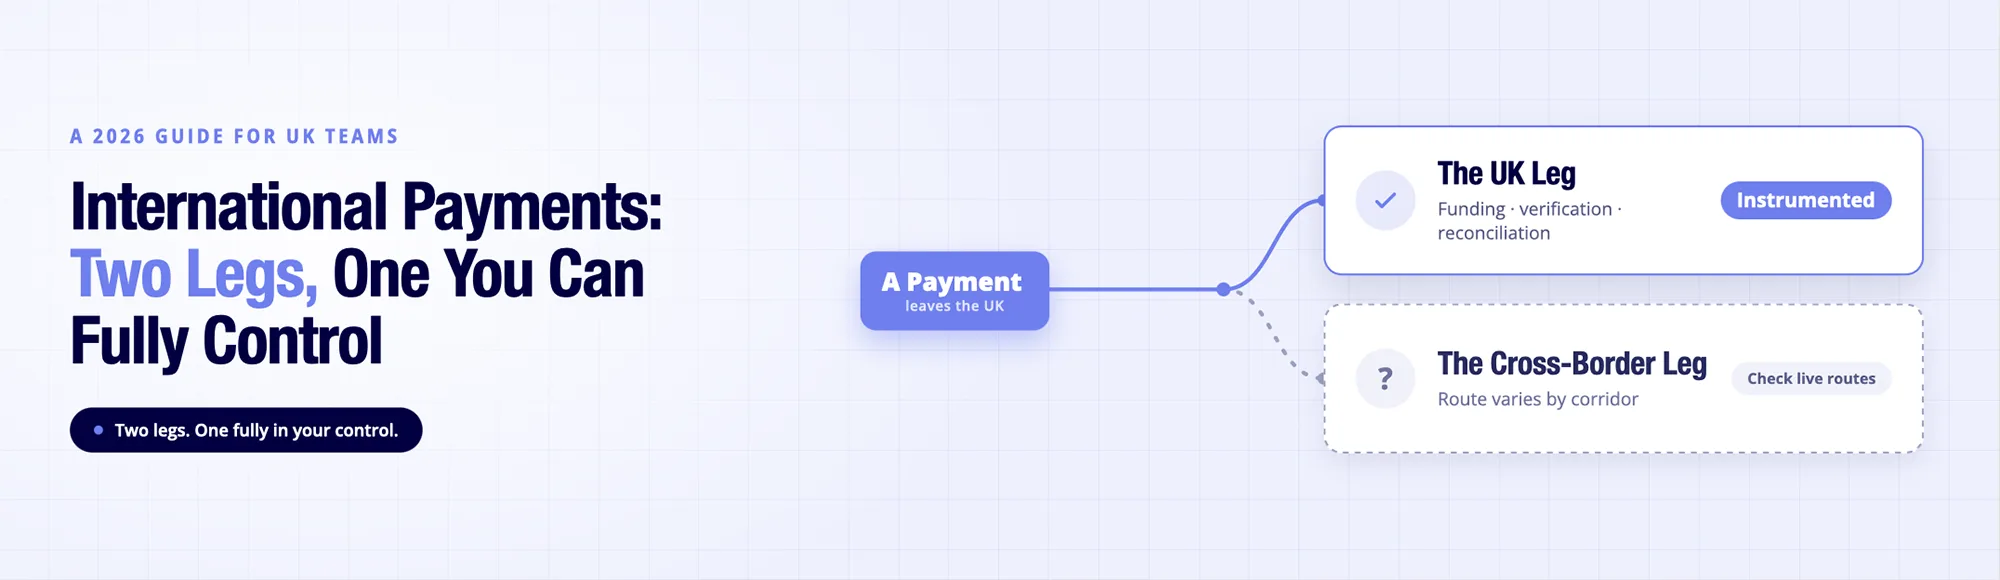
International Payments Still Break at Scale. Here Is Why.
International payments from the UK are two journeys joined together: a fast domestic leg and a slower cross-border leg where fees and visibility hide. This guide explains how each leg works, the four real costs, what Open Banking can and cannot change, and how to compare international payout services properly.
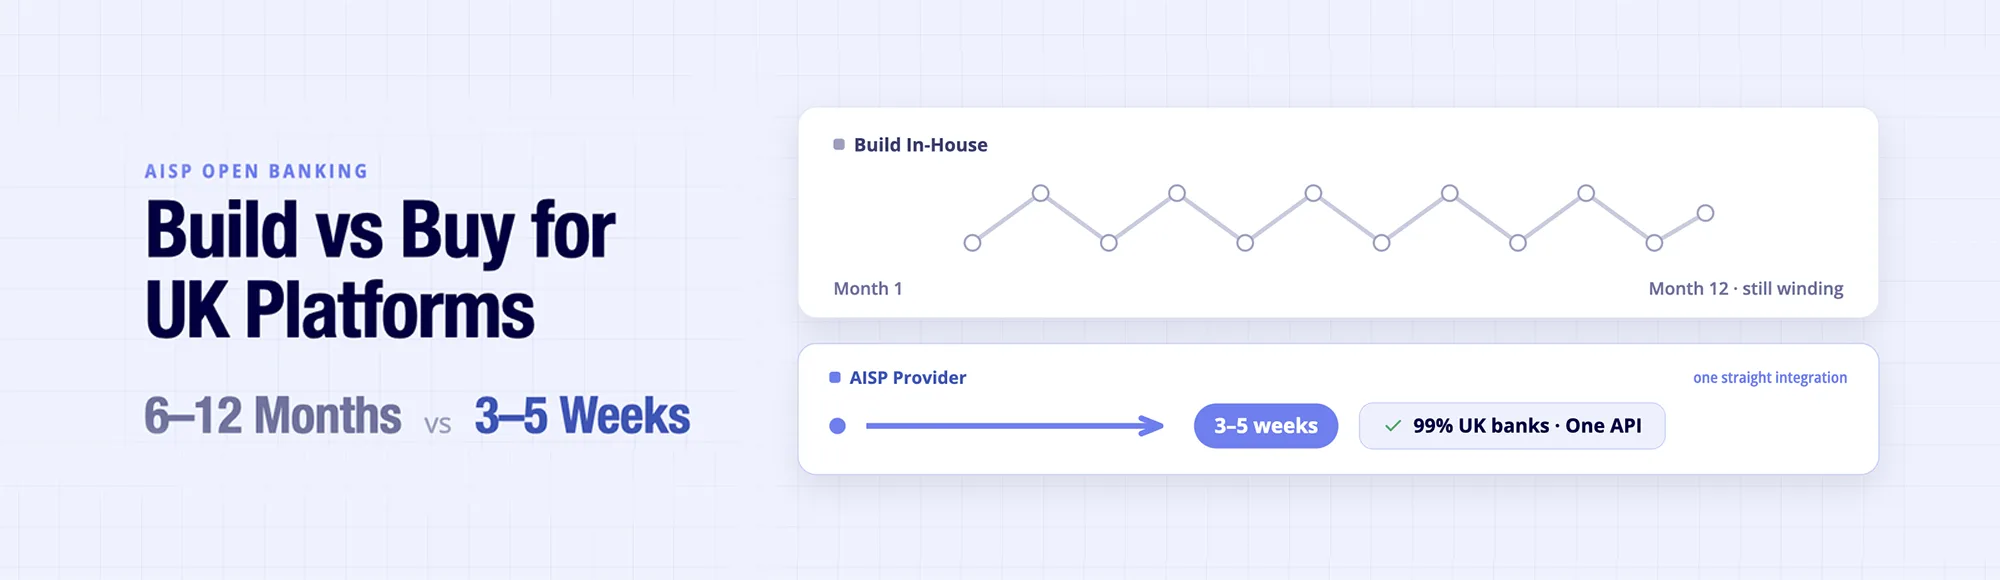
AISP Open Banking: Build vs Buy for UK Platforms
Deciding whether to build direct bank connections or use an AISP Open Banking provider comes down to engineering time and ongoing maintenance cost. This guide compares in-house integration against open banking AISP infrastructure on timeline, FCA authorisation, consent handling and reliability, so UK platform teams can evaluate the real cost of each path.
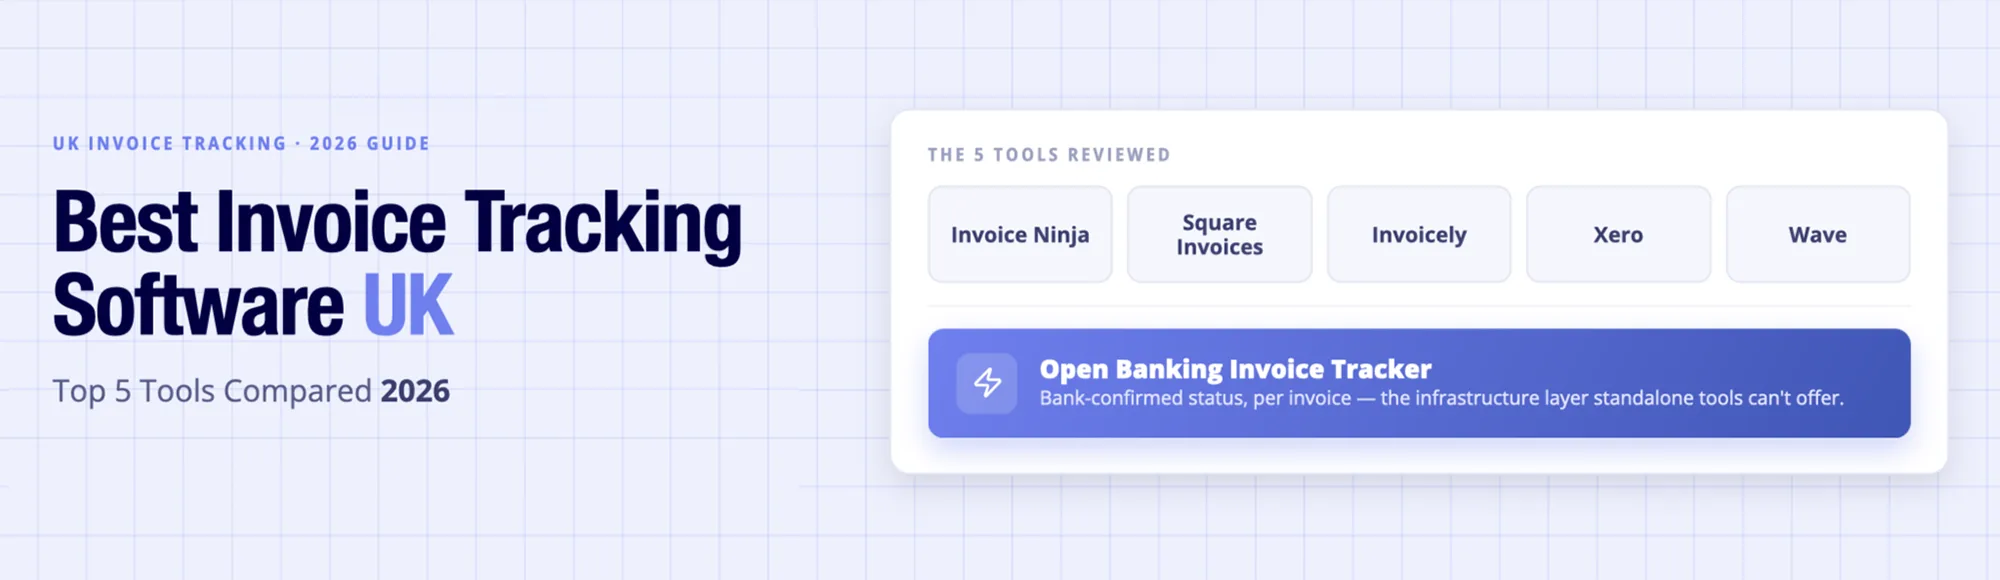
Best Invoice Tracking Software in the UK: Top 5 Tools Compared 2026
Choosing the best invoice tracking software means comparing more than invoice creation. This guide reviews Invoice Ninja, Xero, Square Invoices, Invoicely and Wave on payment tracking, bank integration and reconciliation, then explains how Open Banking infrastructure enables real-time, bank-confirmed invoice status for UK finance platforms beyond traditional CSV-based workflows.
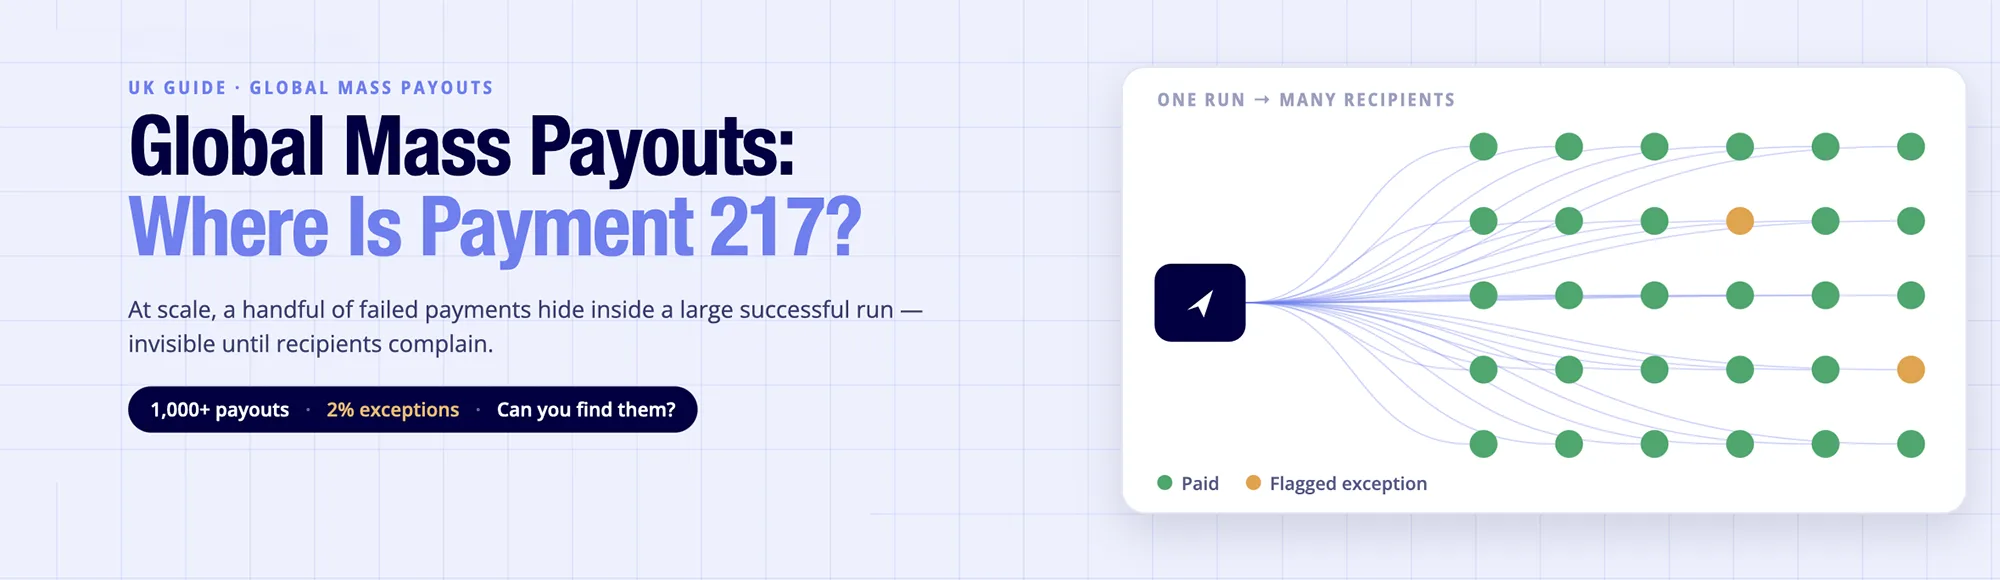
Global Mass Payouts: Why They Break at Scale? (UK Guide)
Global mass payouts break at scale for predictable reasons: batch blindness, partial failures, and reconciliation lag. This UK guide explains the three failure modes, the two-layer architecture that fixes them, and how one ERP platform cut its payout time by 15 days after moving to per-payout webhooks.
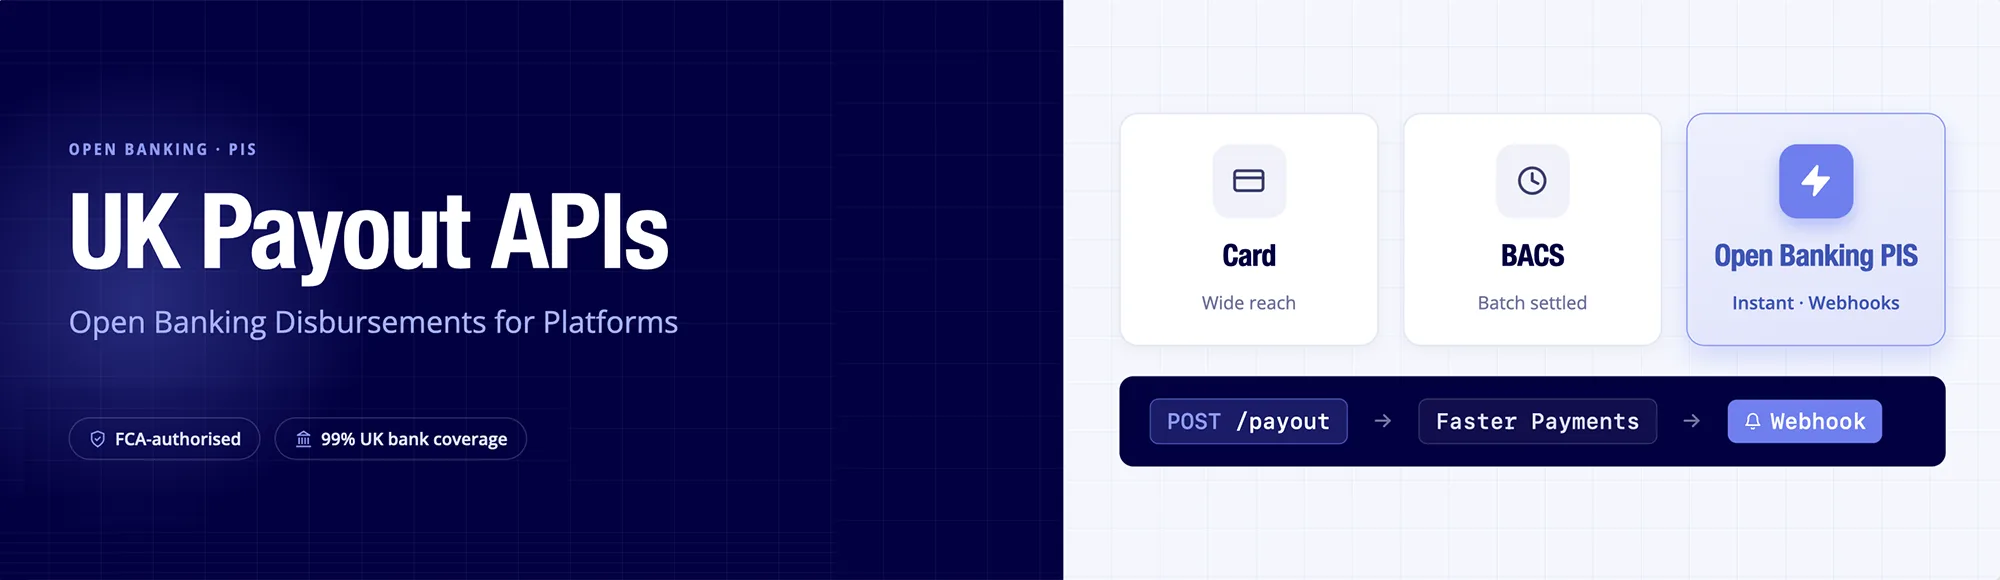
UK Payout APIs: Open Banking Disbursements for Platforms
Open Banking PIS lets UK platforms program Faster Payments for outbound disbursements and receive per-payout webhook status, reducing manual CSV uploads and reconciliation delays. This guide explains how payout APIs work, compares card/BACS/Open Banking options, and gives engineers a checklist for choosing a provider: coverage, webhooks, idempotency, sandbox fidelity, compliance, onboarding and pricing.
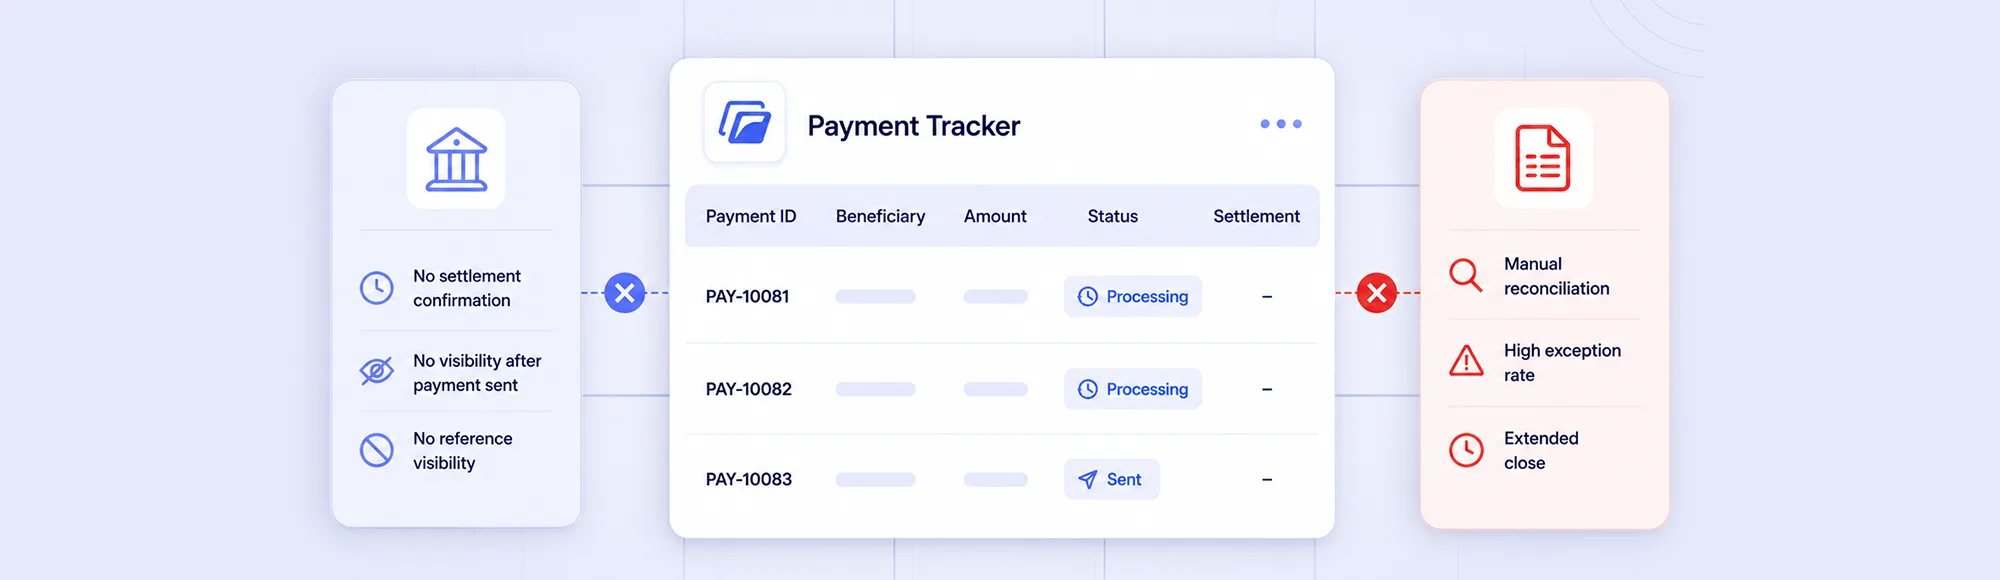
Why Your Payment Tracker Is Not Telling You Enough
Most payment tracker tools answer one question: did the payment go out? UK finance teams need three more answers. Did it arrive? Did the reference survive? Did it close the reconciliation? Industry research from March 2026 found 85% of UK firms still use manual reconciliation. This blog covers why payment tracking breaks and what fixes…
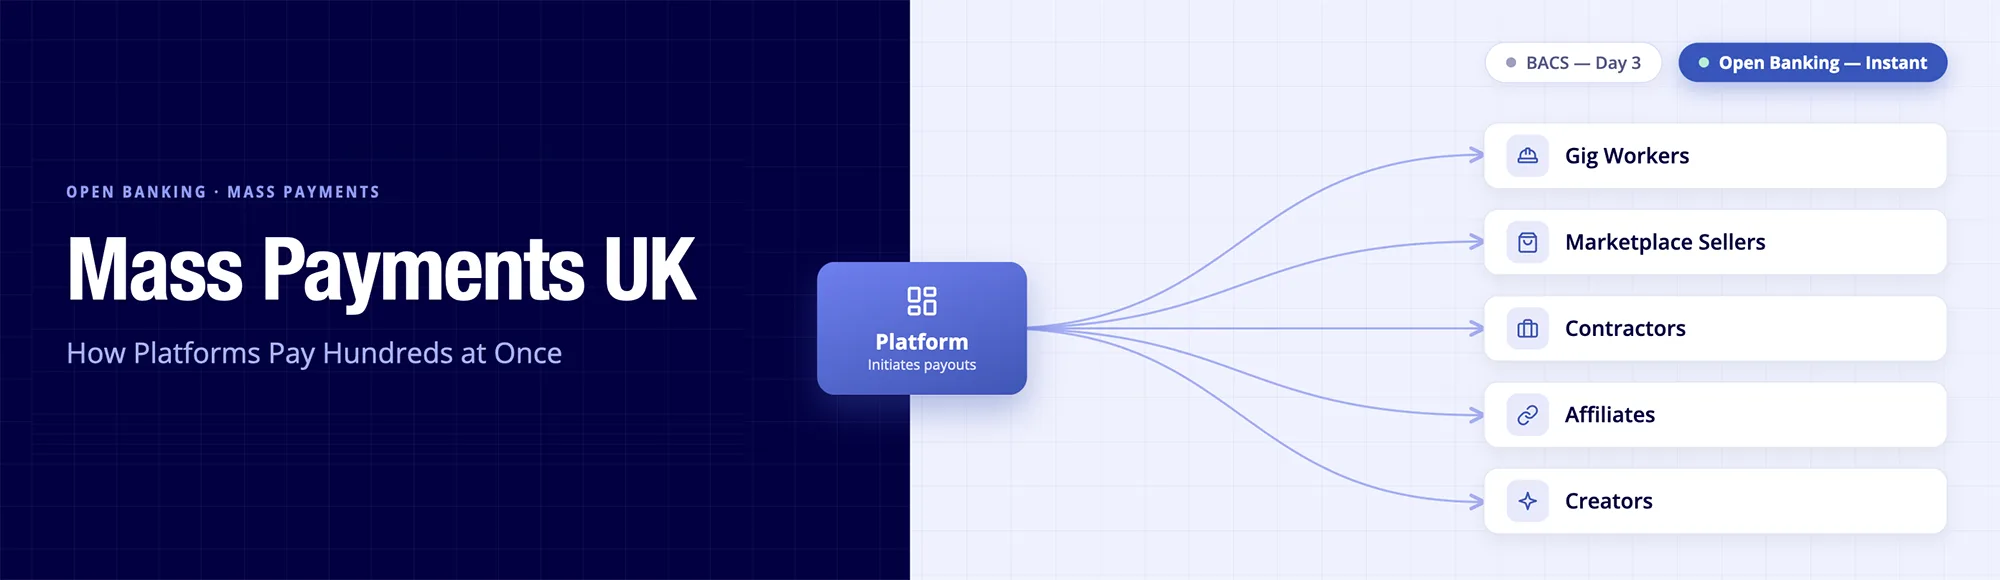
Mass Payments UK: How Platforms Pay Hundreds at Once
Traditional payment methods like BACS can slow down mass payouts with delayed settlement, limited visibility, and late error detection. Discover how Open Banking APIs enable faster, more transparent mass payments with real-time payment status, automated reconciliation, and a better experience for UK platforms paying hundreds or thousands of recipients.
Moneyhub Alternatives: 6 UK Open Banking Providers Compared
Compare the best Moneyhub alternatives for UK Open Banking. This guide breaks down TrueLayer, Yapily, Bud Financial, Tink, Plaid, and Finexer across bank coverage, AIS/PIS capabilities, pricing models, and deployment speed. Ideal for fintech, SaaS, and platform teams evaluating providers for payments, data access, and affordability use cases in the UK market.
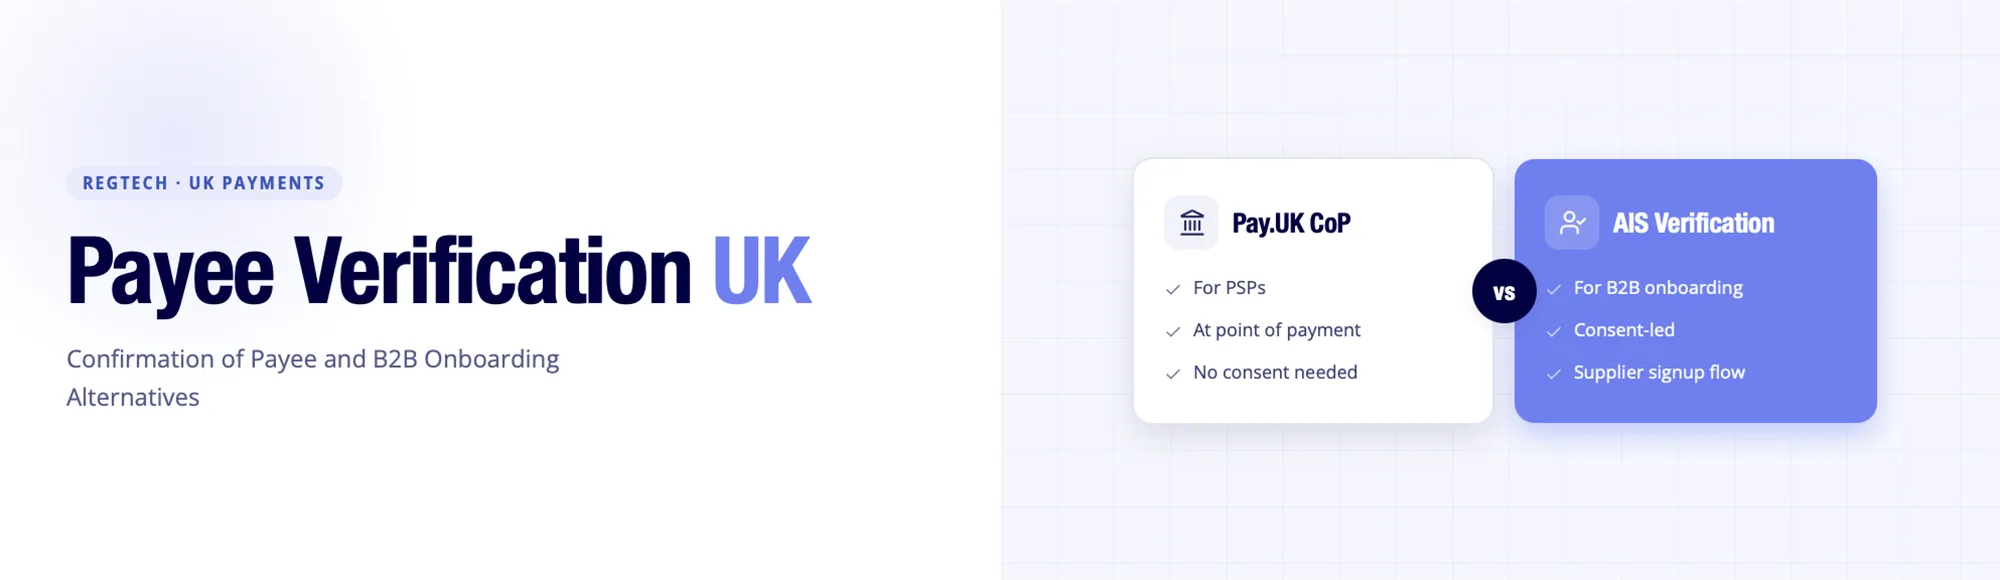
Payee Verification UK: CoP Explained and B2B Alternatives
Payee verification in the UK covers two distinct mechanisms: the regulated Pay.UK Confirmation of Payee scheme for PSPs checking accounts before payment, and AIS-based bank account verification for B2B platforms onboarding suppliers. This guide explains how Confirmation of Payee works, who must comply, who provides it, and where Open Banking verification fits B2B onboarding workflows.
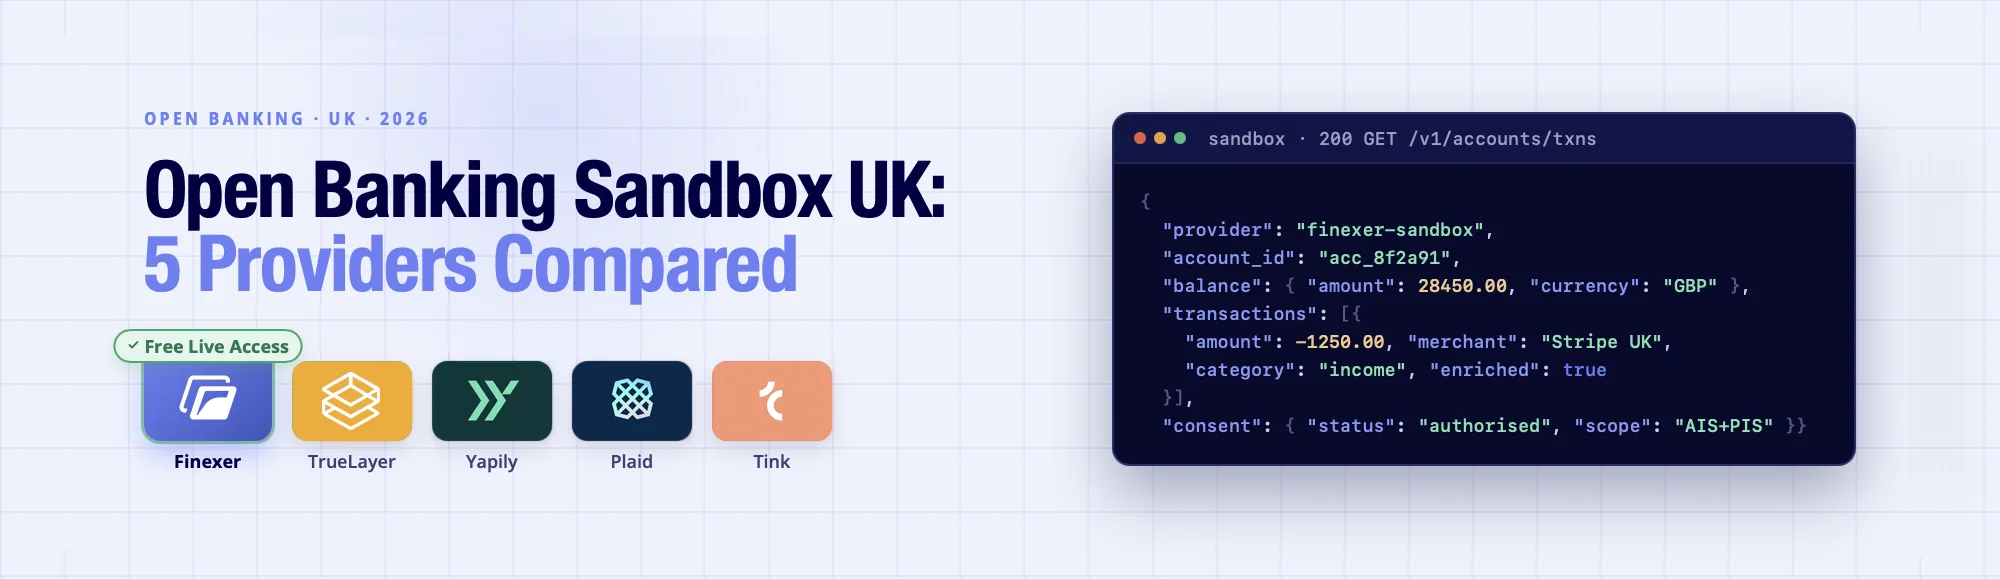
Open Banking Sandbox UK: Finexer vs TrueLayer vs Yapily vs Plaid vs Tink Compared
Most open banking sandboxes look identical until you try to go live. Some providers offer free signup and instant access. Others route every enquiry through a sales call before testing a single endpoint. This comparison covers five UK open banking sandbox environments on free access, AIS and PIS coverage, bank simulations, and time to live.
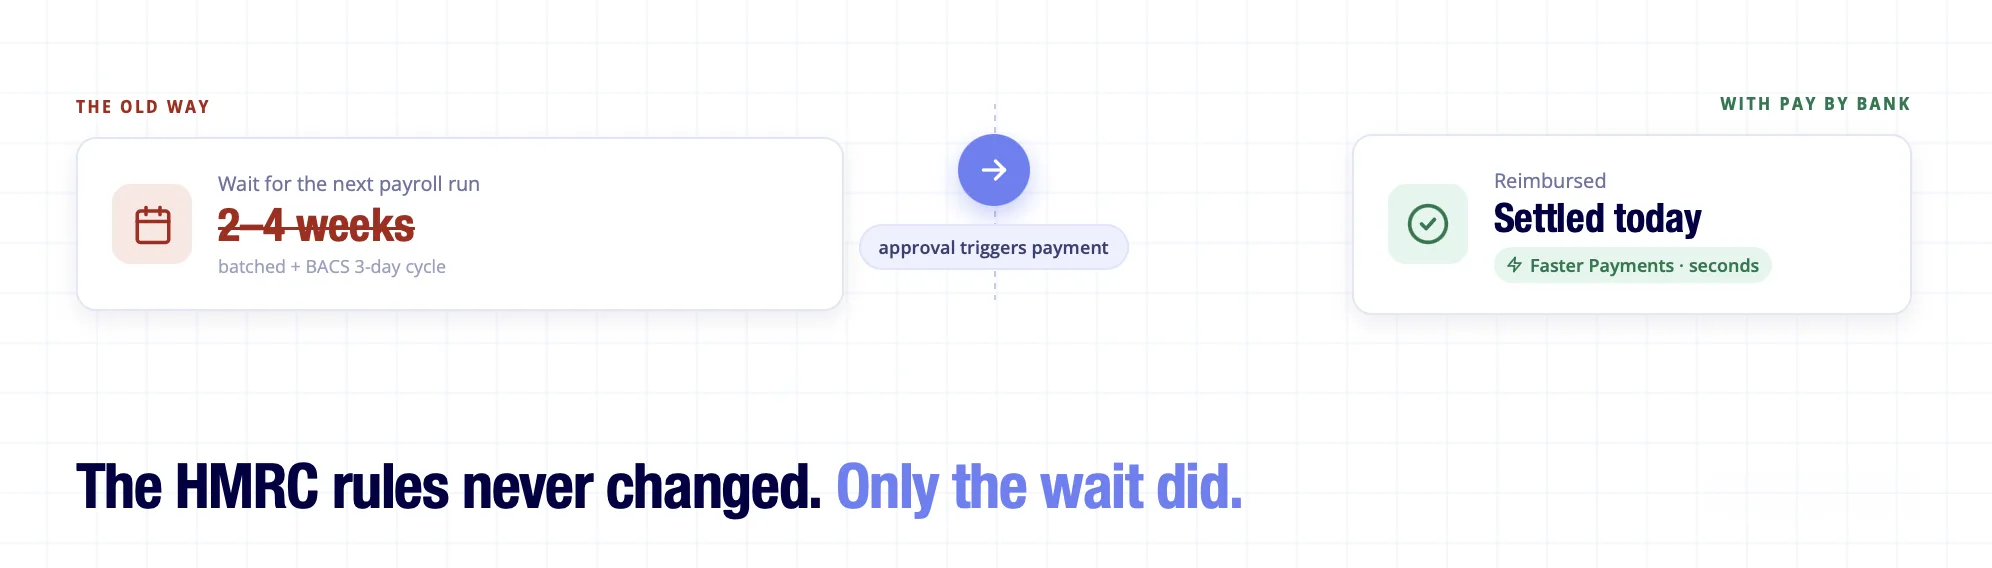
Employee Expense Reimbursement: UK Rules and Process
Employee expense reimbursement in the UK is governed by HMRC ITEPA s336 – tax-free only when an expense is wholly, exclusively, and necessarily incurred for work. The rules are clear. The wait is not: most reimbursements sit two to four weeks for the next payroll run. This guide covers both the rules and the fix.
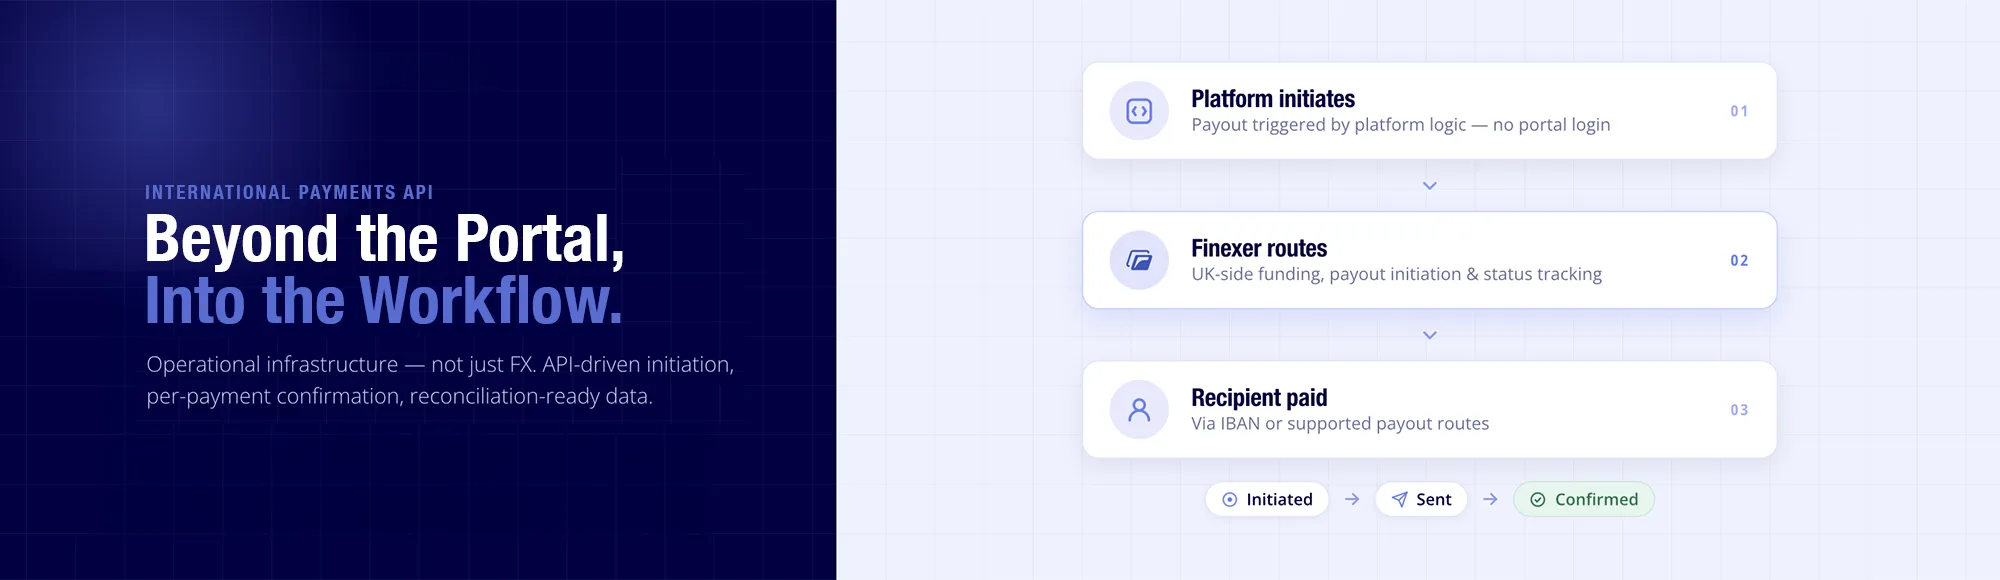
International Payments APIs Are Not Just for FX. They Are Becoming Operational Infrastructure.
Most businesses still treat international payments as a manual problem – bank portals, SWIFT references, chasing confirmations. An international payments API changes that. This blog covers why cross-border payment workflows break at the operational layer, what a cross border payments API actually needs to deliver, and how infrastructure-first businesses are replacing the manual steps entirely.
Bud Financial Alternatives: Top 6 UK Open Banking Providers
Looking for Bud Financial alternatives for your UK Open Banking platform? This comparison covers six providers, Finexer, TrueLayer, Tink, Plaid, Yapily and Moneyhub, on UK bank coverage, AIS, transaction data enrichment and white-label capability. Lending platforms are directed to lending-focused alternatives. Non-lending platforms find the UK data and payments stack that fits their use case.
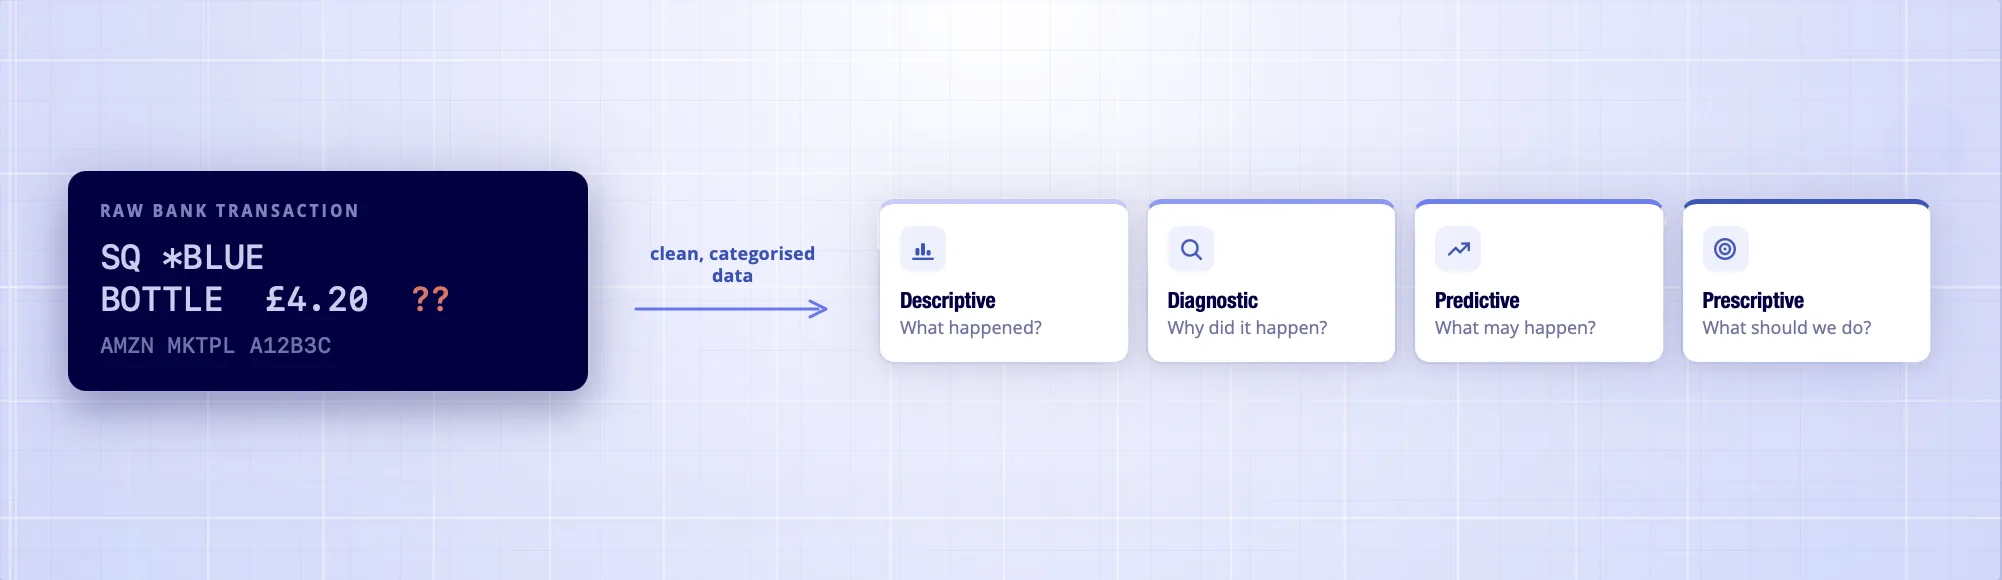
Financial Data Analysis: The 4 Types and How to Apply Them
Financial data analysis examines transactions, revenue, and cash flow to support business decisions. It falls into four types under the Gartner framework: descriptive, diagnostic, predictive, and prescriptive. Each answers a different question, and each depends on clean, categorised data underneath. This guide explains all four with practical UK examples and where data quality fits in.
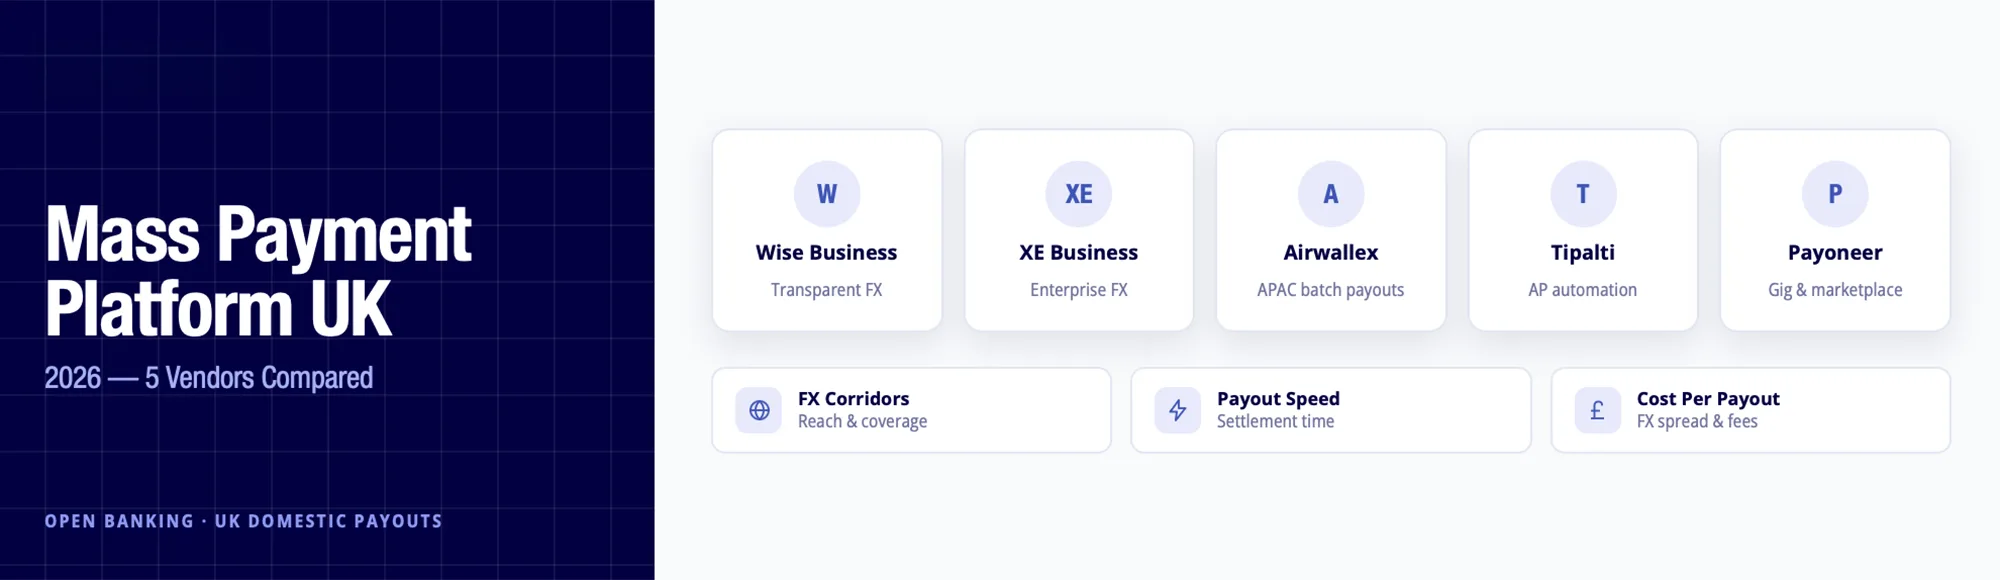
Mass Payment Platform UK 2026: Top 5 Vendors Compared
A mass payment platform sends hundreds or thousands of bulk payments to contractors, marketplace sellers and suppliers across multiple corridors in a single batch. This comparison reviews five platforms, Wise Business, XE, Airwallex, Tipalti and Payoneer, on corridor coverage, FX cost and payout speed, with a guide for UK marketplaces, gig platforms and payroll teams.
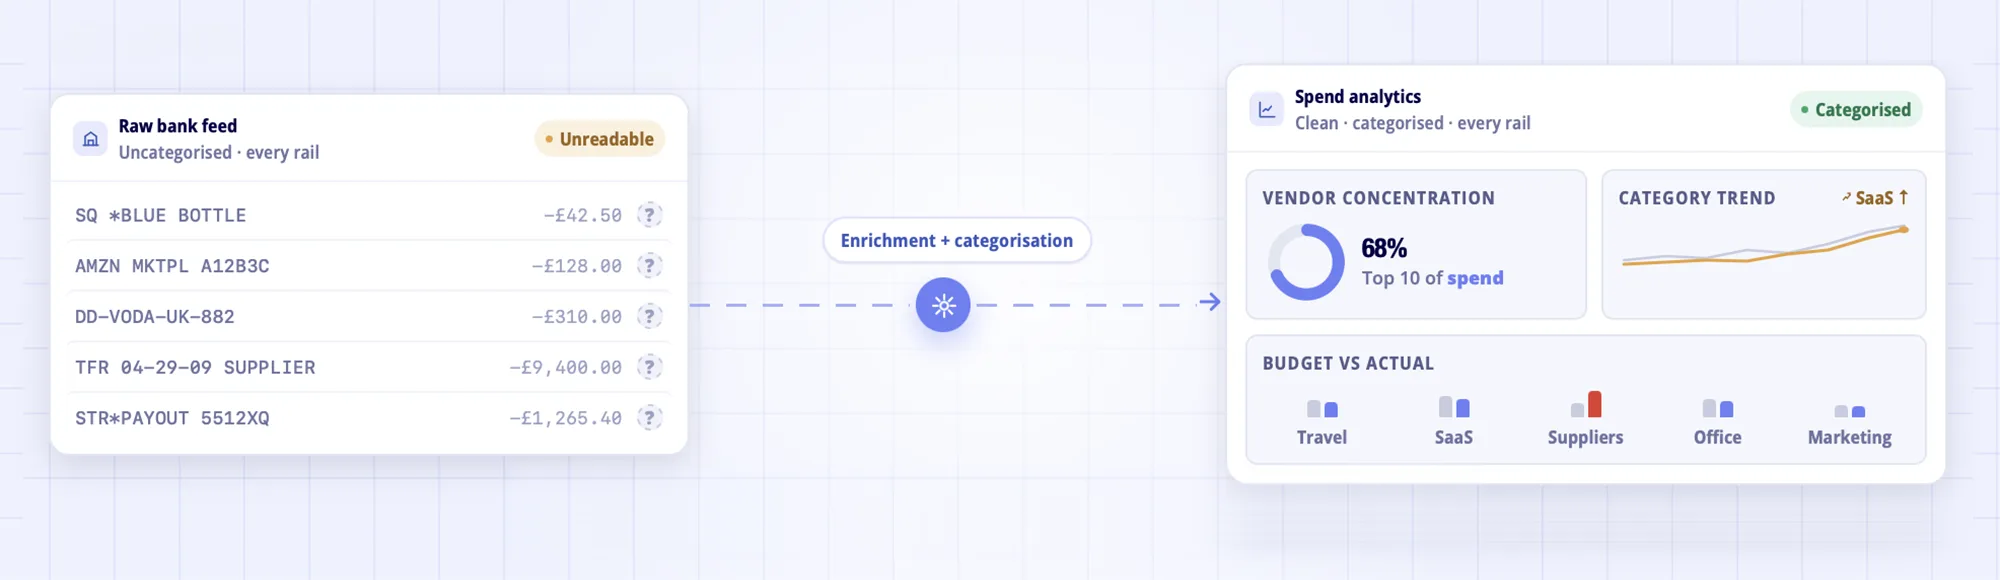
Spend Analytics UK: How Clean Bank Data Powers Finance Visibility
Spend analytics is the layer that turns raw transaction data into vendor, category, and budget insight. Most finance teams already capture their spend. What they lack is clean, categorised data across every payment rail. This blog explains what spend analytics is, why card-only tools fall short, and what a clean bank-data feed actually makes possible.
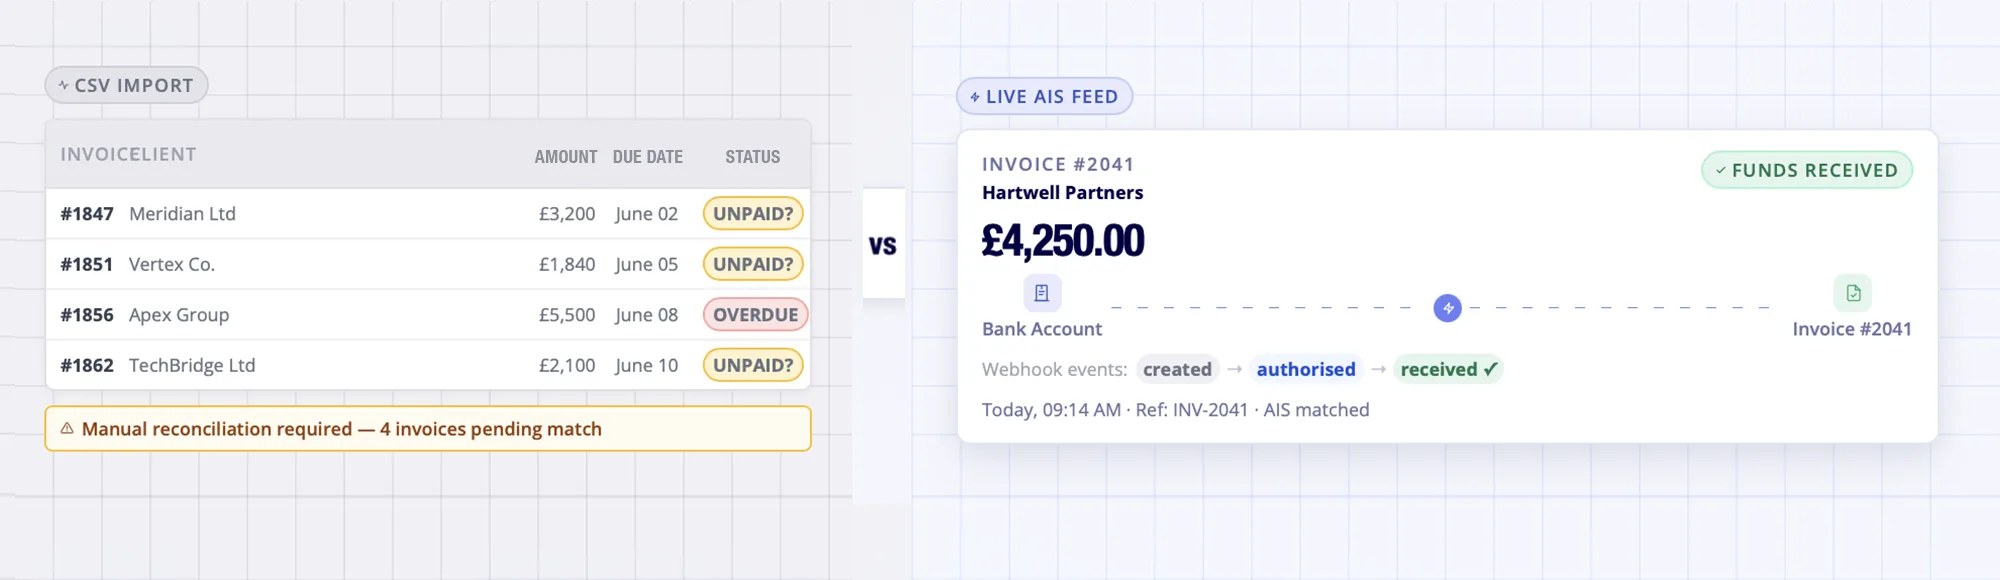
Invoice Tracker UK: Open Banking Invoice Reconciliation
Finexer’s invoice tracker UK connects invoice records with live Open Banking bank data, Pay by Bank initiation and per-event webhooks from request to bank-matched confirmation. Platforms building invoice tracking as a product feature use the Finexer Invoice Reconciliation Tracker as the regulated bank data and payment layer. The platform owns the workflow. Finexer provides connectivity.