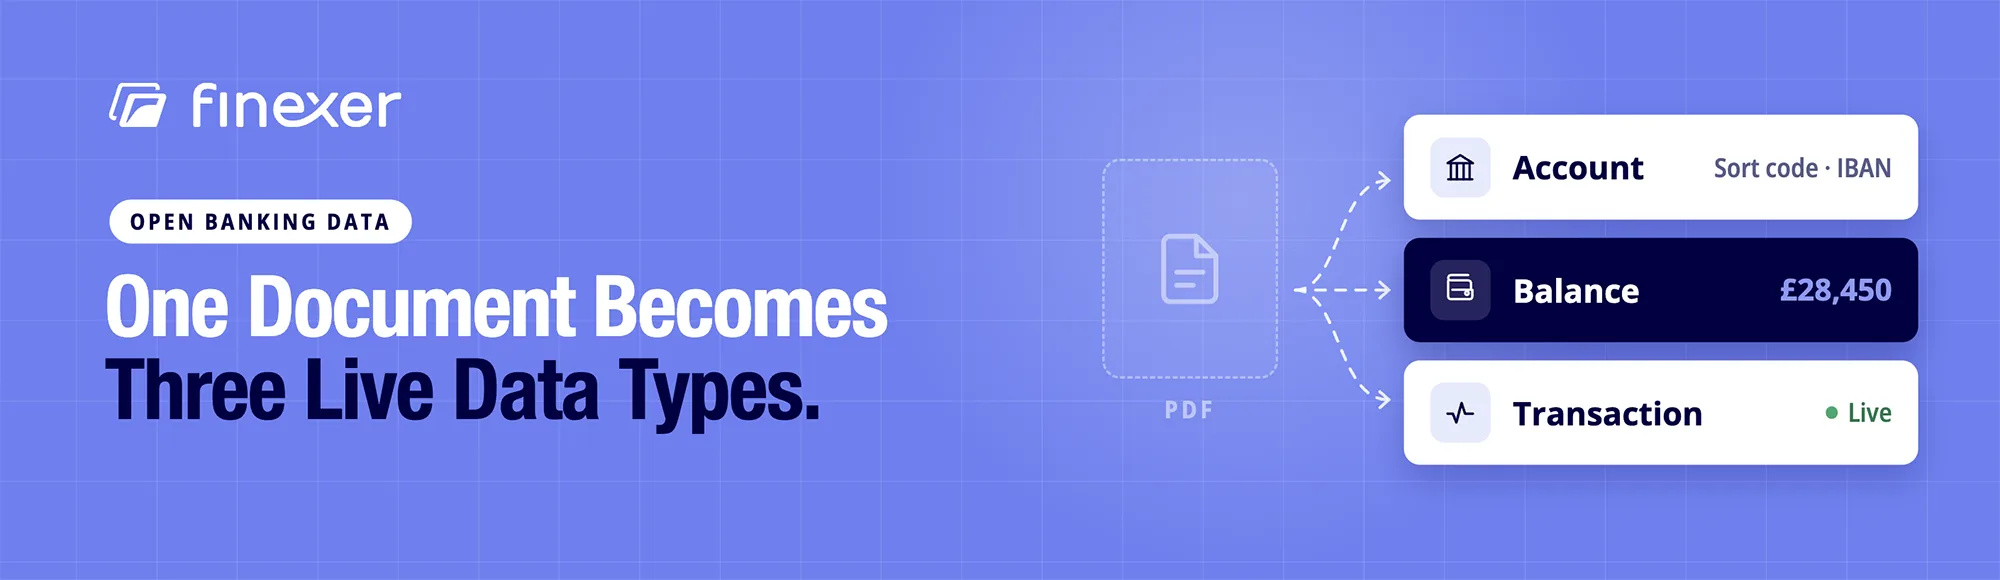
Yes. With the customer’s consent, account, balance and transaction data comes directly from the bank through an API. There is no document to find, download or upload and nothing sitting in the Downloads folder waiting to go stale.
That single change removes a whole category of friction from onboarding and reconciliation. Here is what replaces the PDF and where a document still has a job to do.
What Arrives Instead of a Document?
Three data types arrive instead of a file: account data, balance data and transaction data.
Finexer’s bank data API delivers exactly this three-way breakdown once a customer connects their bank account.
| Data Type | What It Includes |
|---|---|
| Account data | Account name, number, sort code, IBAN, currency |
| Balance data | Current balance, currency, credit line |
| Transaction data | Date, reference, amount, status, transaction code |
Each type updates as new activity happens at the bank. A PDF statement is a snapshot of one moment, already out of date the day it is generated.
Why Do PDF Statement Uploads Cause Problems?
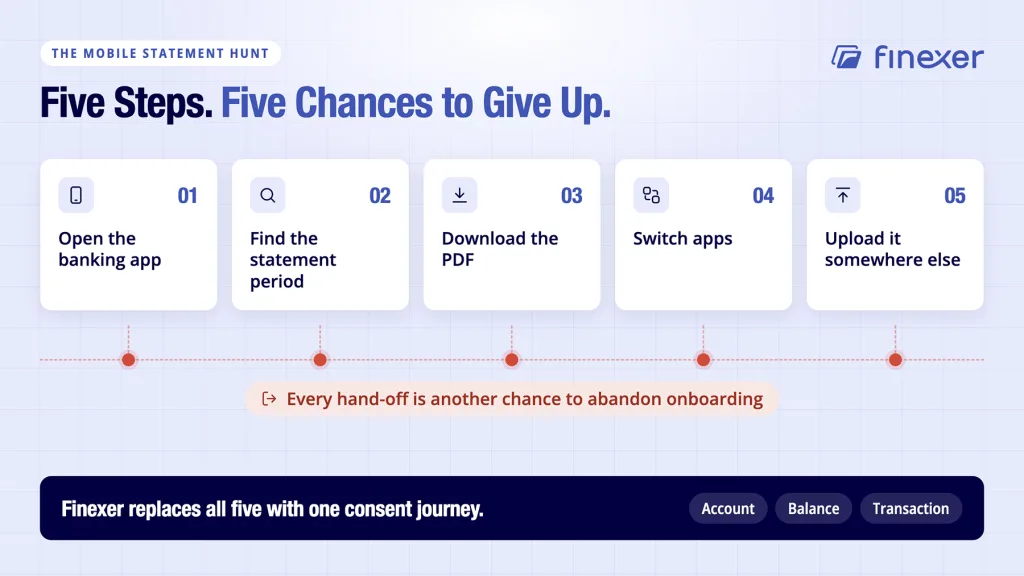
PDF uploads cause high abandonment, especially on mobile, where downloading a statement and re-uploading it is a multi-app, multi-step process.
Client feedback on this is consistent. Users open a banking app, search for the right statement period, download a PDF, switch apps and then upload it somewhere else entirely.
Every extra step is a chance to give up. Some platforms try to fix this after the fact with bank statement extraction software that reads the uploaded PDF and pulls out the numbers.
That approach still starts with a document hunt. A process built around bank transaction data pulled directly from the bank removes the document step entirely, rather than automating what happens after that.
What Does the Customer Actually Experience?
The customer goes through a one-off consent journey rather than a document hunt.
They see a request to connect their bank account, log in directly with their own bank and approve access. From that point, data arrives automatically. There is no repeat statement chase each time a platform needs updated figures as the connection stays live until the customer withdraws consent or it lapses.
This matters most at onboarding, the moment a business is most likely to lose a new customer to friction. Removing a document upload step tends to remove not only a mild inconvenience but also a genuine drop-off point.
How Do UK Providers Compare on This?
Not every UK Open Banking provider approaches statement data the same way. Some focus on data, some others on payments and others still (a smaller number though) on both.
| Provider Type | Examples | Focus |
|---|---|---|
| Data-only (AISP) | Moneyhub Enterprise | Financial data products, limited payments focus |
| Payments-led (PISP) | GoCardless, Volt.io | Payment initiation, less emphasis on account data |
| Combined AIS and PIS | TrueLayer, Yapily, Tink, Salt Edge, Finexer | Both data access and payment initiation from one integration |
The practical difference for a platform evaluating options is whether banking data and payments come from a single API or two separate ones. That matters more once a product needs both.
Where Are PDF Documents Still Needed?
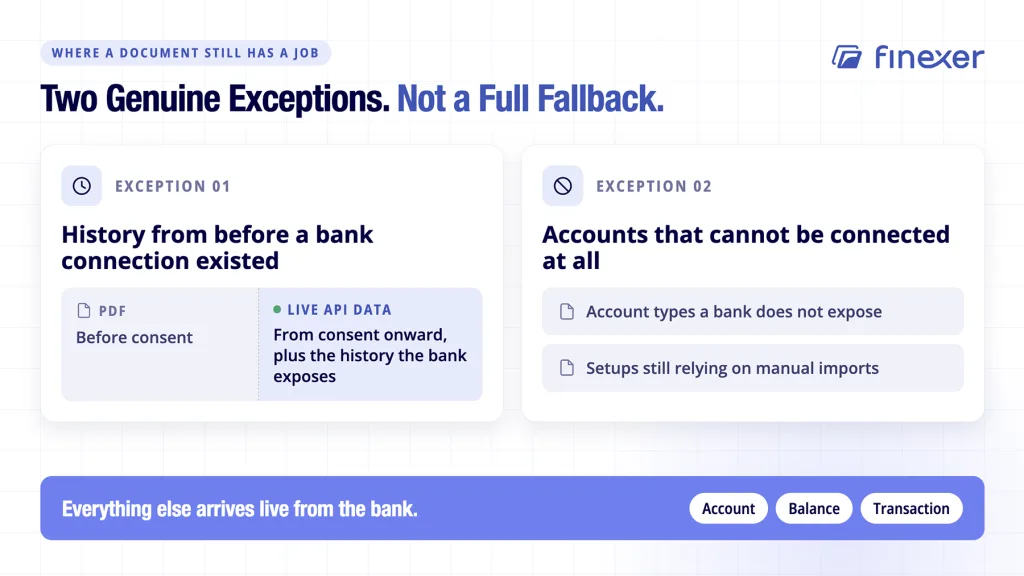
PDFs are still needed for two situations: history from before a bank connection existed and accounts that cannot be connected at all.
Open Banking data only exists from the point a customer connects their account onward, plus whatever history the bank chooses to expose. For older records or account types a bank does not support through its Open Banking interface, a document remains the only option.
This is a common gap platforms run into when planning a build, alongside accounts like cloud accounting software setups that still rely on manual imports for edge cases.
What’s the difference between digital banking statement data and a PDF statement?
Digital data arrives structured and current through an API. A PDF is a static document representing one moment, formatted for reading rather than processing.
Is digital banking statement data secure?
Access requires explicit customer consent, and the customer authenticates directly with their own bank. The platform never sees banking login credentials.
Does every UK bank support this?
Coverage spans almost all major UK banks across high street, challenger and business accounts, though account types and history depth vary by bank.
How far back does transaction history go?
Depth depends on what the connected bank exposes through its Open Banking interface, so it varies by bank rather than being fixed at one figure.
See Digital Statement Data in Action
Manual statement uploads slow down onboarding and cause drop-off on mobile.
Finexer’s Data product replaces that document hunt with account, balance and transaction data delivered directly from the bank.
Explore with AI
About the Author
Yuri
Yuriy Yakushko is a fintech founder and software engineer with over 20 years of experience building financial technology. He’s passionate about creating scalable, secure infrastructure that helps businesses modernise how they access financial data and manage payments.