Read the Record, Not the Upload.
Instant banking data, zero documents to chase.
For any repeated workflow, the API route wins on both accuracy and completion rate. PDF parsing works on a document that the customer has to find, download and upload and which can be edited before it reaches you.
That is the decision in one sentence. Framed as open banking vs bank statement parsing, the choice comes down to whether a workflow happens once or repeats, and the table below breaks that down across the factors that actually change a build.
How Do the Two Methods Compare?
| Factor | PDF Parsing | Open Banking API |
|---|---|---|
| Data accuracy | Depends on layout and parser quality | Comes directly from the bank’s record |
| Tamper risk | File can be edited before upload | No document exists to alter |
| User effort | Find, download, upload a file | One-off consent, then automatic |
| Completion rate | Drops sharply on mobile | Higher, fewer steps to abandon |
| Refresh capability | Static, needs re-upload | Updates as new activity occurs |
| Audit trail | Upload timestamp only | Consented, timestamped API request |
Every row favours the API route for a workflow that repeats. PDF parsing does not lose on any single factor by a small margin; rather, it loses on most of them by a wide one, and the gap widens further as transaction volume grows.
Why Does the Drop-Off Problem Matter Most?
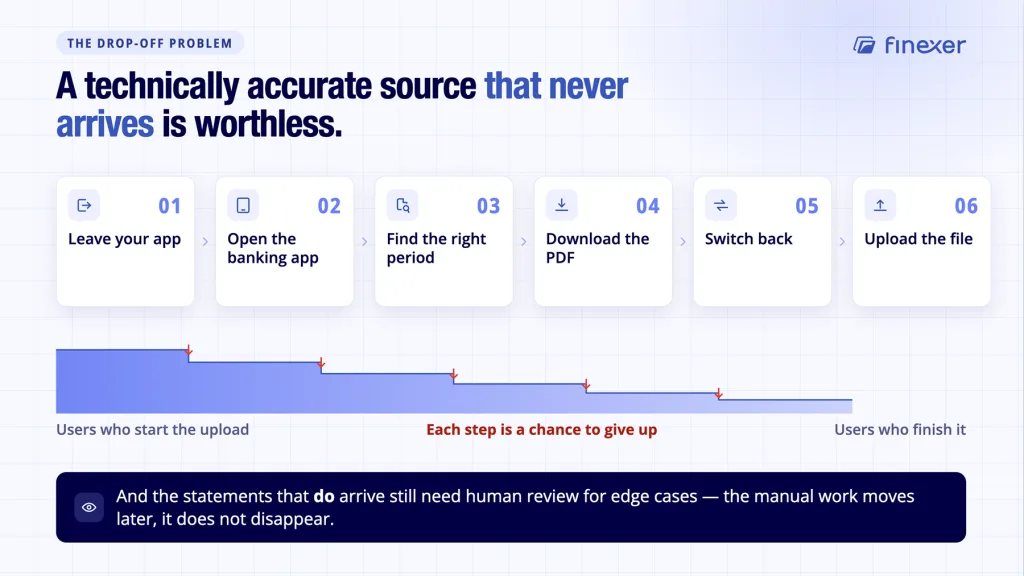
The drop-off problem is the one factor that actually decides most builds because a data source that is technically accurate but never reaches you is worthless in practice.
Mobile uploading is where this surfaces hardest. A user has to leave your app, open a banking app, find the right statement period, download a PDF, switch back and then upload it, often on a small screen with a patchy connection. Each step is a chance to give up, and platforms consistently see completion drop the moment a document upload enters the flow, regardless of how well the rest of the onboarding is designed.
Even statements that do get uploaded are not the end of the work. OCR and parsing tools still need human review for edge cases, such as unusual layouts, multi-page tables and truncated descriptors, all of which produce output someone has to check before it is usable. The document route does not remove manual effort; it just moves it later in the process often out of sight of whoever approved the original build decision.
Where Does PDF Still Have a Place?
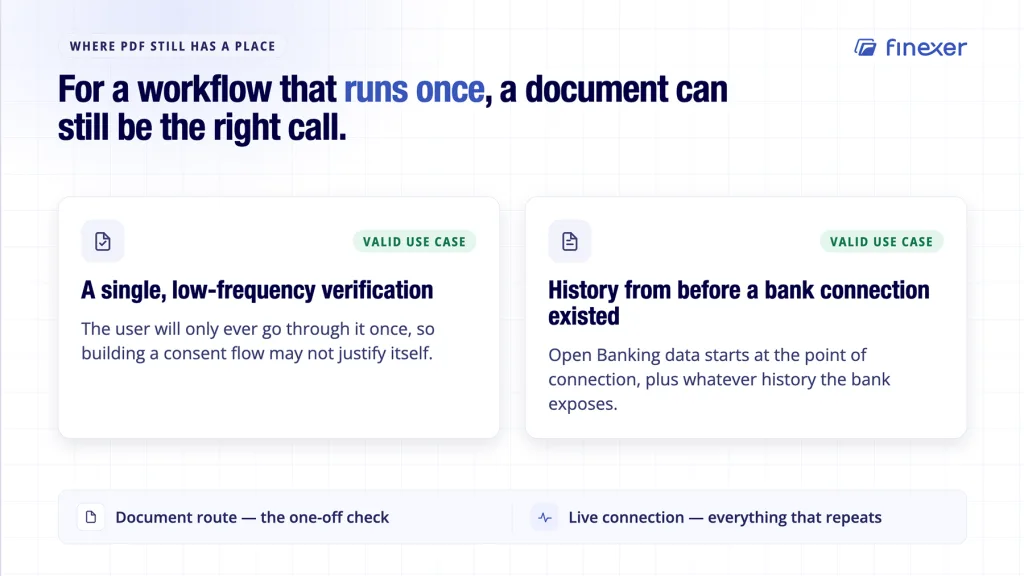
PDF documents still have a place for one-off checks and historical periods that a live connection cannot reach.
A single, low-frequency verification, where a user will only ever go through the process once, may not justify building a consent flow. Similarly, history from before a bank connection existed has no equivalent through an API as Open Banking data only exists from the point of connection onwards, plus whatever history the bank exposes. For those specific cases, a document remains the practical option, and no serious comparison should pretend otherwise.
How Do UK Providers Handle This Differently?
Not every UK Open Banking provider treats this decision the same way, and the difference matters when a platform is choosing between them rather than choosing whether to move away from documents at all.
| Provider type | Examples | Approach |
|---|---|---|
| Data-only (AISP) | Moneyhub Enterprise | Direct API access, with no document parsing involved. |
| Combined AIS and PIS | TrueLayer, Yapily, Finexer, Salt Edge | Data access plus payment initiation from one integration. |
| Document-first tools | OCR and statement extraction vendors | Parse uploaded PDFs, but remain dependent on the document existing. |
Platforms already committed to a document-based workflow, through bank statement automation tooling, are automating the slower half of the problem rather than removing it. The API route and the document route are not two versions of the same solution; they solve the accuracy and effort problem differently.
Where Does Finexer Fit In?
Finexer’s Data product delivers bank transaction data directly from the bank, structured into account, balance and transaction data, with no document stage in the process. Finexer’s bank data API handles the connection and consent flow such that a platform receives structured records rather than a file to parse.
That structure matters for platforms building toward MTD-compliant software or ongoing reconciliation, where a workflow repeats monthly rather than running once. The consent happens a single time, and the connection stays live until the customer withdraws it or it lapses, removing the repeated document chase entirely.
- Account, balance and transaction data direct from the bank
- No document stage where accuracy or tamper risk can enter
- Live connection updates as new activity occurs
- Consented, timestamped audit trail on every request
Is Open Banking data always more accurate than a PDF statement?
It removes the transcription and parsing errors that come from a document although descriptors may still need enrichment to become fully readable.
Does switching to Open Banking mean giving up PDF uploads entirely?
No. Most platforms keep a document upload option for edge cases while using the API route for the repeated, high-volume workflow.
How long does the customer consent journey take compared to a document upload?
It typically takes less time for one-off setup and removes the repeated document hunt entirely for anything that recurs as the connection stays live afterward.
Can Open Banking data be edited before a platform receives it?
No. It comes from a consented, authenticated connection directly with the bank, with no document stage where it could be altered.
See the Comparison in Your Own Workflow
Every upload you ask for is a customer who might not finish, and every PDF you accept is a file someone had the chance to edit.
Finexer’s Data product delivers account, balance and transaction data straight from the bank for repeated workflows to run on the record rather than a document.
Explore with AI
About the Author
Yuri
Yuriy Yakushko is a fintech founder and software engineer with over 20 years of experience building financial technology. He’s passionate about creating scalable, secure infrastructure that helps businesses modernise how they access financial data and manage payments.