SME buyers need different things from enterprise buyers: No long procurement cycle, sandbox access before contract, an agent route so they don’t need their own licence, and support that responds within a working week. A ranking of open banking platforms for SMEs isn’t useful if the top choice requires a three-month sales cycle. The real question is which open banking platforms for SMEs fit how SMEs actually buy and build products: fast, lean, agent-friendly.
What makes an Open Banking platform right for SMEs?
SMEs don’t have a procurement team. Small teams need rapid onboarding, not lengthy vendor evaluations. The best open banking platforms for SMEs share key characteristics: no mandatory long-term contracts, production access within days not weeks, agent licensing to reduce regulatory burden, good documentation for solo developers, and predictable support response times within a week.
| SME Criterion | What to Ask a Vendor | What Matters |
|---|---|---|
| Contract length | “What’s your minimum term?” | SMEs need flexible, short-term contracts rather than restrictive enterprise commitments |
| Sandbox access | “Can I access the sandbox today without signing a contract?” | If they say “after you sign NDA,” they don’t get SMEs |
| Licensing model | “Do I need my own FCA licence, or can I use an agent licence?” | Agent route means Finexer holds regulatory burden; you integrate and get paid |
| Time-to-production | “How long from sandbox approval to live integration?” | Enterprise takes longer; SME-friendly is usually much faster |
| Support tier | “What’s your standard response time, and do SMEs get dedicated support or ticket queue?” | Queue support doesn’t work for SMEs; response time matters more than volume of documentation |
When evaluating open banking platforms for SMEs, these five factors separate providers that work for your size from those that don’t.
Why do enterprise-first providers fit badly for SMEs?
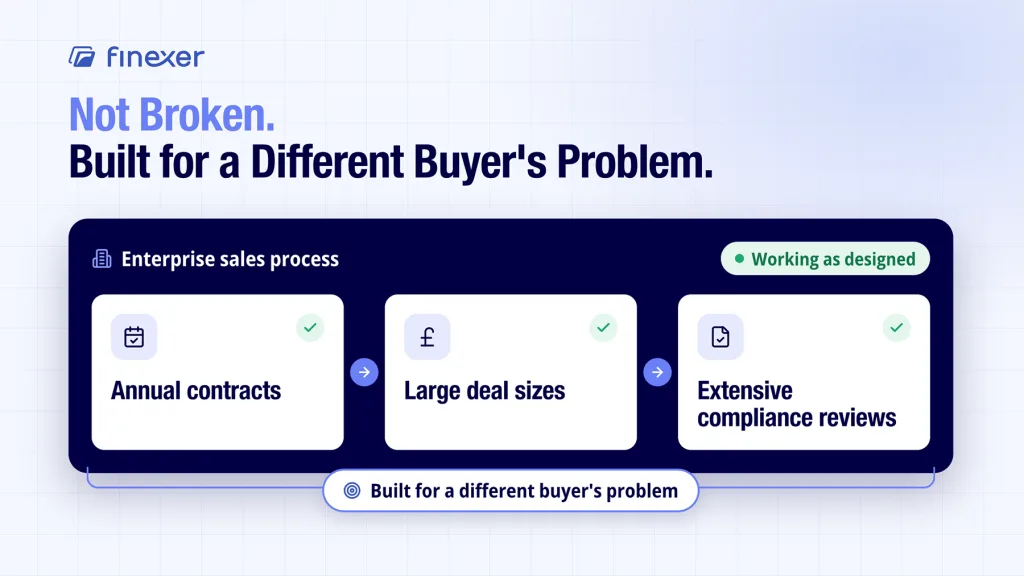
Enterprise-focused platforms create friction at every stage. They optimise for three things: annual contracts, large deal sizes, and extensive compliance reviews. None of these benefit a five-person team. These providers require your own FCA licence, months of procurement, and dedicated engineers assigned to your account.
A small team can’t justify these costs. It’s not that enterprise platforms are “bad.” They’re solving a different buyer’s problem entirely. Your problem is speed and cost. There are audit trails and SLA guarantees. The structural mismatch means even a “great” enterprise provider will feel slow to you.
What should SMEs absolutely not compromise on?
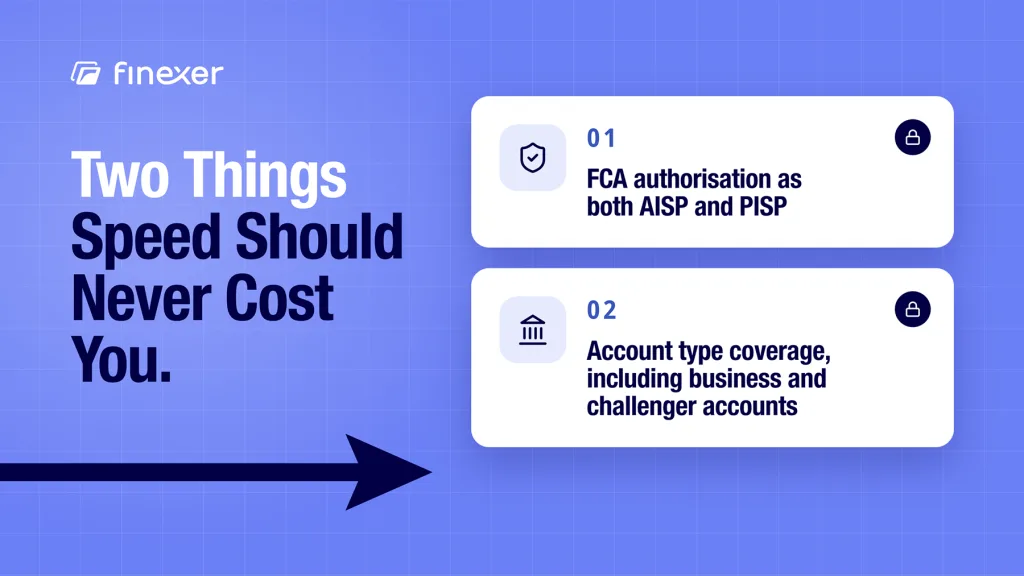
While speed and fast onboarding matter greatly, two critical things are absolutely non-negotiable: FCA authorisation status and account type coverage by the vendor. A provider that isn’t FCA-authorised as an AISP and PISP is a liability, not a time-saver. A provider that skips business current accounts or challenger banks will force you to rebuild when your SME customer base grows and diversifies over time.
Ask vendors directly: “Are you FCA-authorised as both AISP and PISP?” If the answer hedges, move on immediately to the next provider option. Ask: “Which specific account types are covered across all banks?” If they say “mostly personal current accounts only,” you’ve identified a coverage gap that will haunt your product later.
How do you narrow the field?
Start by eliminating non-starters using clear criteria. When comparing open banking solution providers, browse open banking providers uk to see the landscape, but don’t rank them all. Some are enterprise-only. Some offer data-only. Some are third-party resellers. Filter by: FCA status, contract terms, sandbox access, and support response. When reviewing pricing models like Yapily pricing, ask whether they’re sized for you.
What does SME-focused look like?
The right provider offers an agent route, which means they hold the FCA licence and you integrate via their credentials. This eliminates regulatory burden entirely. They provide sandbox access immediately, before any formal contract signature. Production onboarding takes days or weeks maximum, not months of procurement cycles. Support responds within a working week to inquiries. They don’t require you to hire a compliance officer or dedicate engineers to their API.
Finexer is built for this exact buyers. Finexer Connect offers agent-route licensing, hands-on onboarding support, and sandbox access available immediately. One single integration covers data, payments, and verification. You can integrate in days, not months. Your team stays small; Finexer carries the regulatory weight and complexity.
The real question
Before evaluating features or comparing options, ask yourself: “Is this provider selling to SMEs, or to enterprises hoping SMEs will fit?”
If they quote a three-month procurement timeline or require your own FCA licence, they’re enterprise-first. They’ll work eventually, but they’re solving the wrong buyer’s problem.
Learn how Finexer Connect brings solutions to production in just days, then Book a demo to see why more SMEs choose agent-route providers
Explore with AI
About the Author
Ravi Ranjan
Ravi Ranjan is Co founder & CEO of Finexer