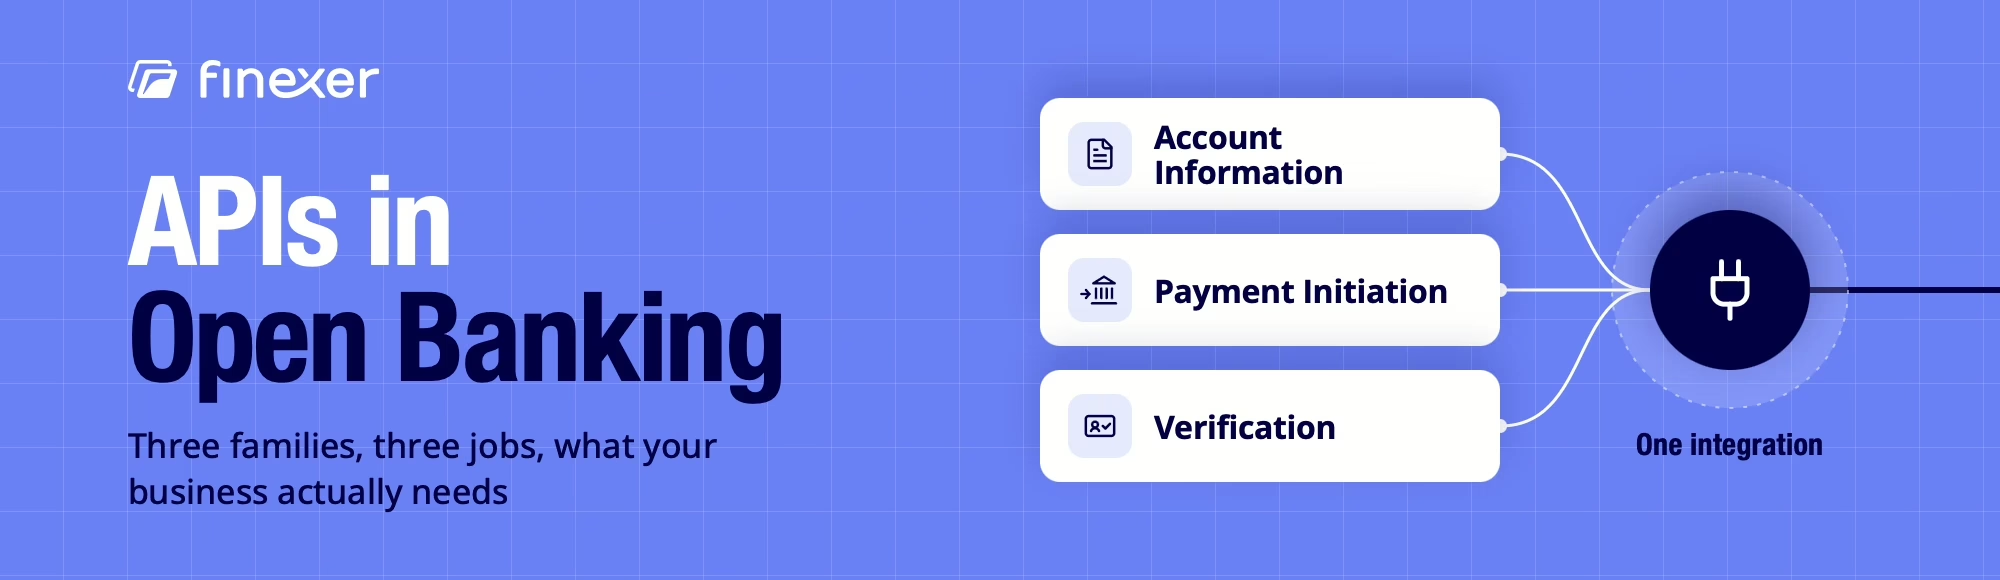
Can your finance team see a customer’s real bank balance before approving credit, without asking them to upload a statement? That’s the kind of question APIs open banking answers. In plain business terms, these are the interfaces that let a platform read consented banking data and initiate payments directly from a bank account, without touching card rails or storing credentials.
If you’re trying to work out whether your platform actually needs these APIs, this guide covers the three families in plain terms, who in the business uses each one, and what changes operationally once they’re in place. If you’re exploring how Open Banking could support your business, this guide will help you understand which API capabilities align with your operational needs
What Is an API in Open Banking?
An API in Open Banking is a secure, regulated connection between your platform and a customer’s bank, used only with the customer’s explicit consent. It replaces manual uploads, screen-scraping and card-network dependency with a direct, authorised line to the bank itself.
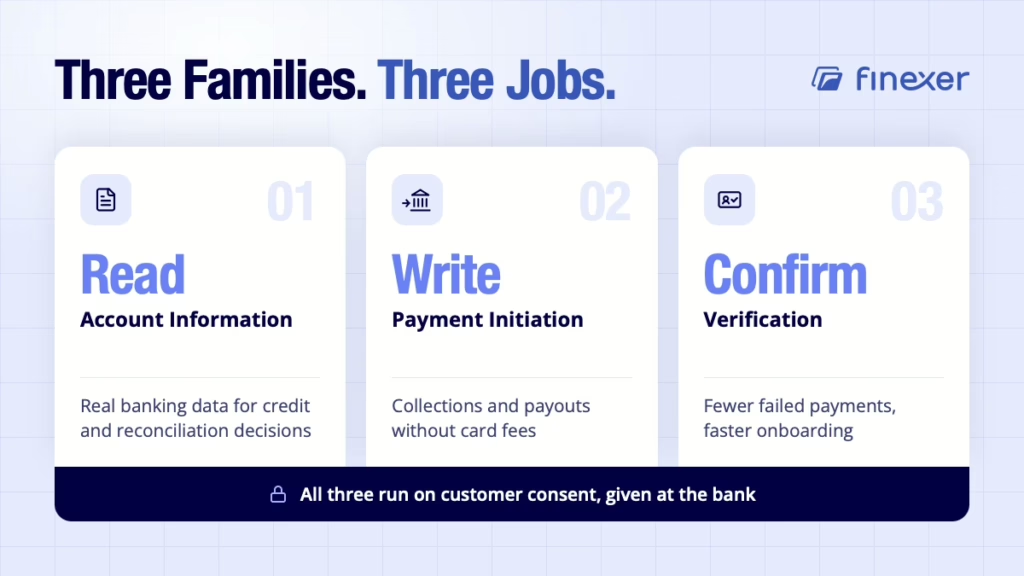
There are three distinct families, and most confusion about APIs open banking comes from treating them as one thing rather than three.
The table below covers the business outcome only; if you want actual request and response bodies, that level of open banking api examples detail lives on a separate page, linked below rather than repeated here.
| API Family | What It Does | Business Outcome |
|---|---|---|
| Account Information | Reads consented transaction and balance data | Real banking data for credit, onboarding and reconciliation decisions |
| Payment Initiation | Sends a payment directly from a bank account | Collection or payout without card fees or manual transfers |
| Verification | Confirms account and identity details against the bank | Fewer failed payments and faster onboarding checks |
Account information services and payment initiation services are the two most commonly confused of the three families that make up APIs open banking; verification is often overlooked entirely, despite doing most of the work in reducing onboarding friction. All three depend on the same principle: nothing moves or gets read without customer consent granted at the bank itself.
Who Actually Needs Each One?
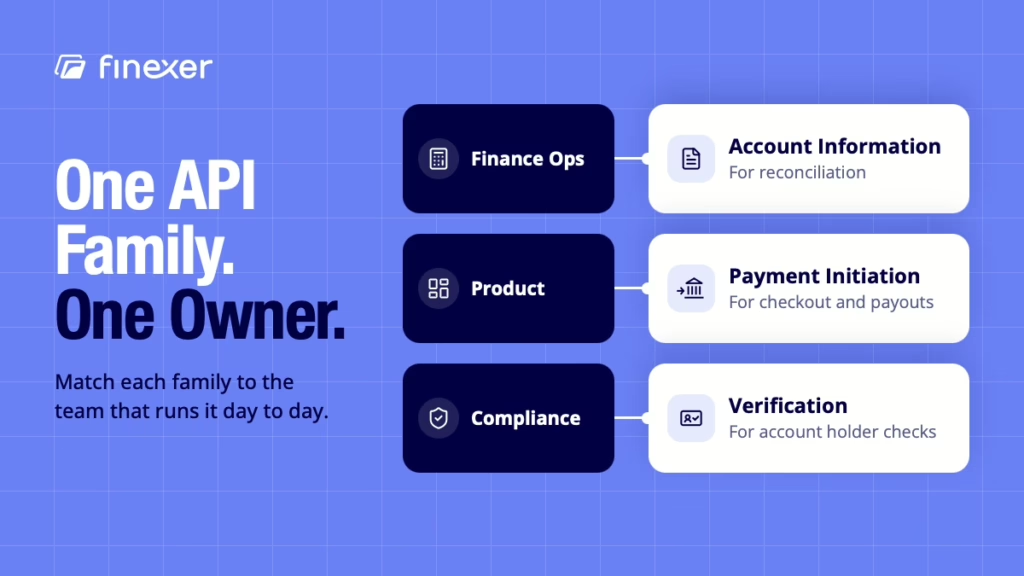
Finance operations teams rely on account information services for reconciliation, since transaction data comes straight from the bank rather than a manual export. Product teams typically own payment initiation services, since that’s what powers checkout or payout flows.
Compliance teams care most about verification, because it confirms who actually holds an account before money moves, and that every action is backed by customer consent on record.
Not every team needs all three; a lending platform might need account information and verification without payment initiation at all, which is exactly why treating APIs open banking as one bundled product rather than three separate decisions leads teams to buy more than they need. For a broader look at how these map to business benefits generally, see our guide to open banking for businesses.
What Are the Benefits of Open Banking APIs for Businesses?
Operationally, three things change once these APIs are live. Reconciliation runs from real banking data instead of manual statement uploads, so finance teams stop chasing PDFs. Payments initiated this way typically settle via Faster Payments, without waiting on card settlement cycles.
Onboarding checks confirm details against the bank record itself, rather than relying on a document the customer could have altered. None of this requires building separate integrations for each bank, or collecting fresh customer consent for every request beyond what was already granted; that’s the point of using APIs that open banking providers already maintain, rather than negotiating bank connections one at a time.
For the technical detail behind each family, including request and response formats, see open banking api examples. For the standards and specifications these APIs are built against, Open Banking API standards covers that separately, so this page doesn’t need to repeat either.
Where Finexer Fits?
Finexer covers all three API families, account information services, payment initiation services and verification, through one integration rather than three. It’s FCA-authorised for AIS and PIS, with transparent pricing (no hidden charges).
For a platform that only needs one of the three APIs open banking families today but expects to need another later, Finexer’s banking data API and its payment and verification counterparts sit on the same connection, so adding the second or third family later doesn’t mean a second integration.
What is an API in Open Banking?
It’s a secure, regulated connection that lets an authorised platform read a customer’s banking data or send a payment from their account, only with explicit customer consent given at the bank itself. It replaces manual uploads and screen-scraping with a direct line to the bank.
What are the benefits of Open Banking APIs for businesses?
Open Banking APIs help businesses reduce manual reconciliation work, simplify account-to-account payments, and verify account details using banking data. These capabilities can support more efficient finance operations, smoother payment flows, and more reliable onboarding.
Do I need all three API families, or just one?
Usually just the one or two that match what your platform actually does. A lender might need account information and verification; a marketplace paying out sellers might need payment initiation and little else.
Is Finexer only useful if I need all three?
No. Finexer supports each family independently, so a platform can start with one and add another later on the same integration rather than needing open banking api examples from three different providers stitched together.
One integration for account information, payment initiation, and verification, so you’re not maintaining three.
Explore with AI
About the Author
Ravi Ranjan
Ravi Ranjan is Co founder & CEO of Finexer