Most UK businesses researching recurring payment solutions land on a two-way comparison: Direct Debit or card-on-file. That comparison used to be enough. It no longer is. Variable recurring payments have moved from a talked-about feature to a live scheme with real transactions running through it.
This guide compares all three recurring payment solutions side by side: Direct Debit, card-on-file, and VRP. You’ll see how each one handles setup, payment failures, amount flexibility, customer control, settlement speed and reconciliation, so you can pick the mechanism that actually fits your billing model instead of guessing.
Key takeaways
- Direct Debit suits established collections with fixed or predictable amounts.
- Card-on-file supports fast subscription setup but is exposed to expired cards and issuer declines.
- Variable recurring payments let a customer approve bank-account collection within set limits, live in the UK since June 2026.
- A recurring payment system needs clear consent records, failure handling, payment-status events and reconciliation data, whichever mechanism sits underneath.
- Finexer provides the VRP collection layer beneath a business’s existing billing or operational platform.
What Are Recurring Payment Solutions?
Recurring payment solutions let a business collect money on an agreed schedule after the customer authorises the arrangement once. The customer does not approve every payment individually, though control and visibility depend on the mechanism doing the collecting.
Hold onto the distinction between billing and collection. A billing platform works out what the customer owes. A recurring payment system initiates the collection, a function usually called payment initiation services when a regulated third party does it on the business’s behalf.
Reconciliation matches the result back to the invoice it settles. A business can add a new collection mechanism underneath its existing billing platform. Comparing recurring payment solutions this way, as an add-on rather than a replacement, is usually the faster path.
What Is the Monthly Recurring Payment Meaning?
The monthly recurring payment meaning is simple: a business collects an authorised amount once a month, without asking for fresh approval each time. The amount can be fixed, like a £50 subscription, or variable, like a usage charge or a rent payment that shifts. What can be collected is set by the original authorisation, not renegotiated each cycle.
A monthly recurring payment is not a standing order, which the customer instructs their own bank to pay. A recurring payment is initiated by the business, or its provider, under a mandate or consent granted upfront. Four questions settle most of the comparison: can the amount change, can the customer revoke authorisation themselves, what happens after a failed payment, and can finance reconcile each payment automatically?
Which Recurring Payment Solutions Should You Compare?
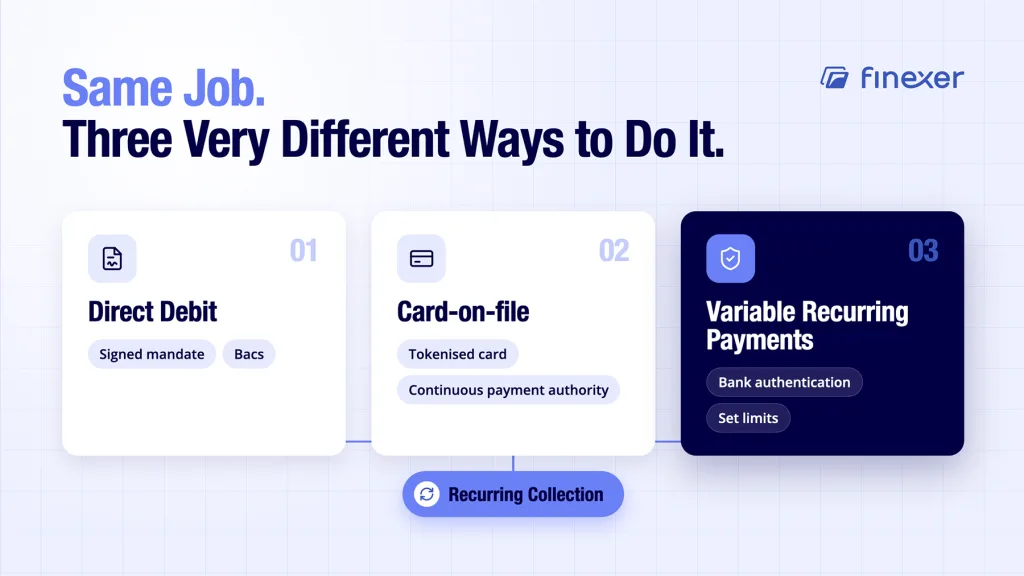
Three mechanisms cover almost every UK recurring collection: Direct Debit, card-on-file, and variable recurring payments.
Direct Debit
Bacs Direct Debit collects from a customer’s bank account under a signed mandate. It handles fixed and many variable amounts well, which is why it remains the default for rent, memberships, insurance and utility bills. The Direct Debit Guarantee protects the customer if a payment is taken in error. The trade-off is speed: a Bacs Direct Debit mandate typically takes days to activate, and status often depends on bureau reporting rather than a live event feed.
Card-on-file
Card-on-file stores a tokenised card reference under what schemes call a continuous payment authority. It suits digital subscriptions and fast sign-up services, since setup is close to instant. The recurring risk is involuntary churn: cards expire, get replaced after fraud checks, or get declined. A card account updater service can refresh some of that automatically, but a card-based recurring payment system built only around a continuous payment authority still needs decline classification and sensible retries, not a card account updater alone.
Variable recurring payments
Variable recurring payments let a customer approve an arrangement with defined limits, such as a maximum amount or expiry, and the business then collects within those limits without asking again. This is no longer a future promise.
The FCA confirmed the launch of the UK Payments Initiative scheme on 2 June 2026, the industry body running the UK’s first commercial VRP rulebook. Phase 1 covers regulated collections: utilities, government, charities and financial services. Wider ecommerce rollout is expected later in 2026, so variable recurring payments UK availability should still be checked corridor by corridor.
Retail customers already use a related version through sweeping VRP, moving their own money between their own accounts. Commercial VRP extends the same consent model that powers sweeping VRP to paying a real business.
How Do the Three Recurring Payment Methods Compare?
Side by side, on the seven factors that decide which one fits: setup speed, amount flexibility, failure causes, customer control, confirmation, settlement, and best use case.
| Criterion | Direct Debit | Card-on-file | Variable Recurring Payments |
|---|---|---|---|
| Setup | Mandate signed; days to activate | Card saved; near-instant | Bank authentication; set limits approved |
| Amount flexibility | Fixed or variable, within mandate | Fixed or variable, by provider | Variable, within approved limits |
| Common failure causes | Insufficient funds, cancelled mandate | Expired card, issuer decline | Insufficient funds, revoked consent |
| Customer control | Cancel via business or bank | Cancel via business or card issuer | Revoke consent via the bank |
| Settlement | Bacs collection timetable | Depends on acquirer | Instant via Faster Payments |
| Best suited to | Regular bills, long relationships | Fast-setup digital subscriptions | Variable, usage-based billing |
Each provider’s own implementation still affects real-world results.
Which Recurring Payment System Fits Your Billing Model?
Card-on-file suits fixed subscriptions where customers expect to pay by card. Direct Debit fits long-term, bank-account relationships just as well. Either way, the recurring payment system underneath should return failure reasons and payment-status events, not just a pass or fail.
Variable recurring payments earn their place on usage-based billing: the platform calculates the amount, the collection API validates it against the approved limit, and each attempt returns a clear result.
Rent platforms and financial-service top-ups with amounts that shift monthly both fit this pattern. High-value or irregular billing needs stronger controls regardless of mechanism: clear authorisation terms, amount limits and full audit records.
Involuntary Churn Is a Commercial Problem
Expired cards and failed bank collections remove revenue the business already earned, and the mechanism chosen changes how much is recovered. For the full mechanics of how VRP payments reduce this loss in UK recurring billing, our dedicated guide covers the churn math. This page stays focused on choosing between mechanisms.
Solution Categories to Shortlist
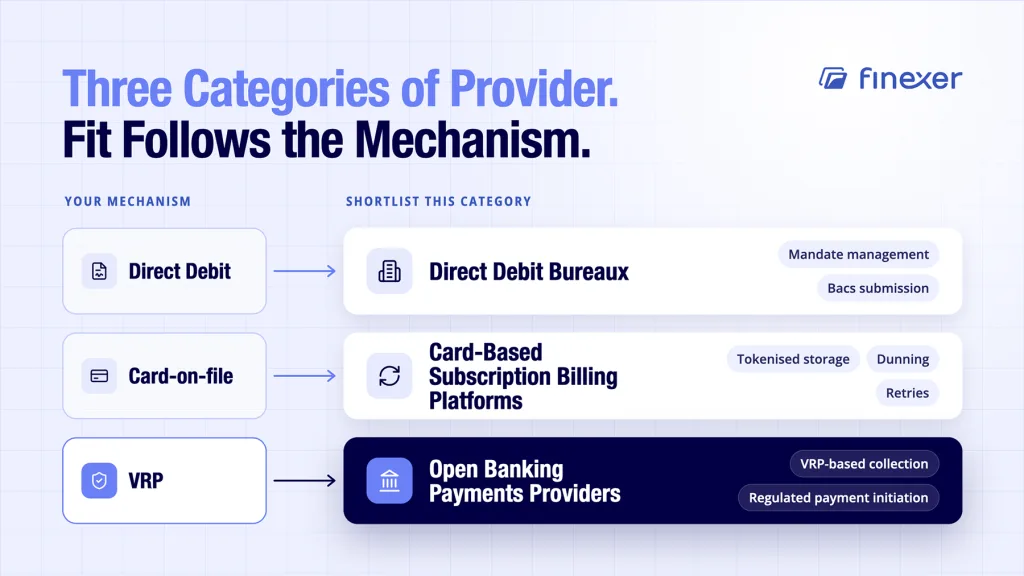
Direct Debit bureaux handle mandate management and Bacs submission on a business’s behalf. Card-based subscription billing platforms combine tokenised card storage with dunning and retries. A growing group of open banking payments providers offers VRP-based collection built on regulated payment initiation. Fit follows the mechanism your billing model points to, more than brand recognition.
What Should You Check Before Choosing a Provider?
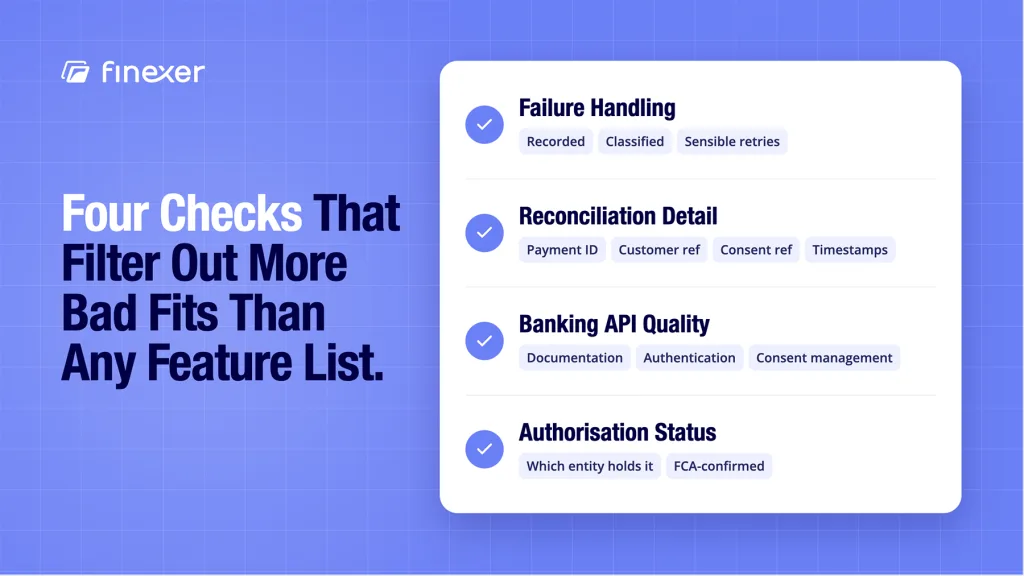
A responsible provider records the original failure, classifies the reason, retries recoverable failures at sensible intervals, and stops rather than repeating a hopeless attempt. Review your current approach to payment failure handling before switching, since the gaps often sit in process rather than the rail.
On reconciliation, ask whether every event includes a payment ID, customer reference, consent reference, amount, timestamps and failure reason, so finance can tell initiated, succeeded and settled apart at volume. Weigh these checks equally across every option on your recurring payment solutions shortlist, not just the one you already favour.
Banking API Quality
A Banking API should offer more than a payment button. Assess the documentation, the authentication flow, consent management, and how cleanly payment-status events arrive. A thin API means your team builds the missing parts anyway.
UK Payment Service Providers: Authorisation Status
Before signing, confirm the provider’s regulatory position. UK payment service providers must be authorised or registered for the service they offer, a requirement the FCA’s March 2026 approach document sets out directly. Ask which entity holds the authorisation and what happens if a connection fails. Assessing UK payment service providers on authorisation status first filters out more bad fits than any feature comparison will.
How Does Finexer Support Recurring Payment Solutions?
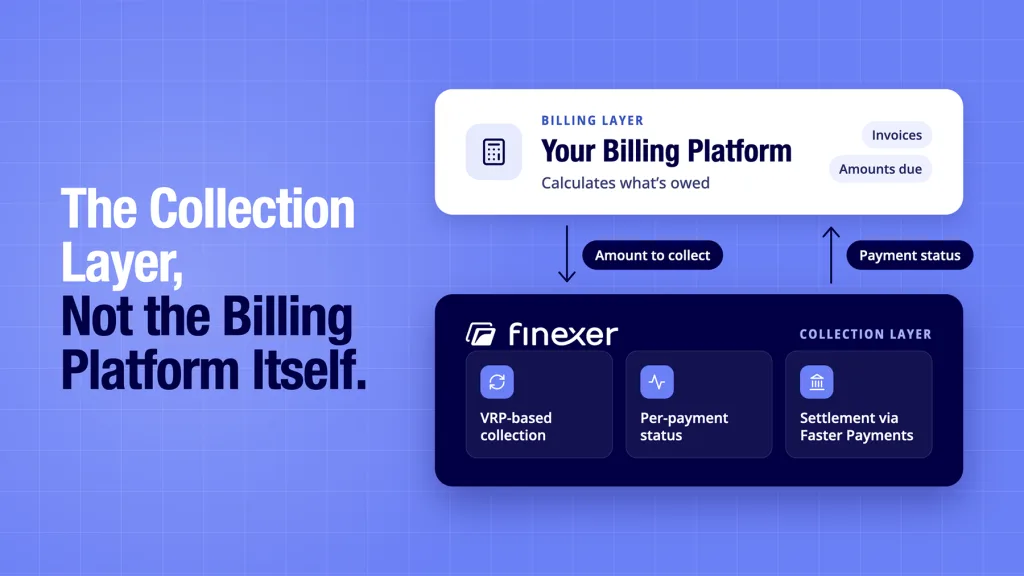
Finexer is not a Direct Debit bureau and not a subscription billing platform. It is the collection mechanism underneath one. Finexer’s Payments product supports VRP-based recurring collection, instant via Faster Payments on the UK domestic leg, with per-payment status returned as requested, initiated, received or matched.
This fits financial platforms, proptechs, employers of record, merchants, rent providers and SaaS businesses that already own their billing logic and need a dependable recurring payment system underneath it. Specifically:
- VRP-based recurring collection through Finexer’s Payments product
- Per-payment status tracking through the request-to-match lifecycle
- Instant settlement via Faster Payments for UK domestic collections
- FCA-authorised (FRN925695) as both AISP and PISP
- Covers almost all banks in the UK
- Transparent pricing with no hidden charges, 3-5 weeks onboarding support
Confirm exact bank coverage and scheme scope during technical review, since VRP availability still varies by provider and use case.
Bottom Line
The right choice among recurring payment solutions depends on how your business bills, not on a universal ranking. Direct Debit suits established bank-account collections. Card-on-file works well for fast subscription setup. Variable recurring payments now support customer-approved bank-account collection through a live UK commercial scheme, strongest today in regulated use cases.
Before choosing, check failure handling, consent visibility, provider authorisation, settlement speed and reconciliation output. Finexer fits businesses that already have billing logic in place and need a reliable VRP collection layer underneath it, with instant settlement and per-payment status built in.
Can a business switch from card-on-file to recurring payment solutions based on VRP?
Yes, but treat it as a payment-rail migration, not a simple API swap. Map existing customers, introduce the new consent journey, pilot it, reconcile both methods during the transition, and communicate the change clearly.
Does a business need a new recurring payment system to use VRP?
Not necessarily. A business can keep its existing billing platform if it can calculate amounts, call the collection API, and process payment-status events, with the VRP provider operating as the collection layer underneath.
What can variable recurring payments UK businesses actually collect right now?
Collection must stay within the customer-approved limits and scheme rules. Phase 1, live since June 2026, covers regulated sectors: utilities, government, charities and financial services. Confirm your use case and bank coverage before building against it.
How should a business handle a failed recurring payment?
Classify the failure, decide whether a retry makes sense, notify the customer if action is needed, and update reconciliation records. A failed payment is a decision point, not a generic error to ignore.
What should UK payment service providers offer for recurring collection?
At minimum: confirmed authorisation status, consent management, amount flexibility, retry support, webhooks, payment-status detail and reconciliation output, not just API documentation.
Add VRP-based recurring collection to your platform, with payment initiation, consent-led authorisation, instant settlement via Faster Payments and per-payment status built into the payment layer.
Explore with AI
About the Author
Ravi Ranjan
Ravi Ranjan is Co founder & CEO of Finexer