Real-time balance access across almost all major UK banks.
A failed payment rarely announces itself in advance. The balance was fine yesterday. It might not be today.
TL;DR: Anyone can check account balance in seconds through a banking app. A platform collecting money from someone else does not have that luxury, and a number from last week is not a balance: it is a memory. This article covers both sides, then gets specific about the part that actually affects revenue: reading a customer’s balance with their consent, at the moment a decision depends on it.
Finexer is an FCA-authorised (FRN 925695) Open Banking infrastructure provider working with UK payroll, invoicing and utility billing platforms on real-time account data. Everything below reflects how consented balance access actually works under that authorization and not a simplified version of it.
How Do I Check My Own Account Balance?
Most people check account balance online through their bank’s app or web portal, both updated close to real time for the account holder. ATMs and telephone banking work as well although telephone banking often reflects the balance as of the previous processing cycle rather than the current moment.
None of these methods help a platform that needs to check a customer’s balance before it acts. A person checking their own account is a different problem from a business that needs to check account balance online for someone else, with permission, before making a decision.
Why Would a Platform Need to Check a Balance?
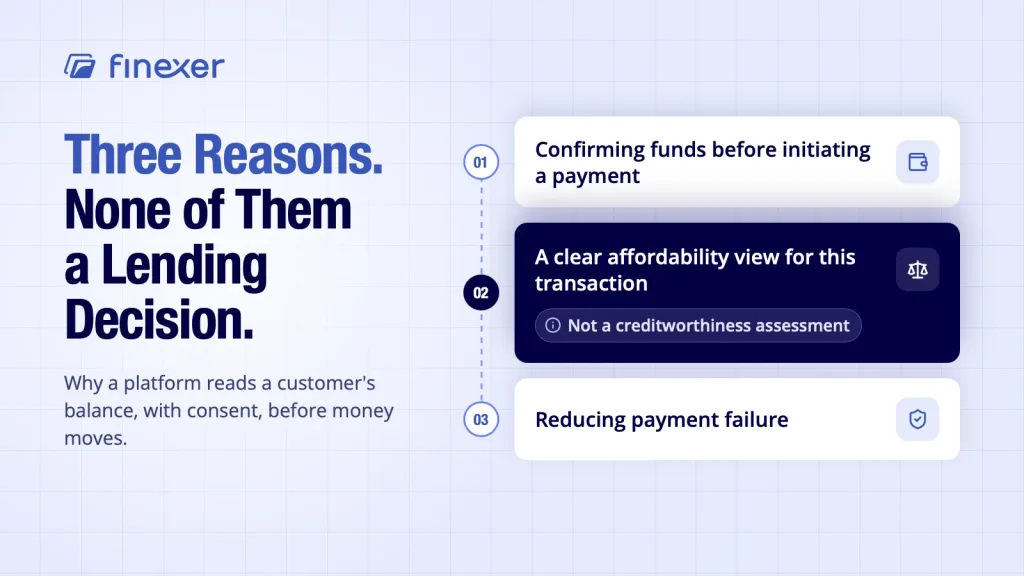
The commercial case is where this gets interesting. Platforms that check account balance on a customer’s behalf, with consent, usually do it for three practical reasons.
Confirming funds before initiating a payment. Rather than submitting a collection and hoping, the platform can see whether the money is there first.
Getting a clear affordability view for a specific transaction. This is not a creditworthiness assessment; it simply checks for whether this payment fits against what is currently in the account.
Reducing payment failure. Every failed collection costs a retry, a support ticket and sometimes a damaged customer relationship.
None of this touches lending decisions. A balance check tells a platform what is in an account right now. It says nothing about someone’s broader creditworthiness, and Finexer does not build for that use case.
How Do Consented Balance Checks Actually Work?
The mechanics matter here, because “real-time” gets used loosely across the industry.
The customer authorises the connection first, through their own bank, the same way any Open Bank data sharing flow works. Nothing happens without that step, and the platform never sees the customer’s banking credentials.
Once consent is granted, the platform reads the balance through a regulated connection via an api for bank transactions, pulled directly from the bank at the moment of the request. That is the distinction that matters: a live read and not a cached figure from an earlier sync.
Balance vs Available Balance: Why the Two Differ
A single number rarely tells the full story. Most banks return two figures, and platforms that look at only one make avoidable mistakes.
| Figure | What It Shows | Why It Matters |
|---|---|---|
| Current balance | Everything cleared into the account so far | Does not account for payments already authorised but not yet settled |
| Available balance | Current balance minus pending holds and authorisations | The more accurate figure for deciding whether a payment will clear |
A platform that reads current balance alone can approve a payment that the available balance would have flagged as risky. That gap is where most failed collections quietly originate.
What a Balance Check Does Not Tell You
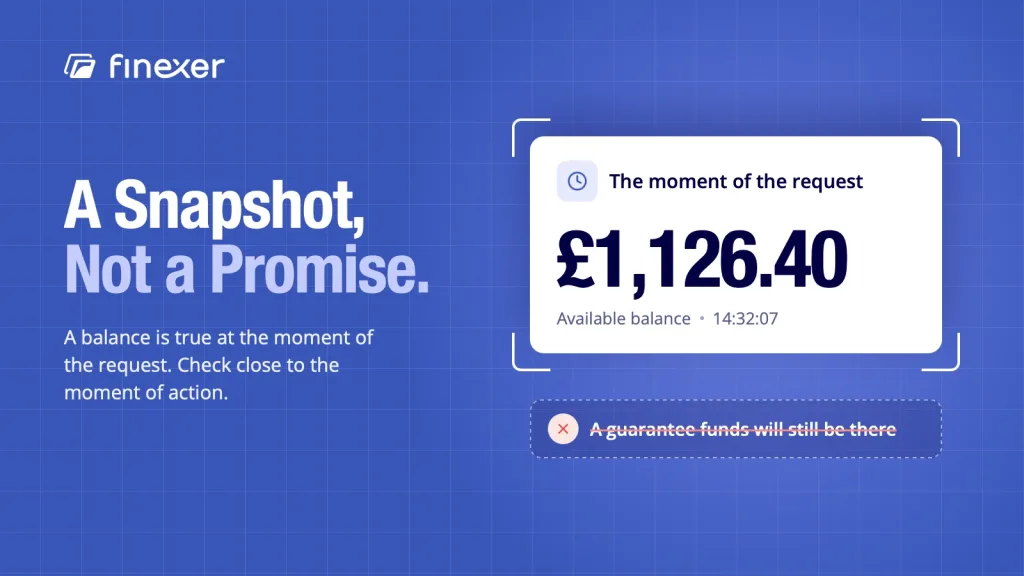
Honesty matters more here than anywhere else in this guide. A balance check is a point-in-time figure, taken at the moment of the request. It is not a guarantee that funds will still be there five minutes later, and it does not guarantee a subsequent payment will succeed.
Treating a balance check as a promise, rather than a snapshot, is how platforms end up designing badly around it. The right response is to check close to the moment of action, not once at onboarding and never again.
How Do UK Providers Compare on Balance Access?
Coverage and depth vary across the market. Based on what providers state publicly, the pattern looks like this:
| Provider | Position | What to Know |
|---|---|---|
| Finexer | AIS + PIS, UK-focused | Built for UK banks specifically, with consented balance and transaction access in one API |
| TrueLayer | AIS + PIS, UK-founded | Strong documentation, skews toward enterprise and large fintech |
| Yapily | AIS + PIS, developer-first | Covers 19+ European countries, not UK-only |
| Tink | AIS + PIS, Visa-owned | Strong European coverage, enrichment-led |
| Plaid | AIS-led, US-origin | Global institution reach, UK product depth still maturing |
| GoCardless | PIS-led, UK-founded | Strong in recurring collections, less AIS balance depth |
None of this is about one provider being faster or cheaper. It is about which one answers the balance question when a platform actually needs it.
How Finexer Handles Consented Balance Access
Platforms lose money every month to payments that fail against an account that looked fine days earlier. That gap between assumption and reality is the whole problem.
Finexer’s bank data API gives UK platforms consented, real-time balance and transaction access across almost all major UK banks. The read happens at the moment it is requested, not from a stored copy, and it sits alongside Finexer’s three-way data structure of account, balance and transaction data, so a platform gets balance context without a second integration.
- Real-time balance reads at the point of decision
- Available balance visibility and not just current balance
- One regulated connection for balance and transaction data together
- Built for UK banks and not adapted from a global product
Where This Shows Up in Practice
Three ICPs use consented balance checks the same way, just at different moments in their workflow.
- Payroll and Invoicing: confirming a client account can cover a payout before it is submitted
- Utility Billing: reading a balance before a Direct Debit retry, instead of resubmitting blind
- Proptech: verifying funds before rent collection, rather than after a bounced payment.
Is checking a balance the same as a credit check?
No. A balance check reads what is currently in an account. It does not assess creditworthiness or affect a credit file, and Finexer does not offer lending or credit decision-ing products.
Does a balance check need to happen every time before a payment?
It depends on the risk of the transaction. Higher-value or higher-risk payments benefit most from a check close to the moment of collection.
How current is the balance a platform sees?
It reflects the live figure from the bank at the moment of the request and not a cached or previously synced number.
Can a balance check stop every failed payment?
No single check guarantees that. It reduces avoidable failures caused by acting on stale information, but funds can still move between the check and the payment itself.
See Real-Time Balance in Action
See how Finexer’s Data product gives UK platforms consented, real-time balance access so decisions are made on current figures and not stale records.
Explore with AI
About the Author
Ravi Ranjan
Ravi Ranjan is Co founder & CEO of Finexer