Stop guessing what your banking statement API returns.
See account, balance, transaction and enrichment data firsthand.
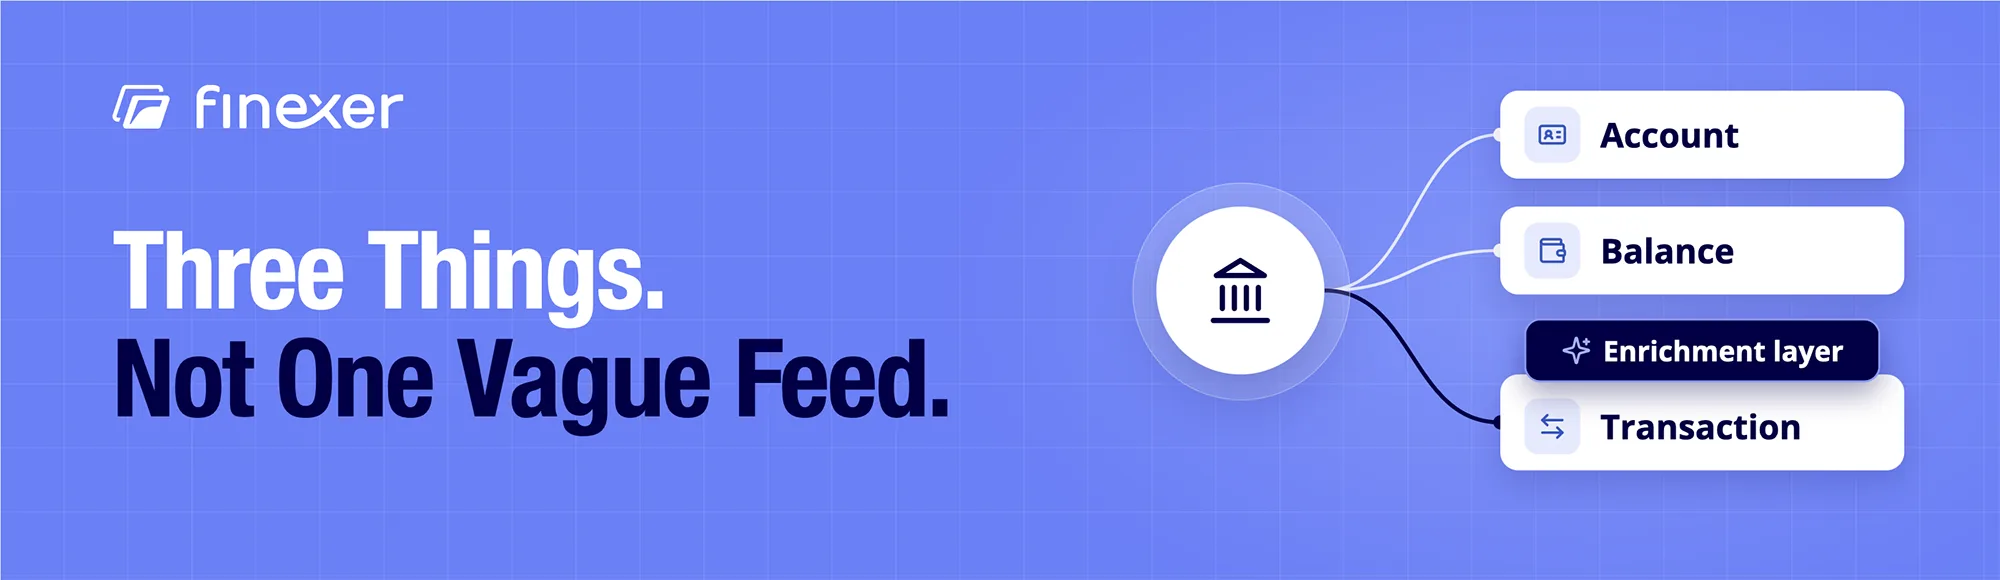
A UK Open Banking bank statement API returns three things: account data, balance data and transaction data. Enrichment adds merchant identification and category on top of the raw banking statement API data. That’s about the full extent of the ability of any compliant provider to pull details from a customer’s banking account.
| Data Type | What It Contains |
|---|---|
| Account data | Account name, number, sort code, IBAN, currency |
| Balance data | Current balance, available balance, credit line |
| Transaction data | Date, reference, amount, status, transaction code |
| Enrichment (added layer) | Merchant name, spending category, confidence score |
Each type of banking statement API data comes from a separate endpoint. A platform can request one, two or all three from a bank statement API, depending on what it is building. None of them require the customer to upload a statement file.
What Does Account Data Include?
As the first layer of banking statement API data, account data confirms which account the customer connected. It returns the account name, account number, sort code, IBAN where applicable and currency.
This is the identity layer. It answers “which account is this” before balance or transaction data gets requested against it.
What Does Balance Data Include?
Balance data returns the account’s current and available balances, plus any credit line where one exists. It’s a snapshot at the moment of the request, refreshed each time the bank statement API is called.
This part of banking statement API data matters for platforms doing affordability checks or confirming whether funds are available before triggering a payment.
What Does Transaction Data Include?
Transaction data is the largest part of banking statement API data, and the one most platforms actually build on. Each transaction record includes the following:
- Date and time
- Reference or narrative text
- Amount and direction (in or out)
- Status
- A transaction code
The depth of banking statement API data varies by bank. Some connections return up to eight years of history via retro_date, while others cap out closer to two years, depending on what the bank itself supports.
What Does Enrichment Add to the Feed?
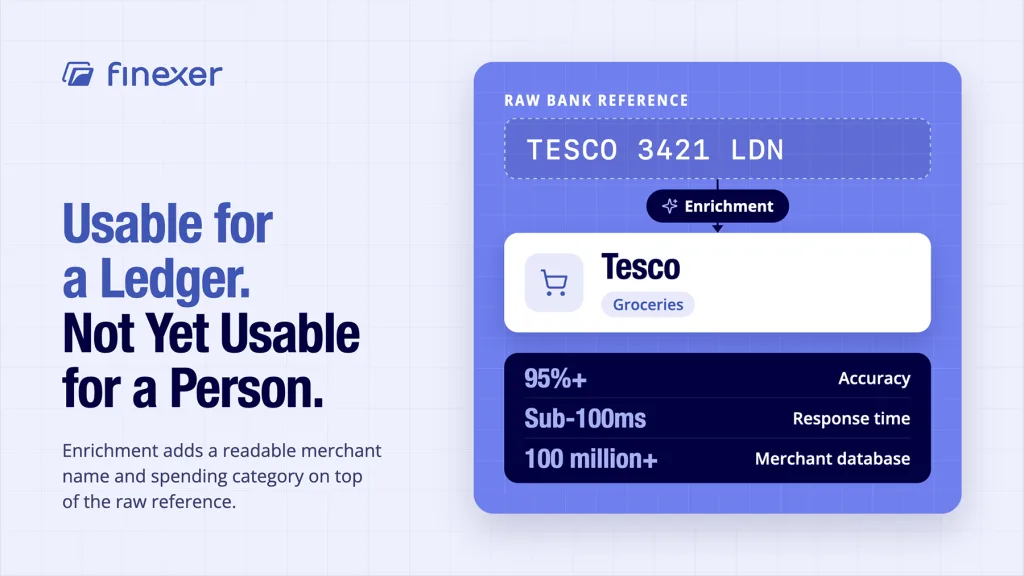
Standard banking transaction data arrives with a bare reference string, something like “TESCO 3421 LDN” rather than a readable merchant name. That’s usable for a ledger but not for a customer-facing app.
Enrichment adds merchant identification and a spending category on top of that raw reference. Finexer’s banking data API runs enrichment at over 95% accuracy, in sub-100ms, against a database of 100 million-plus merchants. Finexer is FCA-authorised, FRN 925695.
Without enrichment, a platform receiving banking statement API data builds and maintains its own merchant-matching logic. With it, that work sits with the provider instead.
What Isn’t Covered by a Bank Statement API?
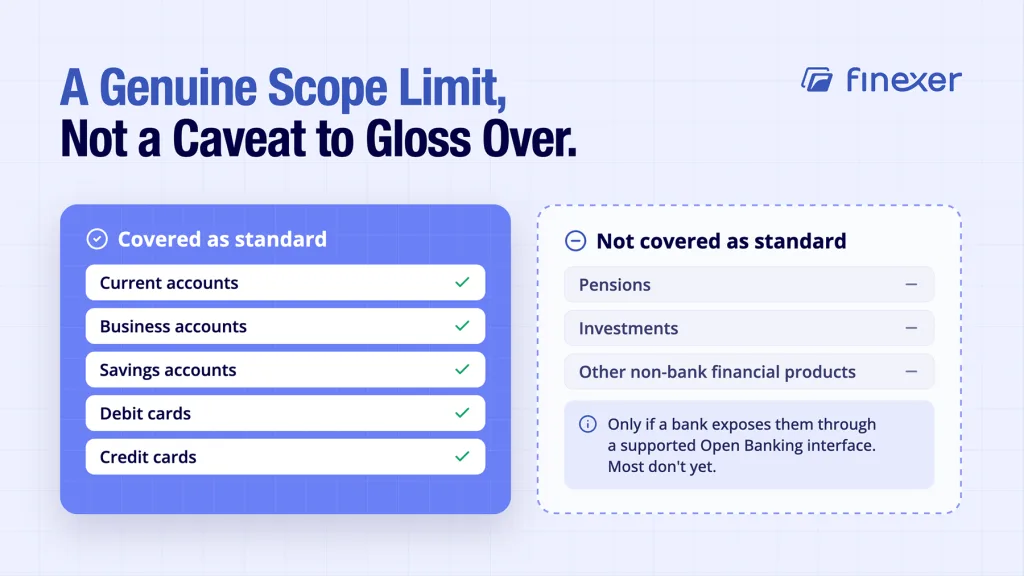
Standard banking statement API data covers current, business, savings, debit-card and credit-card accounts. It does not cover pensions, investments or other non-bank financial products unless the bank exposes them through a supported Open Banking interface, which most don’t yet.
This is a genuine scope limit of any bank statement API and not a caveat to gloss over. A platform building a full net-worth view, rather than a transaction or affordability view, needs a different data source for that portion.
Choosing Between Providers on Data Depth
Not every provider returns the same banking statement API data, and history depth is the detail most buyers miss during a demo.
Before committing to a bank statement API, confirm against a provider’s actual docs and not their sales deck as to whether the field set matches the three-way breakdown above and whether something is bundled in ambiguously.
Enquire into the real transaction history depth per bank and not just the headline maximum.
Check whether enrichment is a separate add-on or an inclusion in the base data call. Do examine the API for whether it serves platforms such as AIS API for SaaS platforms or is built primarily for consumer apps.
Providers across the market structure banking statement API data differently. Some return transaction data without enrichment as standard, pushing merchant-matching work back onto the platform; others bundle it. Teams building financial reporting tools specifically should confirm that enrichment is included before scoping their own matching logic on top.
Does a bank statement API replace uploaded PDF statements?
Yes, for any bank the API supports. It returns structured, real-time banking data directly from the account, rather than a document that needs parsing.
How current is the data returned?
Balance and transaction data reflect the account at the moment of the request. This is real-time banking data, not a periodic export.
Can a bank statement API access pension or investment accounts?
Only if the bank exposes them through a supported Open Banking interface, which is uncommon today. Standard coverage is current, business, savings and card accounts.
Do all UK banks return the same transaction history depth?
No. Depth depends on what the individual bank supports, from roughly 2 years up to 7 years via retro_date on banks that allow it.
Stop maintaining your own merchant-matching logic. Get account, balance, transaction and enrichment data from one API.
Explore with AI
About the Author
Yuri
Yuriy Yakushko is a fintech founder and software engineer with over 20 years of experience building financial technology. He’s passionate about creating scalable, secure infrastructure that helps businesses modernise how they access financial data and manage payments.