Client Picture Without Chasing
Consented account data instead of statement requests.
Financial advisory services firms and the platforms they use are the audience for this page. It is not for consumers looking for an adviser.
Before an adviser can assess a client’s position, someone has to collect statements, reconcile figures, identify missing accounts and decide whether the picture is current.
TL;DR: Advisory firms do not need another advice guide. They need a better way to assemble client financial information.
Consent-based account access can replace repeated PDF and CSV requests with account, balance and transaction data through Open Banking. For corporate financial advisory services, the case becomes stronger when clients hold several accounts or entities.
This is a firm-side view of the client-data problem, grounded in UK Open Banking infrastructure and the operational questions that matter when banking information moves into an advisory workflow. Finexer supplies infrastructure to B2B platforms. It does not give financial advice to consumers.
Where does the client data problem start for financial advisory services?
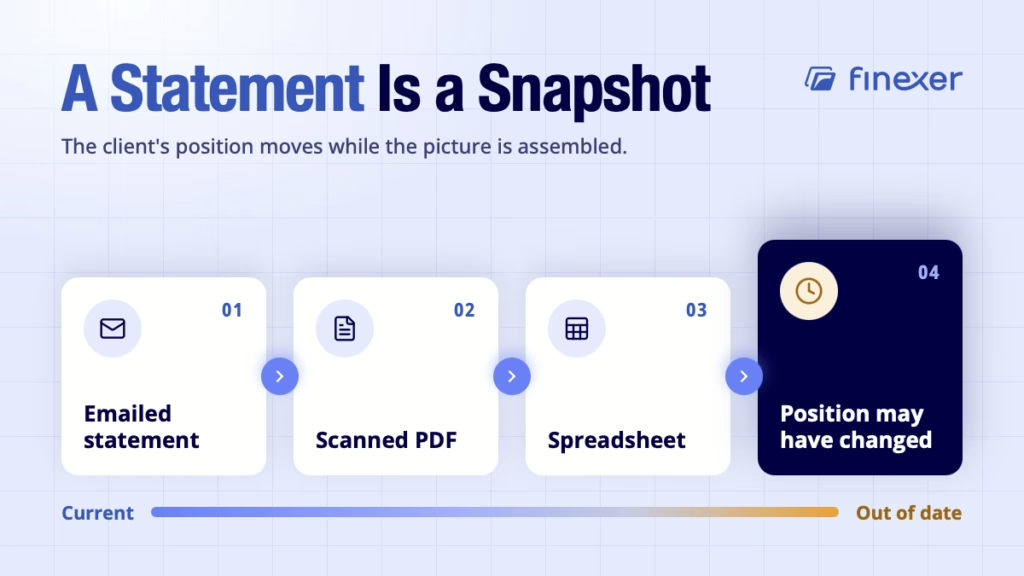
It starts at collection, because advice depends on a financial picture assembled from several documents.
A client may send statements by email, upload PDFs or provide spreadsheets covering different periods. A statement is a snapshot. By the time a firm has requested, received, checked and entered several documents, the client’s position may have changed.
The FCA’s financial advice market data, published in April 2026 from survey submissions extracted in December 2025, shows around 5,500 firms offering financial advice, about 31,000 advisers, 4.1 million retail clients and £1 trillion in assets under advice. The typical adviser has about 150 clients.
What changes with consented account access?
Open Banking changes the collection step by replacing document requests with customer-authorised access to account information.
The client connects an account and authenticates with their bank. An authorised Account Information Service Provider can then provide permitted information to the receiving platform.
| Data type | What arrives | Advisory use |
|---|---|---|
| Account data | Account name, number, sort code, IBAN and currency | Identify connected accounts |
| Balance data | Accrued balances, currency and credit line | Build a current position |
| Transaction data | Date, reference, amount, status and code | Review financial activity |
This is where UK financial data becomes operational. The platform receives structured information from connected accounts.
Open Banking Limited reported 2.97 billion successful API calls and 42.03 million payments in August 2026, with average weighted API availability of 99.98% (Open Banking Limited).
Corporate financial advisory services need more than one account
Corporate financial advisory services face a different version of the same problem.
A business client may have several current accounts, savings accounts, cards or accounts associated with different entities. Manual collection can turn one client relationship into a document-management exercise.
| Question | Why it matters |
|---|---|
| Can business accounts connect? | Personal-account coverage is not enough. |
| Can several accounts be accessed? | Advisers may need a wider picture. |
| What data is returned? | Different fields serve different workflows. |
| How is consent managed? | Access must remain tied to authorization. |
| What happens when access needs renewal? | The client journey must handle change. |
Some providers, Yapily among them, also support consumer, business and corporate accounts alongside UK and European coverage.
Finexer Data covers current, business, savings, debit-card and credit-card accounts, subject to what the connected bank exposes through its Open Banking interface.
What should advisory firms require from a data provider?
A provider evaluation should start with the workflow rather than the feature list.
Five checks matter most:
- Regulatory standing. Confirm FCA authorisation and the legal basis for the data service.
- Account coverage. Test high-street, challenger, personal and business accounts that match your clients.
- Data structure. Confirm that account, balance and transaction data arrive in a usable form.
- Consent handling. Understand authorisation, reconfirmation and what happens when access changes.
- Retention and controls. Establish what your platform stores, for how long and under which policies.
This checklist does not replace technical due diligence, particularly for Open Banking financial services.
Data quality is a professional-risk question
“Data quality” can sound like an engineering concern. For an advisory firm, it is closer to a professional workflow concern.
If transactions are missing, duplicated or difficult to interpret, the adviser inherits uncertainty.
Transaction descriptions also exist primarily for banking systems. They are not necessarily written for an adviser or a financial planning interface.
That is why spending data deserves attention during vendor assessment. The issue is not merely whether a provider returns transactions. It is whether the information supports the workflow.
Finexer’s separate Enrichment product adds merchant identification and transaction categorisation to standard Open Banking transaction data.
Consent needs a place in the operating model
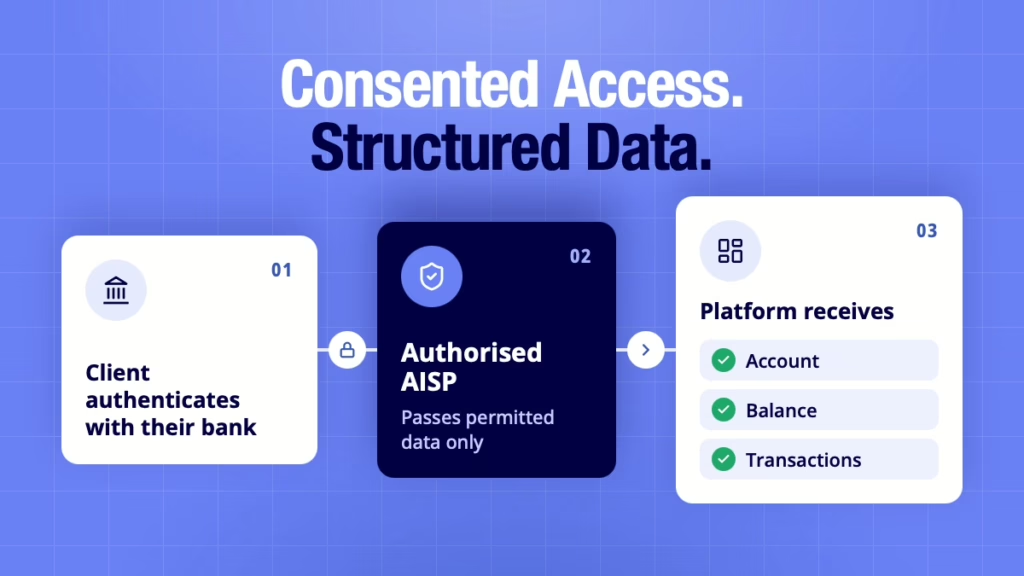
Open Banking financial services work because the customer authorises access.
The client authenticates with their bank, while the authorised provider passes permitted information to the receiving platform. The provider does not receive the client’s bank password.
Consent also needs operational treatment after the first connection. UK Open Banking includes customer reconfirmation requirements.
For firms building or buying advisory technology, consent should appear in process maps, customer communications, audit records and exception handling.
Our guide to Open Banking data sharing shows how consented access fits into a wider client journey.
Firms must apply their own regulatory, privacy, retention and record-keeping requirements.
How Finexer fits the advisory platform
Advisory platforms need a current client picture without chasing statements. Finexer’s Data product provides consent-based access to account, balance and transaction data, and the platform uses it to build its own client experience.
Finexer is FCA-authorised under FRN 925695. It is infrastructure, not financial advisory software, and it does not provide advice to consumers.
For a platform assessing Finexer for advisory work:
● Almost all major UK banks covered, across high street, challenger and business accounts.
● Account, balance, and transaction data through AIS.
● Support for multiple connected bank accounts within a consent journey.
● White-label infrastructure, so the platform retains its client-facing brand.
For corporate financial advisory services, Open Banking for business accounts is the relevant evaluation path because business-account coverage can determine whether a platform fits its client base.
Where Finexer sits against other providers
TrueLayer, Yapily, Tink, Plaid and Token.io sit in the combined AIS and PIS category. Moneyhub Enterprise has a strong Open Finance position for wealthtech, while Armalytix focuses on Open Banking-based financial health and audit data for accountancy firms.
TrueLayer has a strong UK presence and API documentation. Yapily combines UK and European coverage. Tink connects thousands of European financial institutions. Plaid brings significant US market presence. Moneyhub Enterprise is positioned around Open Finance and wealthtech.
For a UK-first advisory platform, the comparison that actually matters isn’t market positioning; it’s bank coverage, business-account support, consent, data structure, regulatory position and integration model.
The buying decision
Advisory platforms need to know whether client information can move from consented bank access into their workflow with the coverage, structure, controls and operational fit they require.
- Before choosing a provider, ask:
- Which client account types can we connect?
- Can business and multi-account scenarios work?
- What account, balance and transaction fields arrive?
- How does consent renewal appear to the client?
- How are connection failures and missing data handled?
- Which data remains with the provider, and which data do we retain?
- Can our platform keep its own brand and client journey?
- What evidence can the provider give us during technical testing?
Can advisory platforms use Open Banking without becoming a financial adviser?
Yes. A platform can provide the technology behind an advice journey without giving personal financial recommendations itself. Whether it needs its own FCA permissions depends on the service it provides and its operating model, so a platform should take regulatory advice on its specific set-up before launch.
Does Open Banking cover pensions and investment accounts?
Not generally through Finexer Data. Pensions, investments and SIPPs are outside its scope unless a bank exposes them through a supported Open Banking interface. Advisory platforms that need those holdings will usually combine account data with a separate source for investment and pension information.
Is transaction categorisation the same as account data access?
No. Account data access retrieves account, balance and transaction information through AIS. Transaction categorisation is a separate step that interprets each transaction, for example by identifying the merchant and assigning a spending category. Finexer offers the two as separate products, Data and Enrichment.
How long does client consent last in UK Open Banking?
Consent can run on an ongoing basis or for a defined period, rather than expiring after a fixed term. Under UK rules, the client reconfirms consent with the account information provider at least every 90 days, a short step in the platform’s journey rather than a full reconnection at the bank.
Final word
A better financial advisory services workflow may not start with better advice software. It may start with better client information.
When consented banking data reaches the platform in a usable form, the firm can spend less time assembling the financial picture and more time working with the client.
For advisory platforms buying Open Banking financial services, test the data, consent journey, account coverage and infrastructure against the workflow you need.
Advisory platforms get client account data: consented by them, enriched by Finexer and with Finexer replacing weeks of onboarding documentation.
Explore with AI
About the Author
Ravi Ranjan
Ravi Ranjan is Co founder & CEO of Finexer