Category: Finexer-Open Banking
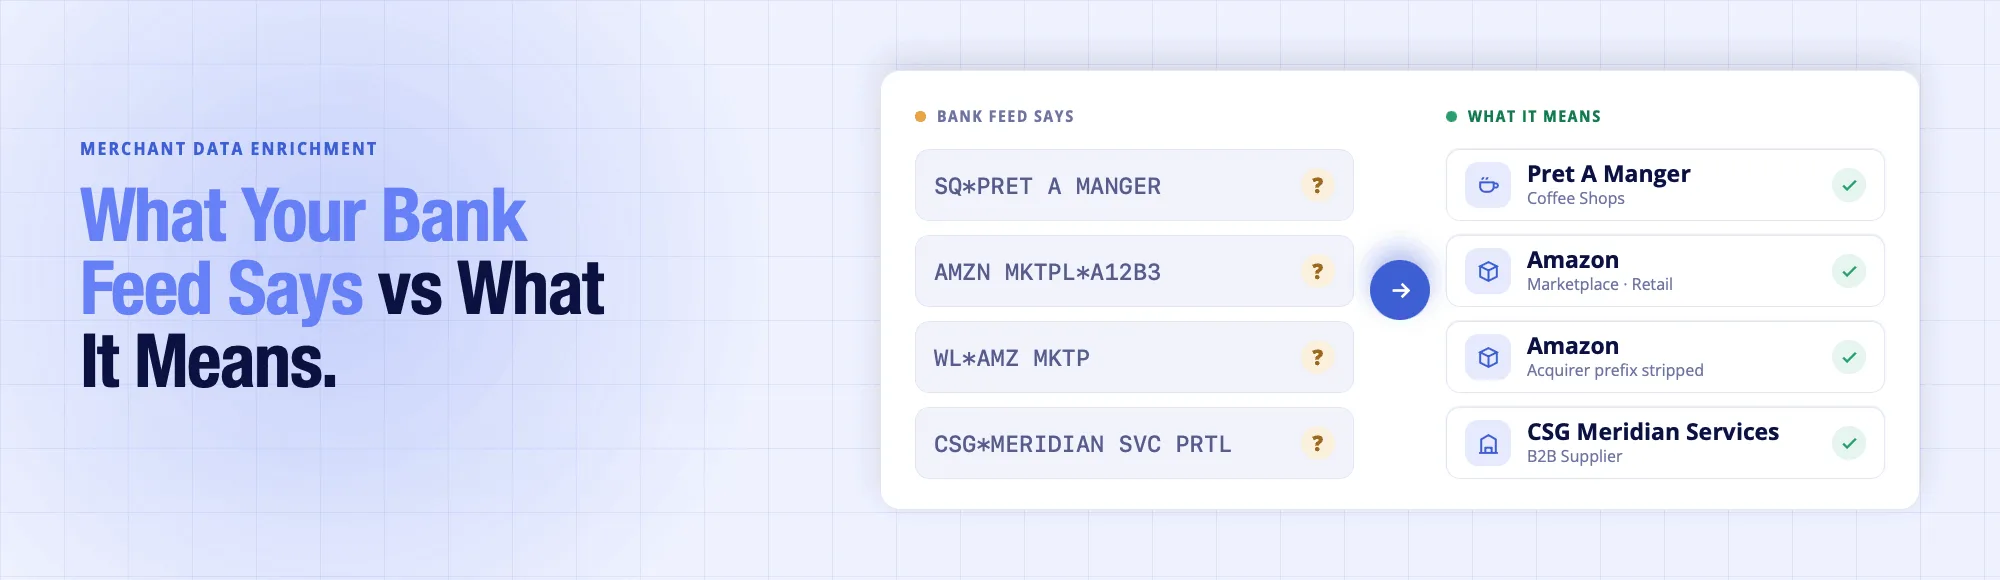
Merchant Data Enrichment APIs Compared: From Cryptic Strings to Clean Merchant Names
Merchant data enrichment resolves raw bank transaction strings – SQPRET A MANGER, AMZN MKTPLA12B3 – into clean merchant names, categories, logos and locations. This comparison covers how five merchant data enrichment APIs process those strings, what each provider returns, which fits your UK platform use case and coverage requirements, and what to test before choosing.
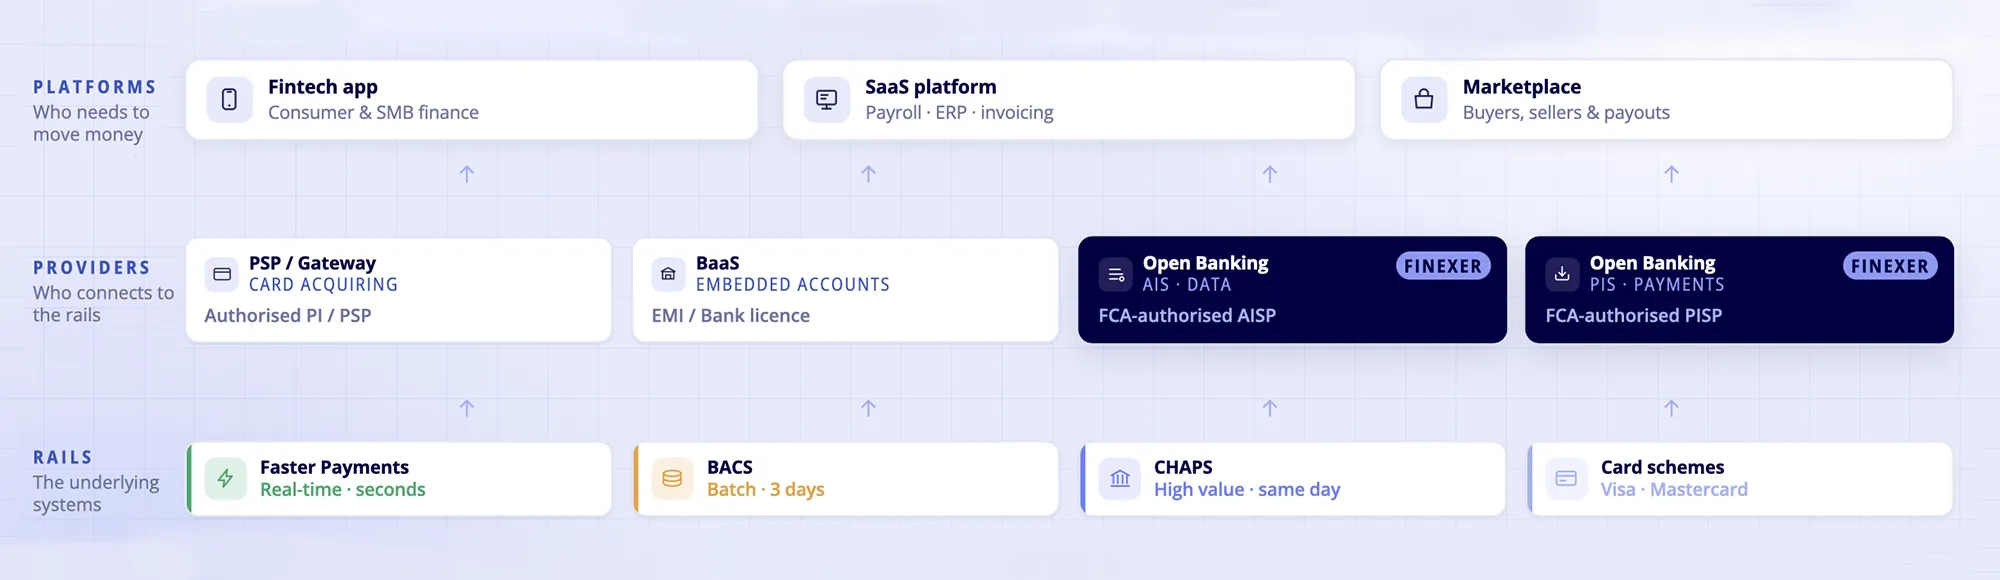
Payment Infrastructure UK: The Full Stack from Rails to Regulation
Every payment a platform processes touches infrastructure it did not build and regulation it did not choose. Understanding the UK payment infrastructure stack – the rails, the provider categories, and who regulates what – is the decision that shapes everything downstream: cost, speed, coverage, compliance, and how easily the stack can change when requirements do.
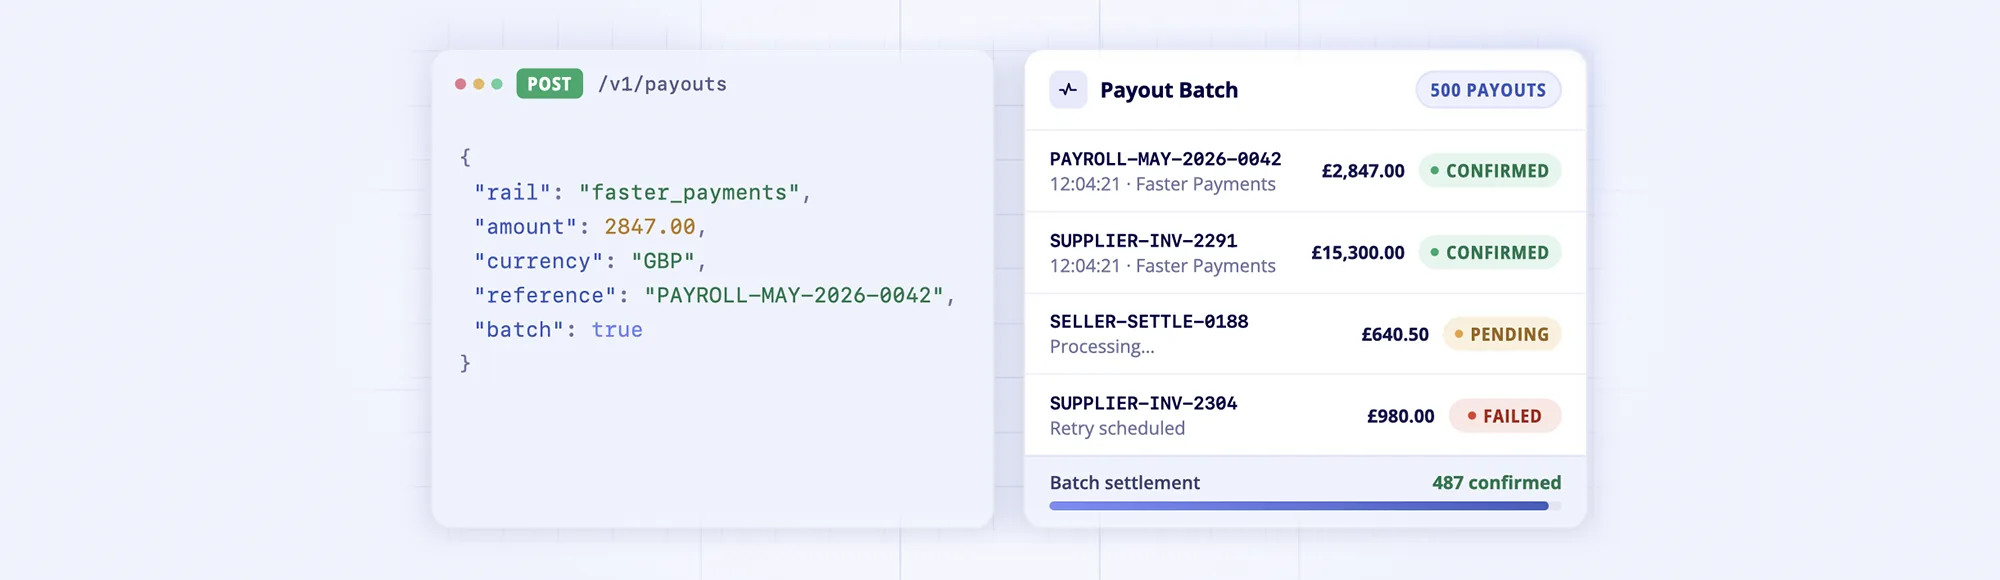
Global Payments API for UK Payout Infrastructure
A global payments API for UK platforms connects domestic GBP payout rails, international recipient disbursements and per-payout reconciliation into one infrastructure layer. This guide covers what rail-aware routing delivers, where Open Banking fits the UK payout stack, how Finexer International Payouts handles UK-origin outbound disbursements to recipients, and what to evaluate beyond the feature page.
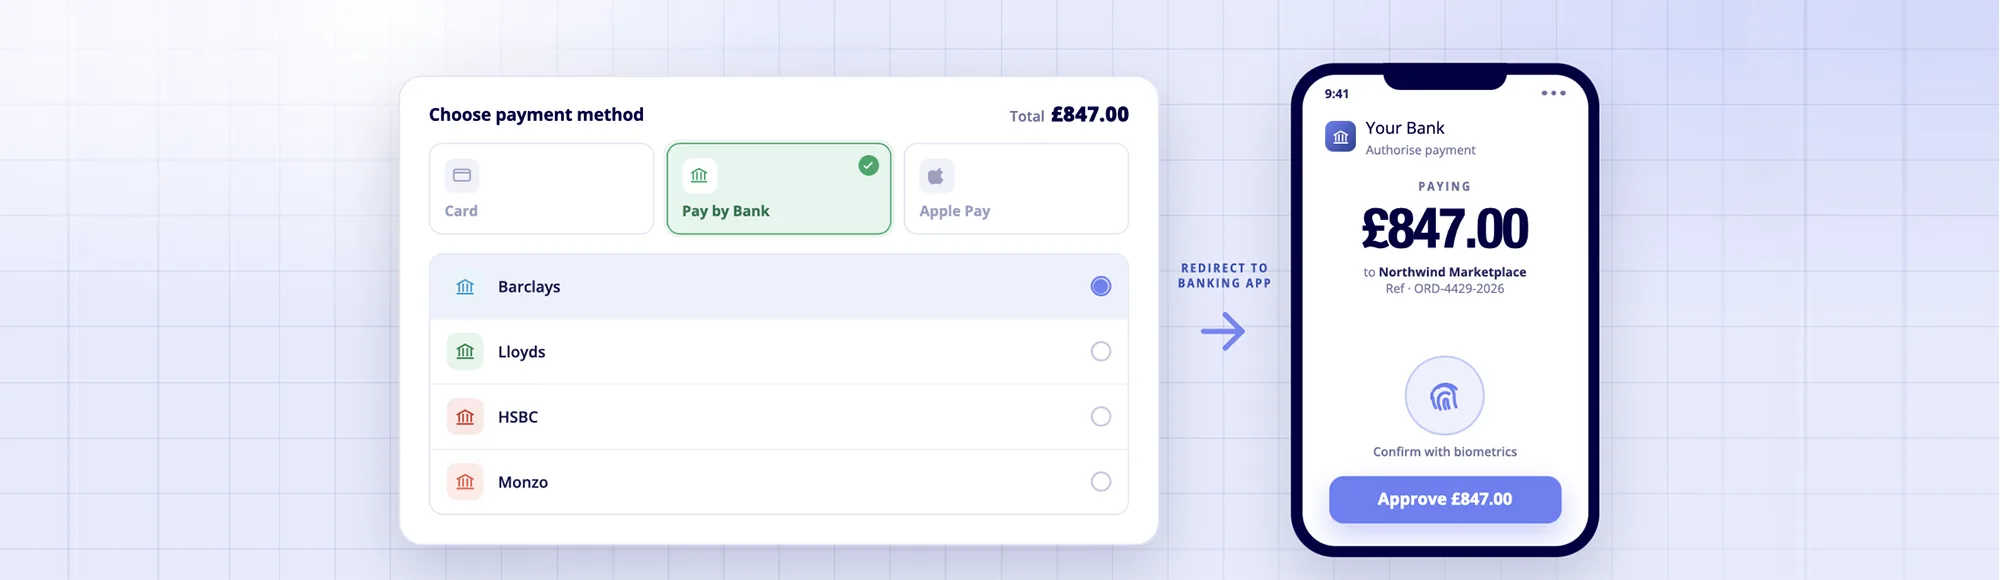
How to Add Pay by Bank Transfer to Your Platform Checkout
Card fees stack up. Checkout friction adds up. A growing share of UK buyers are now comfortable paying directly from their bank. Implementation playbook for platform teams adding pay by bank transfer as a checkout option – covering engineering scope, webhook handling, edge cases, and what this checkout option genuinely does and does not replace.
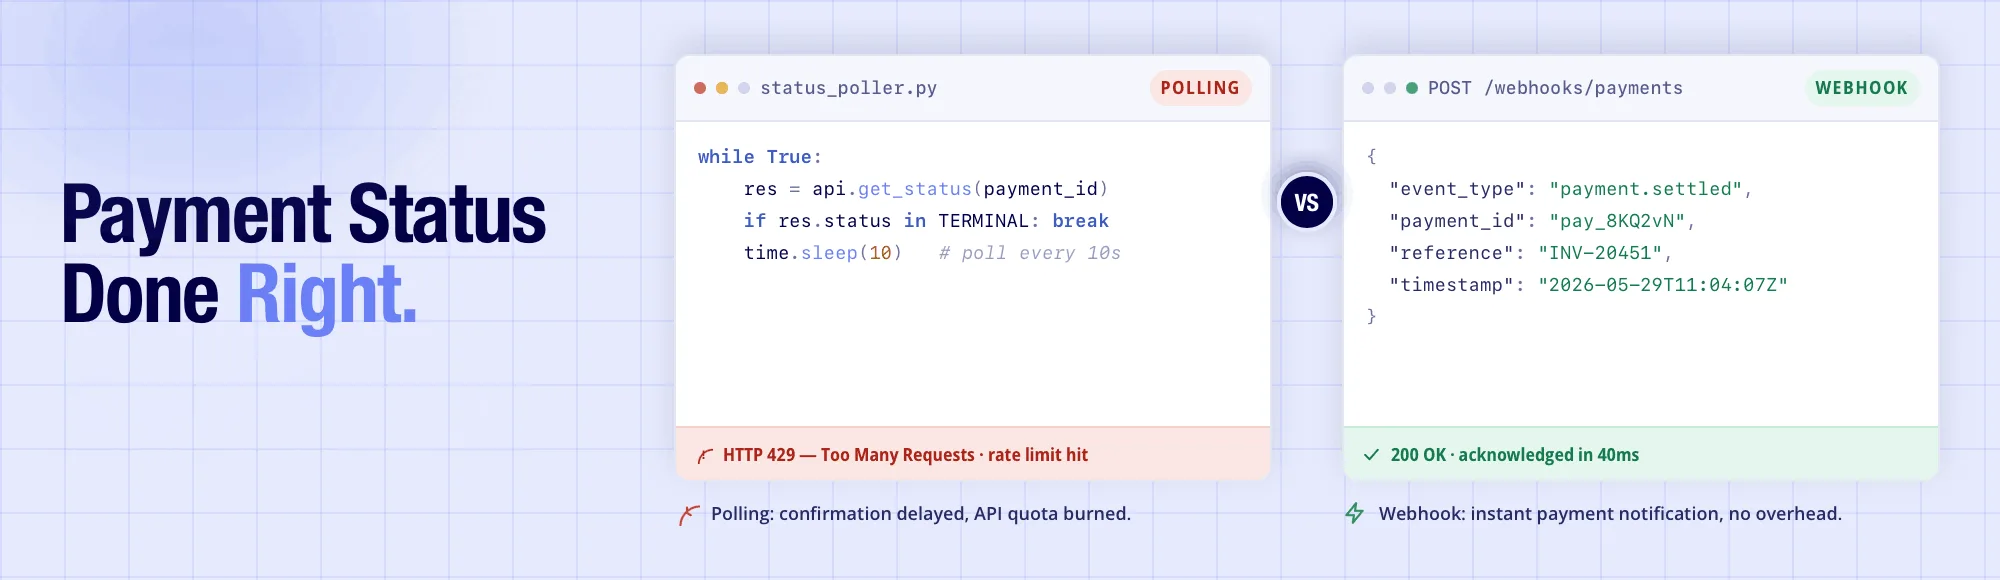
Payment Status Tracking: Webhooks vs Polling and the Open Banking Approach
Payment status is one of those things that looks simple until you are running payment workflows at volume on a UK platform. Polling creates rate limit pressure, confirmation delays, and reconciliation gaps that compound with scale. This is how webhooks, idempotency, and bank-confirmed instant payment notification change the operational picture for engineering and product teams.
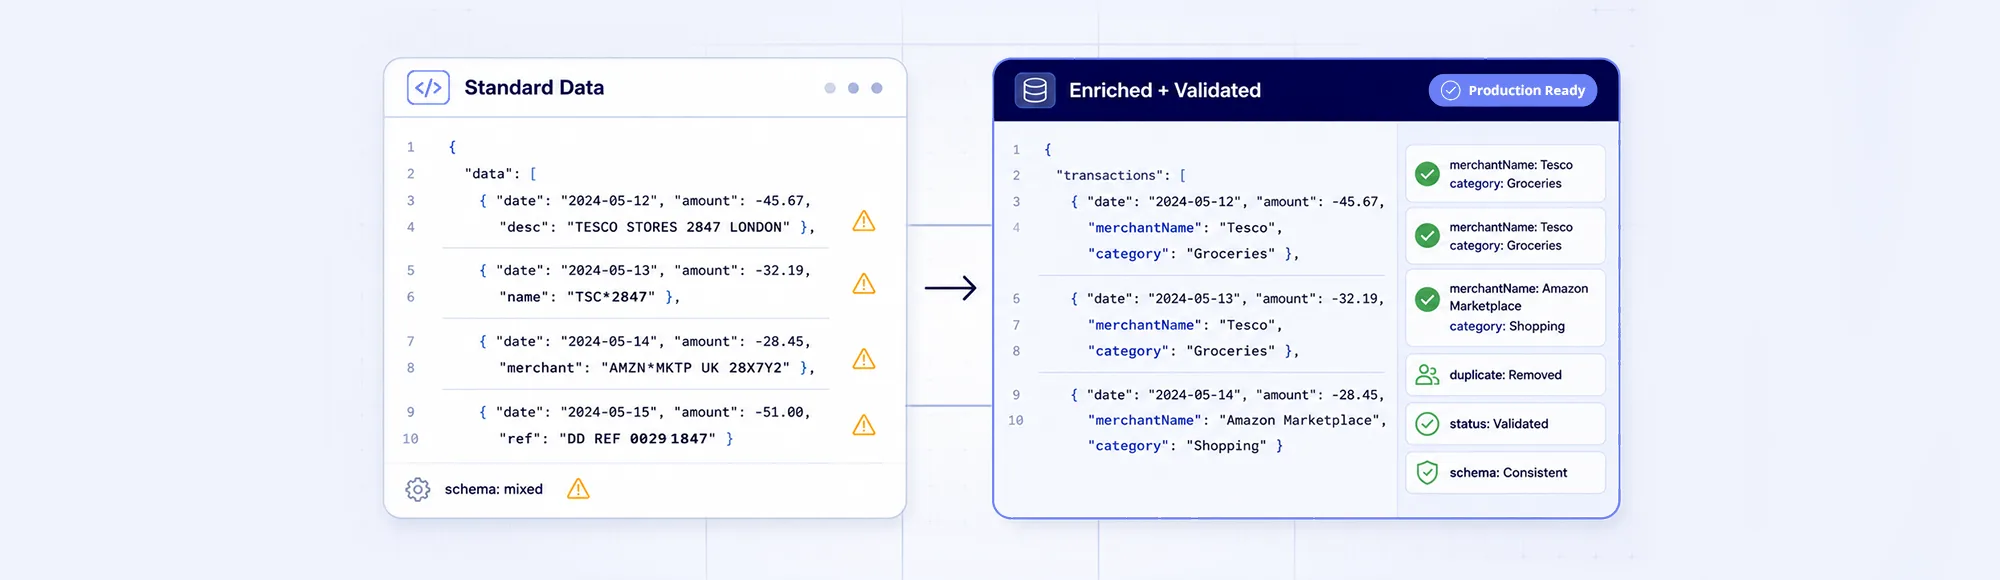
Standard Bank Transaction Data Is the Foundation. Why Enrichment and Validation Both Matter.
Standard bank transaction data gives platforms the foundation they need – account activity, balances, amounts, and payment references. Financial data enrichment adds merchant context and spending categories on top of that. But enrichment alone, without validation and verification of data, still breaks production workflows at scale. Both layers together determine whether financial automation holds up.
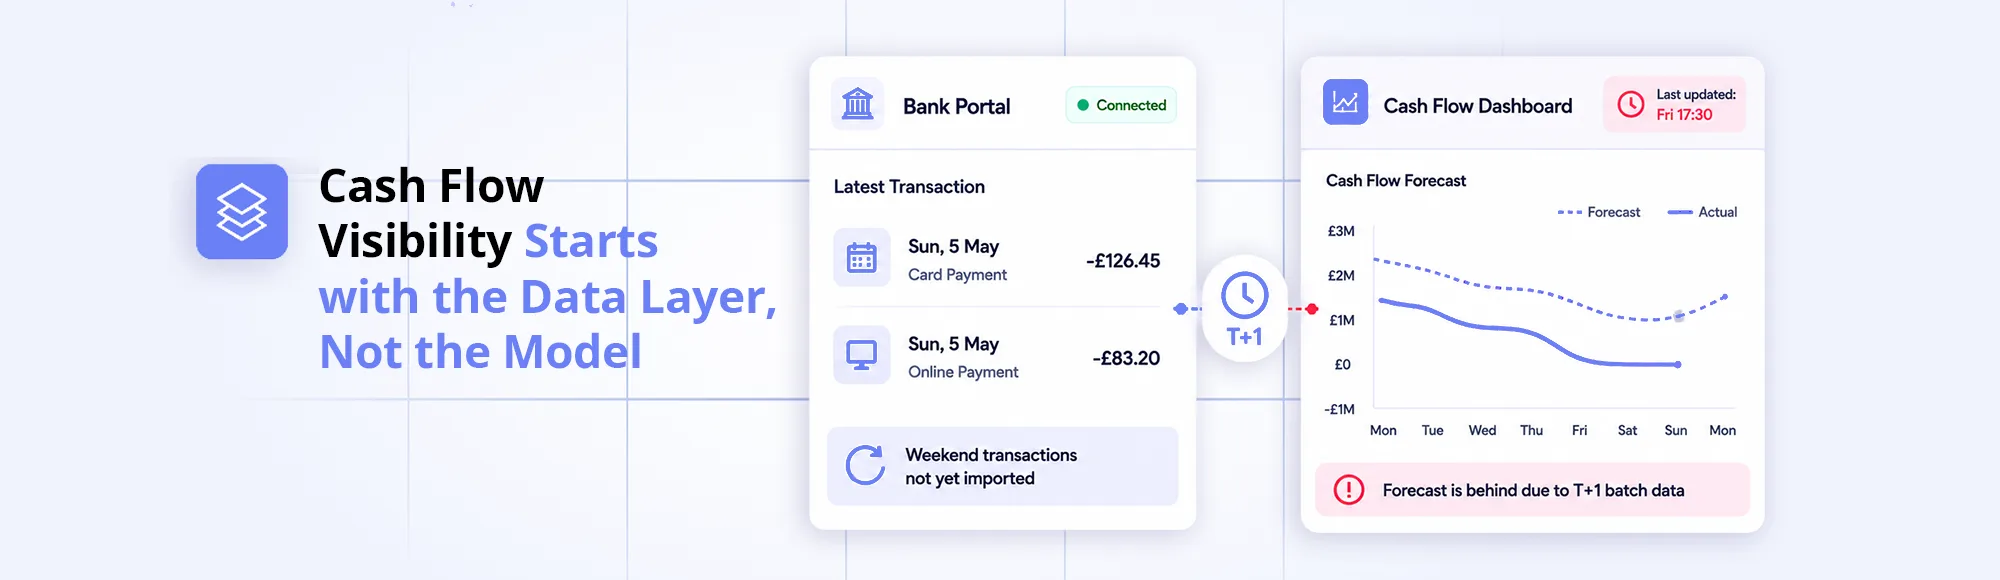
Why Most Businesses Still Struggle to Improve Cash Flow Visibility
Cash flow visibility fails when the data feeding it is delayed. A forecast built on yesterday’s bank statement is a reconstruction, not a real forecast. This blog covers why finance teams struggle to improve cash flow visibility, why forecast accuracy depends on connected financial data, and what changes when bank transaction data arrives near settlement.
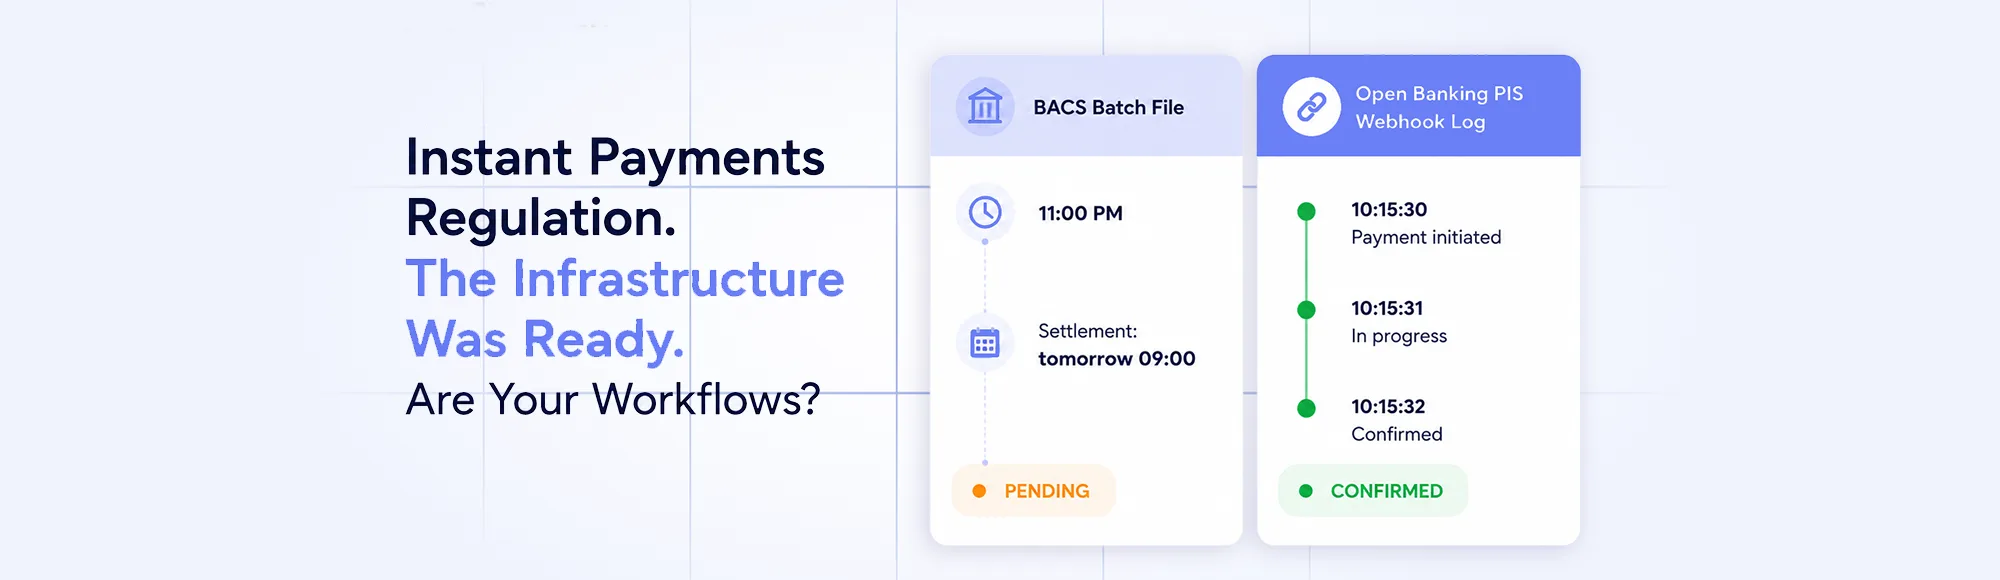
Why Instant Payments Regulation Is Changing More Than Just Speed
Instant payments regulation is not just a compliance update. It is changing the operational assumptions payment platforms, billing systems, and finance teams have built their workflows on. This blog covers what the EU Instant Payments Regulation means operationally, how the UK Faster Payments ecosystem compares, and what it means for platform payment infrastructure in 2026.
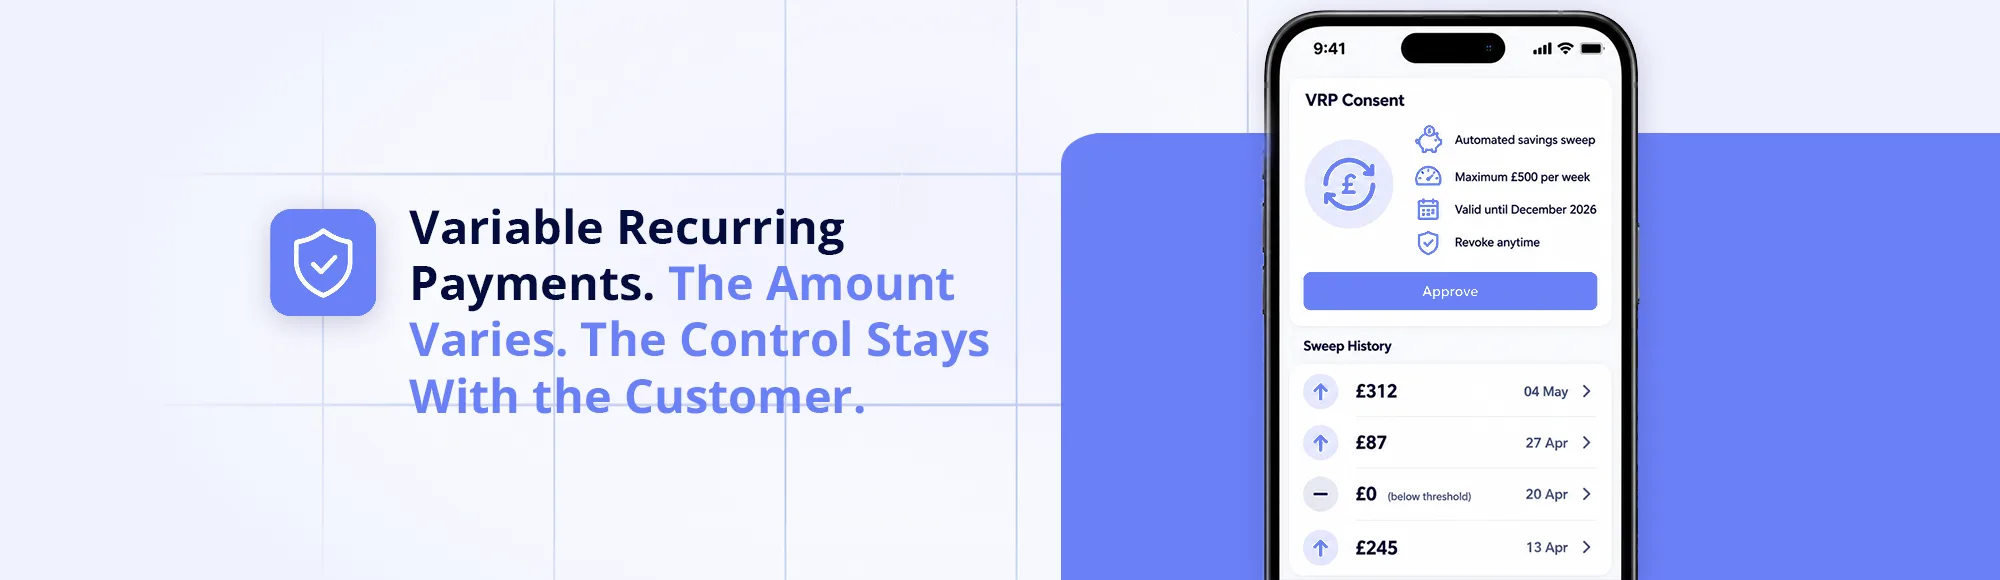
Variable Recurring Payments Open Banking Examples That Show Where Payments Are Heading
Variable recurring payments are described as a technical upgrade to Direct Debit. That undersells them. VRPs change who controls recurring payment amounts – shifting control from the business to the customer. This blog covers real Open Banking VRP examples across savings, utilities, lending, and subscriptions, and why VRPs matter for financial inclusion beyond flexible billing.
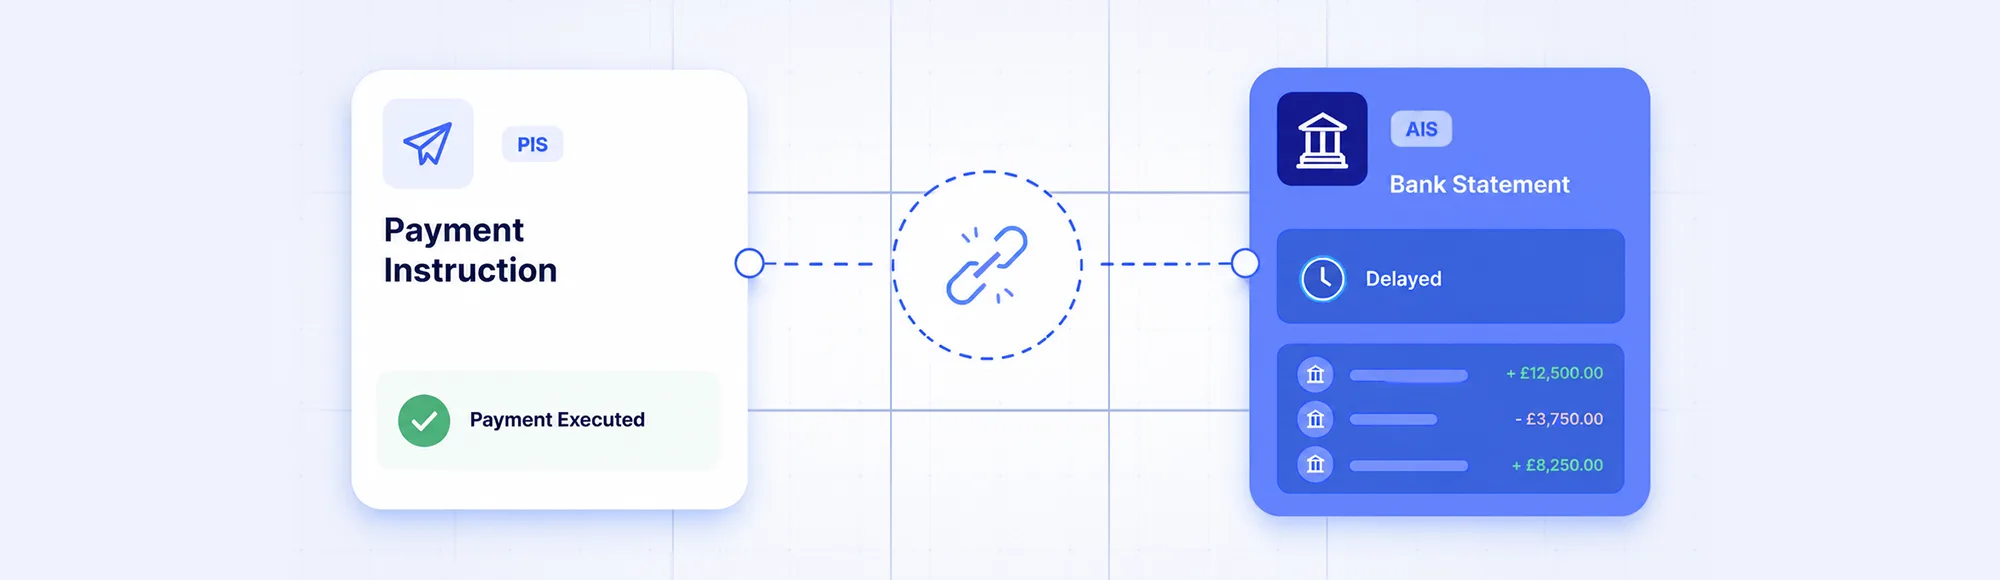
Payment API Integration: Why Payments and Data Must Work Together
Payment API integration works in the sandbox. It breaks in production when payments execute but financial data does not follow. Reconciliation fails. Cash position drifts. This blog covers why payment API integration depends on open banking data sharing to work reliably – and what the connected payments-plus-data workflow actually looks like for B2B platform teams.
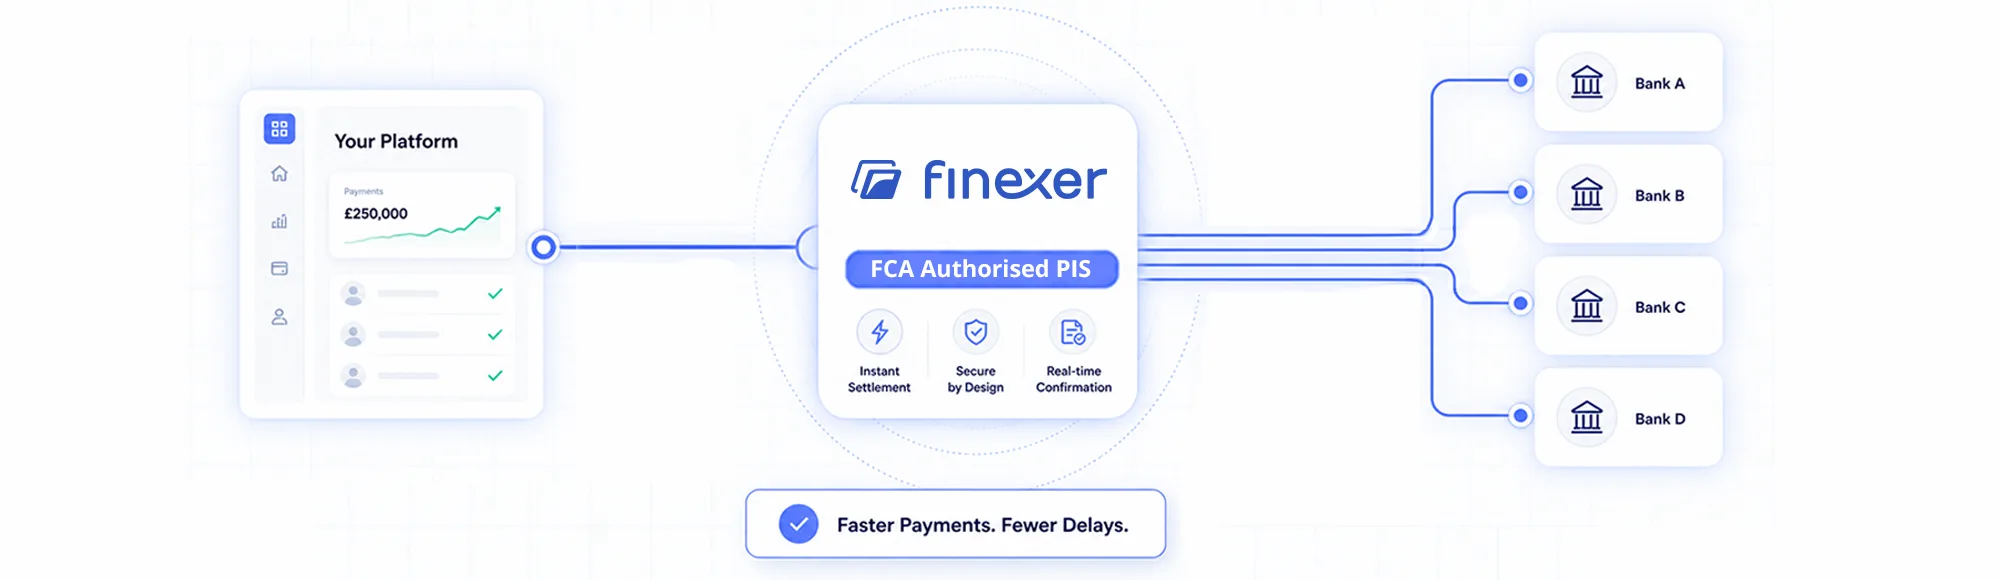
Proven API Banking Platform Guide: What Actually Matters in Production
Most API banking platform evaluations start with endpoints and feature documentation. They should always start with production reliability instead. This blog covers what actually determines which open banking platform has the best API for UK product teams, and compares the top five UK providers on real criteria that matter once integration moves beyond the sandbox.
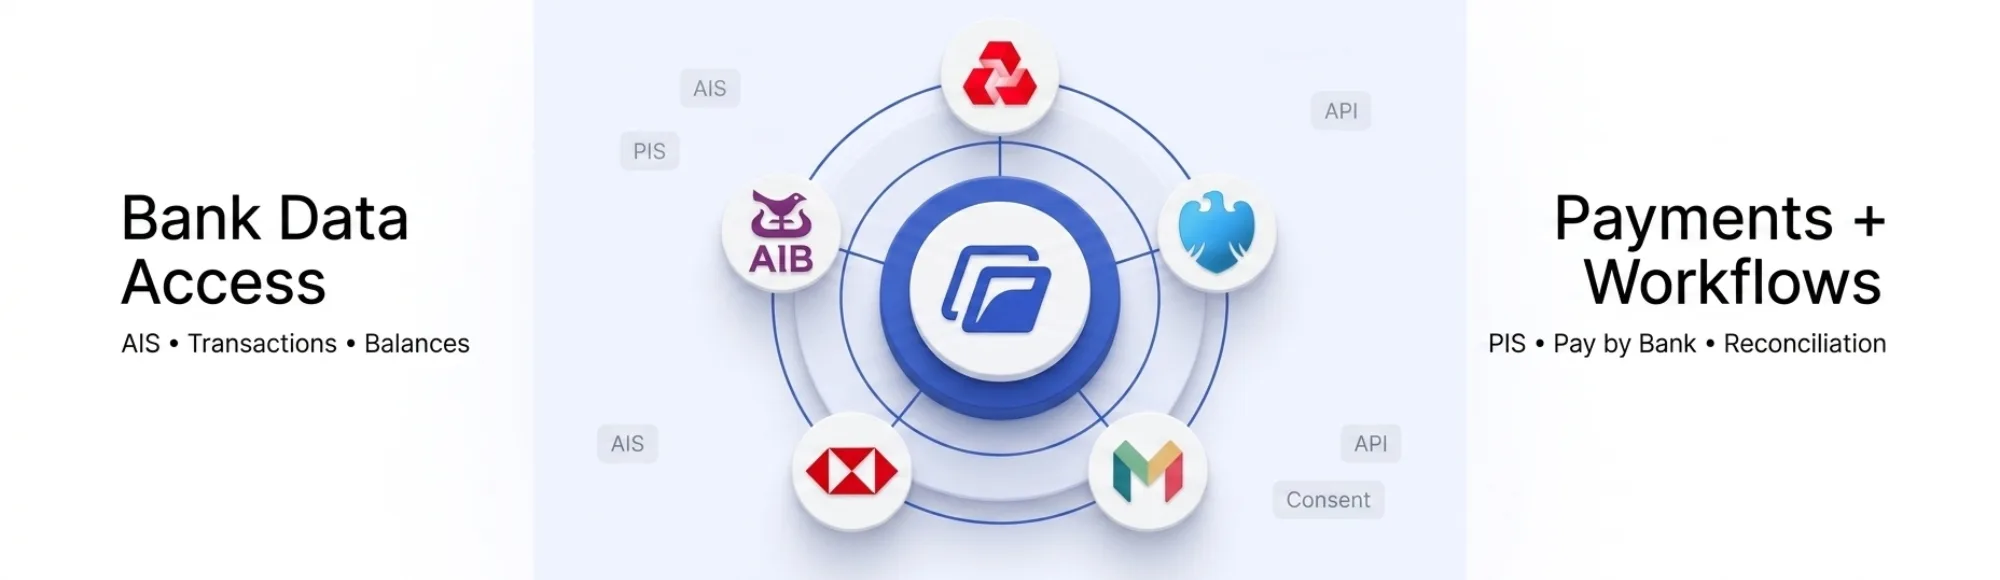
Finexer Open Banking: Infrastructure for Reliable Financial Workflows
UK-only. FCA-authorised. Bank data and payments in one integration. Open Banking infrastructure for accounting, Lawtech, EPOS, and billing platforms. Contact Now Finexer Open Banking provides API-based access to bank transaction data and payment initiation through Open Banking infrastructure. It enables platforms to retrieve structured financial data, initiate account-to-account payments, and build reliable financial workflows using…
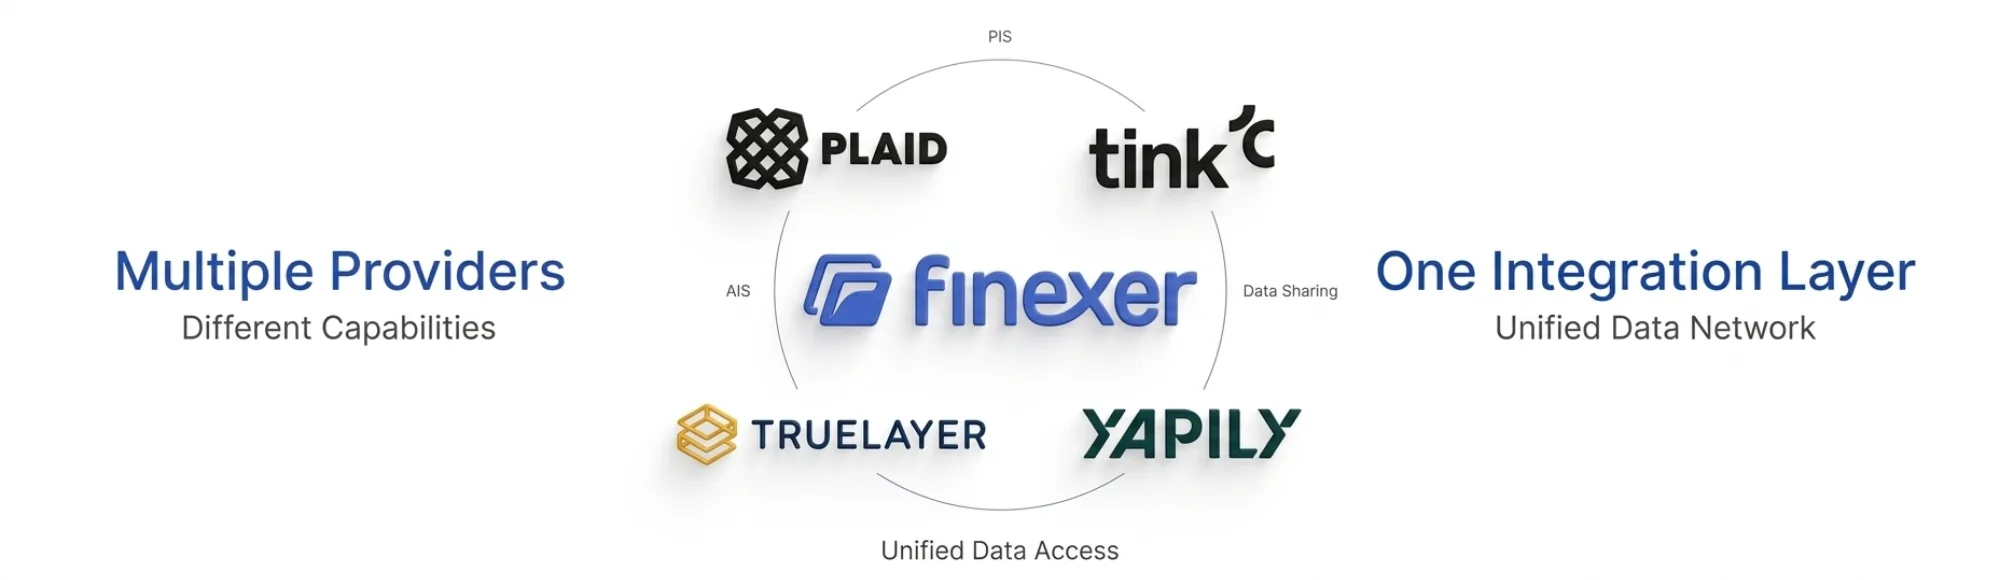
Open Banking Data Networks: 5 Best Providers for Secure Data Sharing in Fintech
Open banking data networks give fintech platforms consented access to bank transaction data across multiple institutions through a single API. Choosing the right provider determines data quality, UK bank coverage, and whether open banking data sharing supports your payment workflows. This blog compares five leading providers to help UK fintech platforms make the right decision.
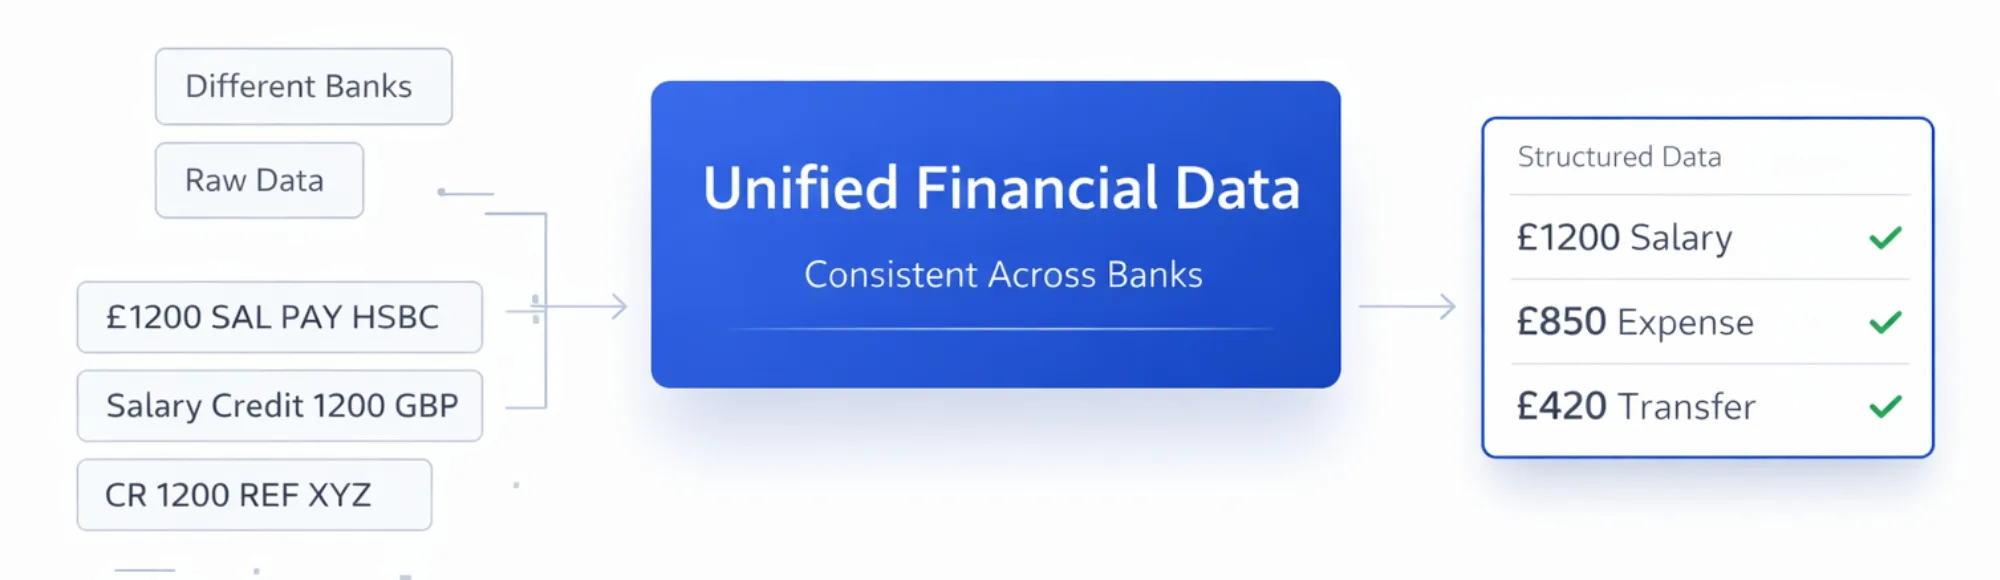
Financial Data Connectivity Across Institutions: Best Fintech Platforms for Reliable Integration
Financial data connectivity across institutions is how UK fintech platforms access, standardise, and use bank transaction data through a single API layer. Most platforms only find the real gap after go-live – when data arrives inconsistently, enrichment is missing, and financial data providers end up stitched together. This blog covers exactly what reliable connectivity requires.
API-Driven Fintech Infrastructure: Best Platforms for Fast, Secure Integration
API-driven fintech infrastructure is not a feature decision. It is a production decision. The wrong infrastructure provider means months of integration work, data quality problems, and real compliance gaps that only surface after go-live. This blog covers what UK platforms need from fintech infrastructure, where providers fall short, and how to evaluate the right fit.
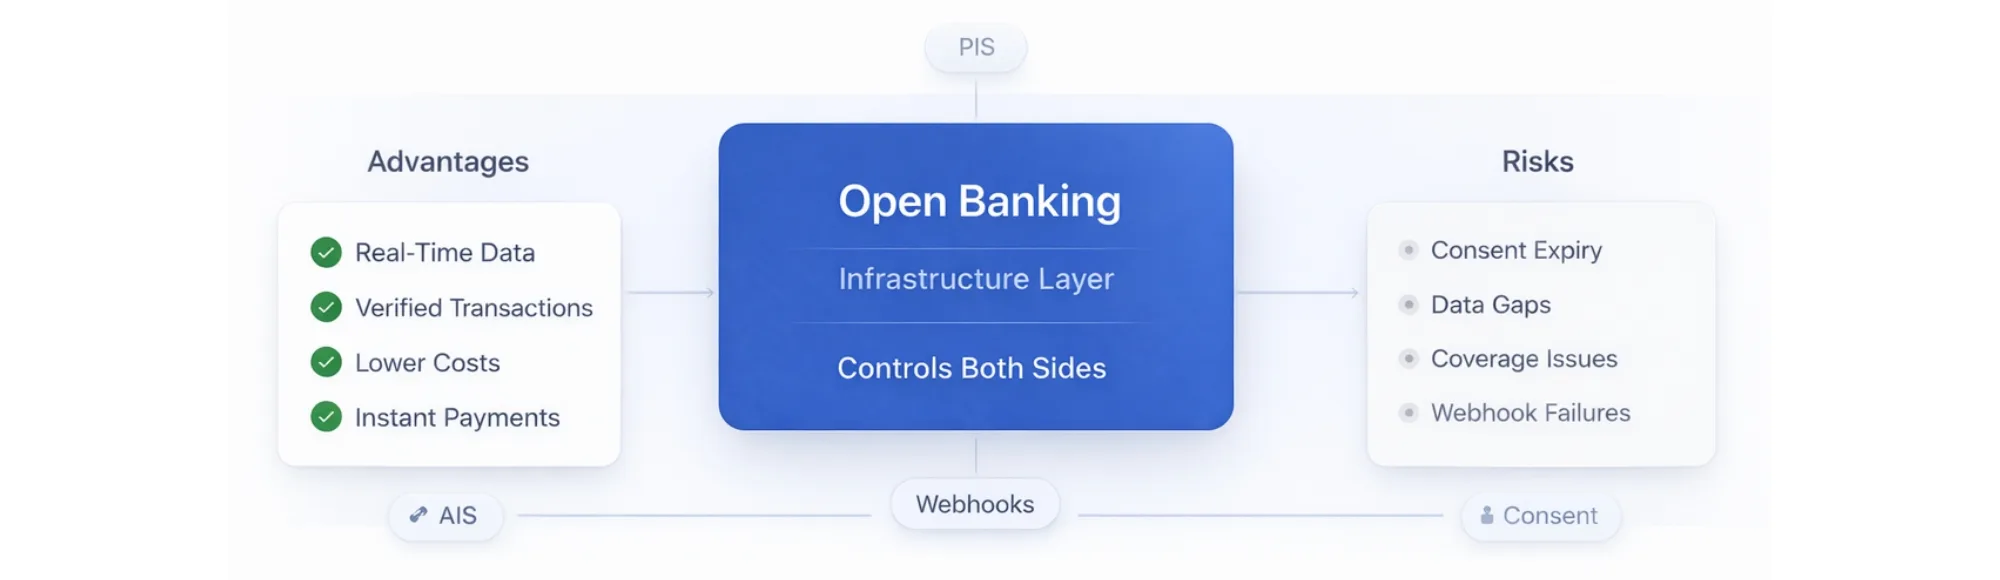
Open Banking Advantages: What Platforms Gain (and the Risks They Must Solve)
Open banking advantages are real – lower payment costs, bank-verified data, and faster financial workflows. But the risks of open banking are equally real for platforms building on it. Consent expiry, coverage gaps, and data inconsistency are operational problems, not theoretical ones. This blog covers both sides from a platform perspective, not a consumer one.
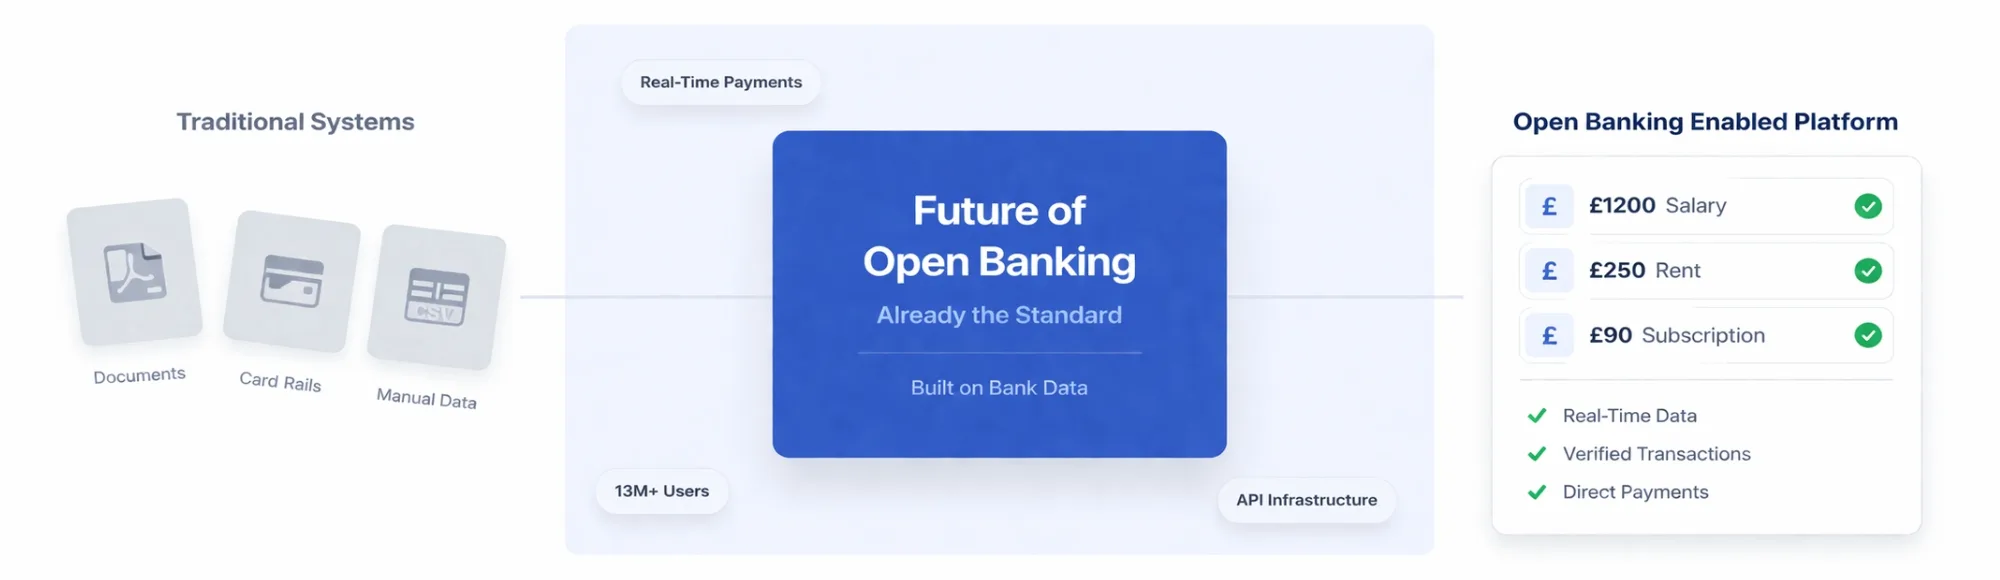
Future of Open Banking: Why It’s No Longer Optional for Financial Platforms
The future of open banking is not a distant roadmap item. It is live, already delivering measurable economic value, and actively separating platforms that have built on it from those that have not. This blog covers whether open banking is mandatory, what the economic data shows, and why the infrastructure shift decision cannot be deferred.
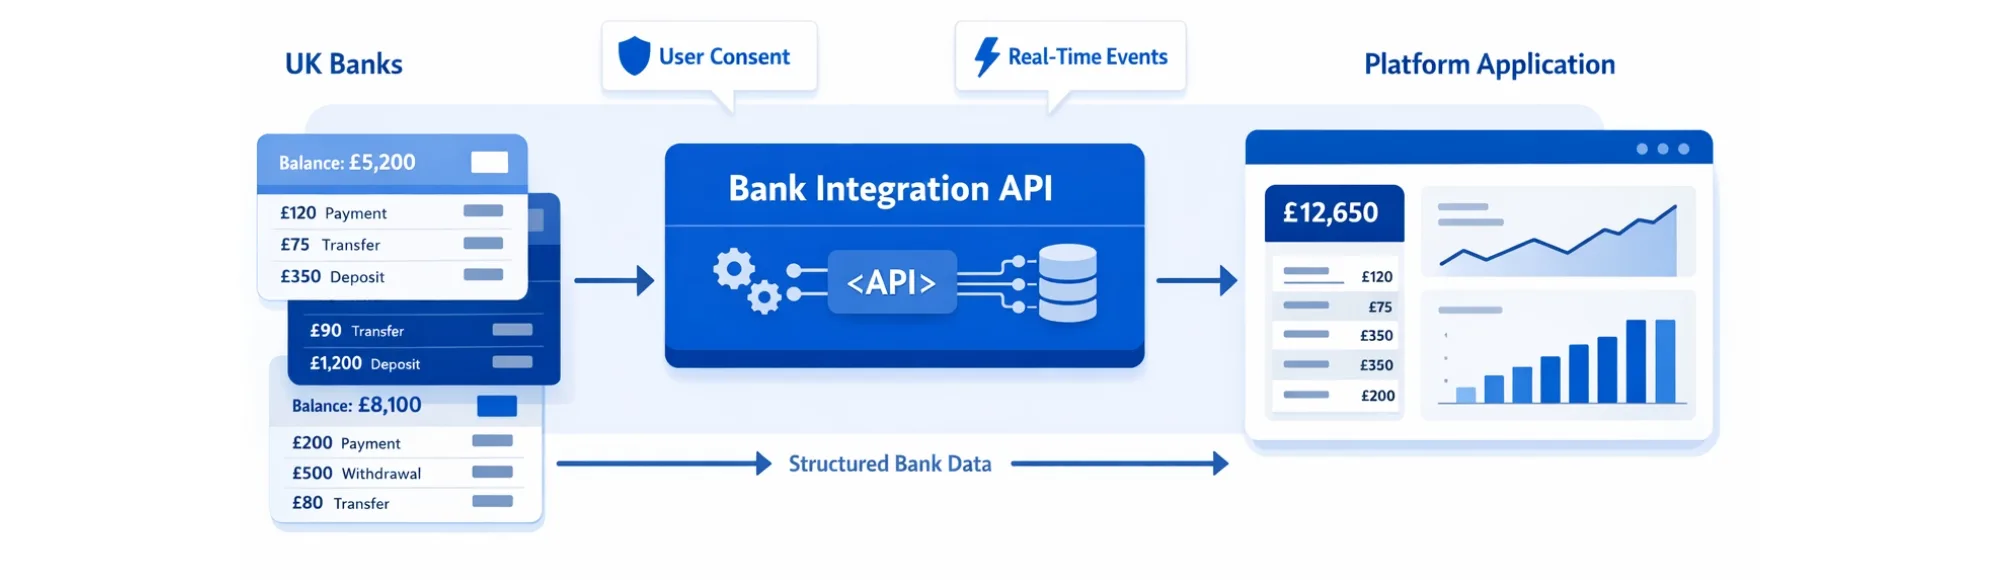
Why Platforms Need a Reliable Bank Integration API for Financial Data Access
Need reliable bank data infrastructure for your platform? Finexer gives UK platforms FCA-authorised AIS and PIS access – structured, real-time, API-ready. Contact Now Every platform I work with that handles financial data eventually reaches the same architectural decision point. The product needs bank transaction data – for reconciliation, verification, affordability assessment, or payment confirmation. The…
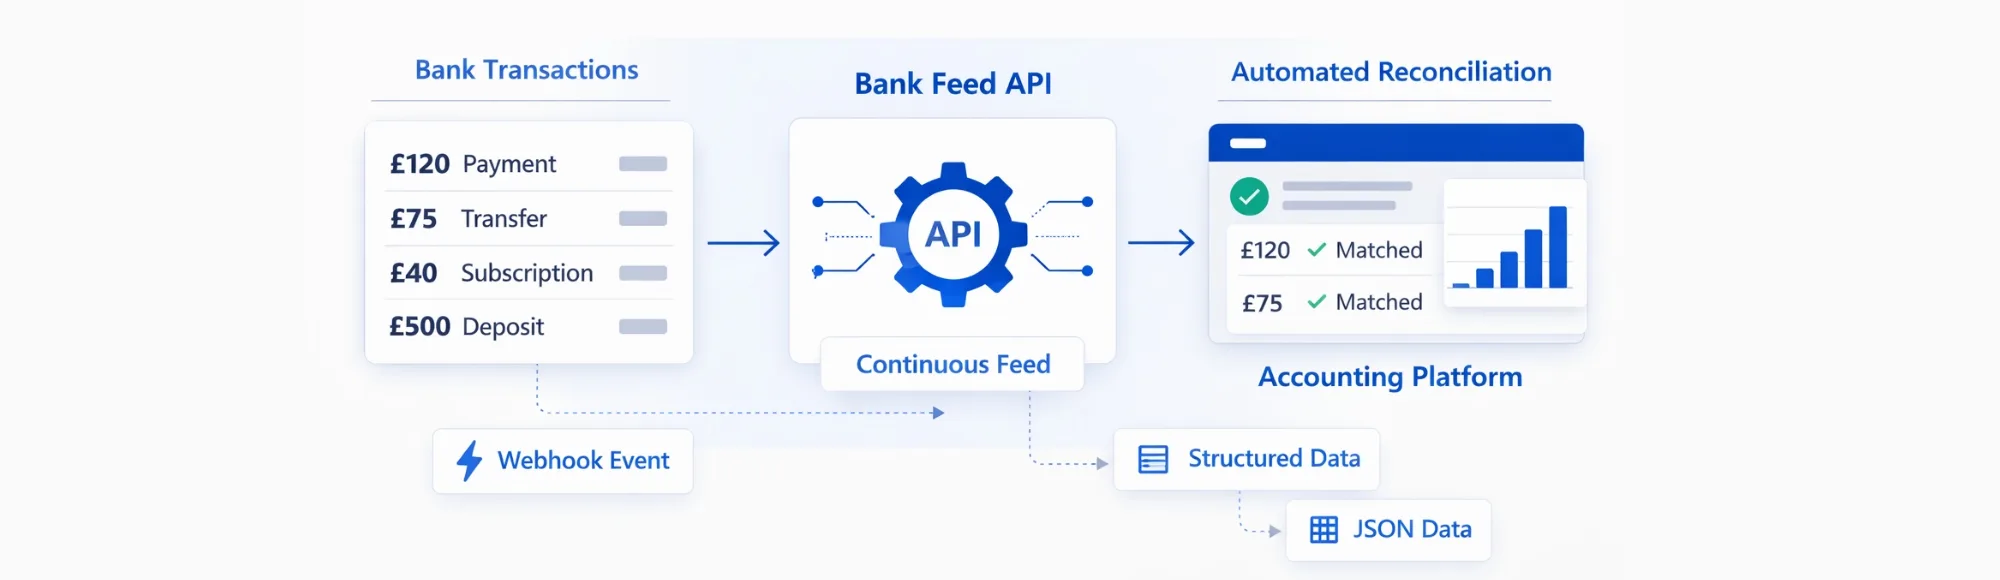
Why Accounting Platforms Need a Reliable API for Bank Feed Automation
Manual bank statement uploads and CSV imports create reconciliation delays that scale with transaction volume. This blog explains why accounting platforms need a reliable api for bank feed automation – covering data continuity, reconciliation accuracy, and how Finexer API provides structured bank transaction feeds for UK accounting, bookkeeping, and ERP platforms.
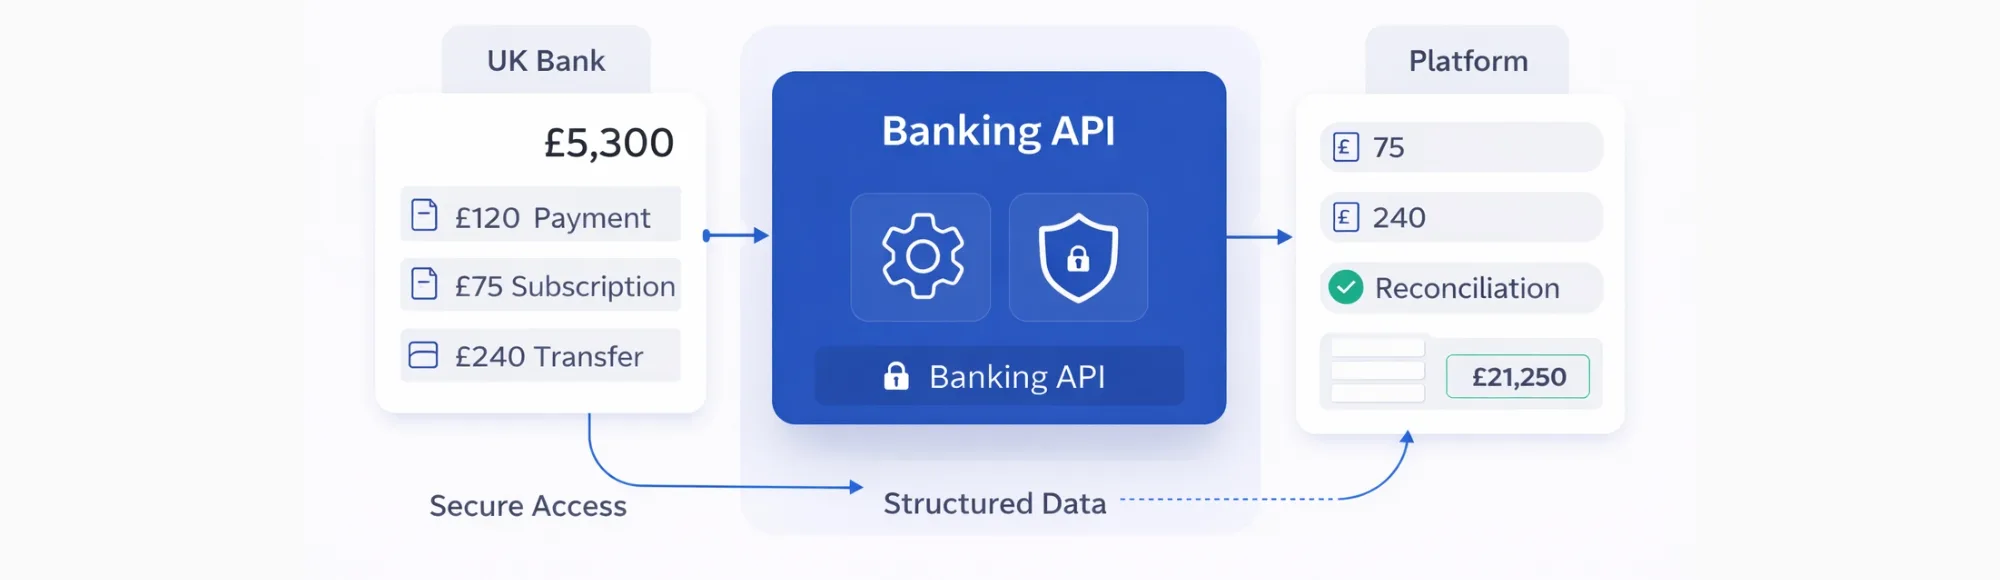
How UK Platforms Connect to a Bank With API Infrastructure
Most platforms still collect bank data through CSV exports and manual uploads. This blog explains how connecting to a bank with API infrastructure changes that – covering how banking APIs work, what platforms can build on top of them, and how Finexer provides unified bank connectivity for UK accounting, LawTech, EPOS, payroll, PropTech, and utility…

Proven B2B Data Enrichment Tools for UK Financial Platforms
Most b2b data enrichment tools serve sales and CRM teams. UK financial platforms need merchant data enrichment that identifies suppliers and business counterparties from verified bank data. This blog explains what to evaluate and how Finexer’s infrastructure enables it.
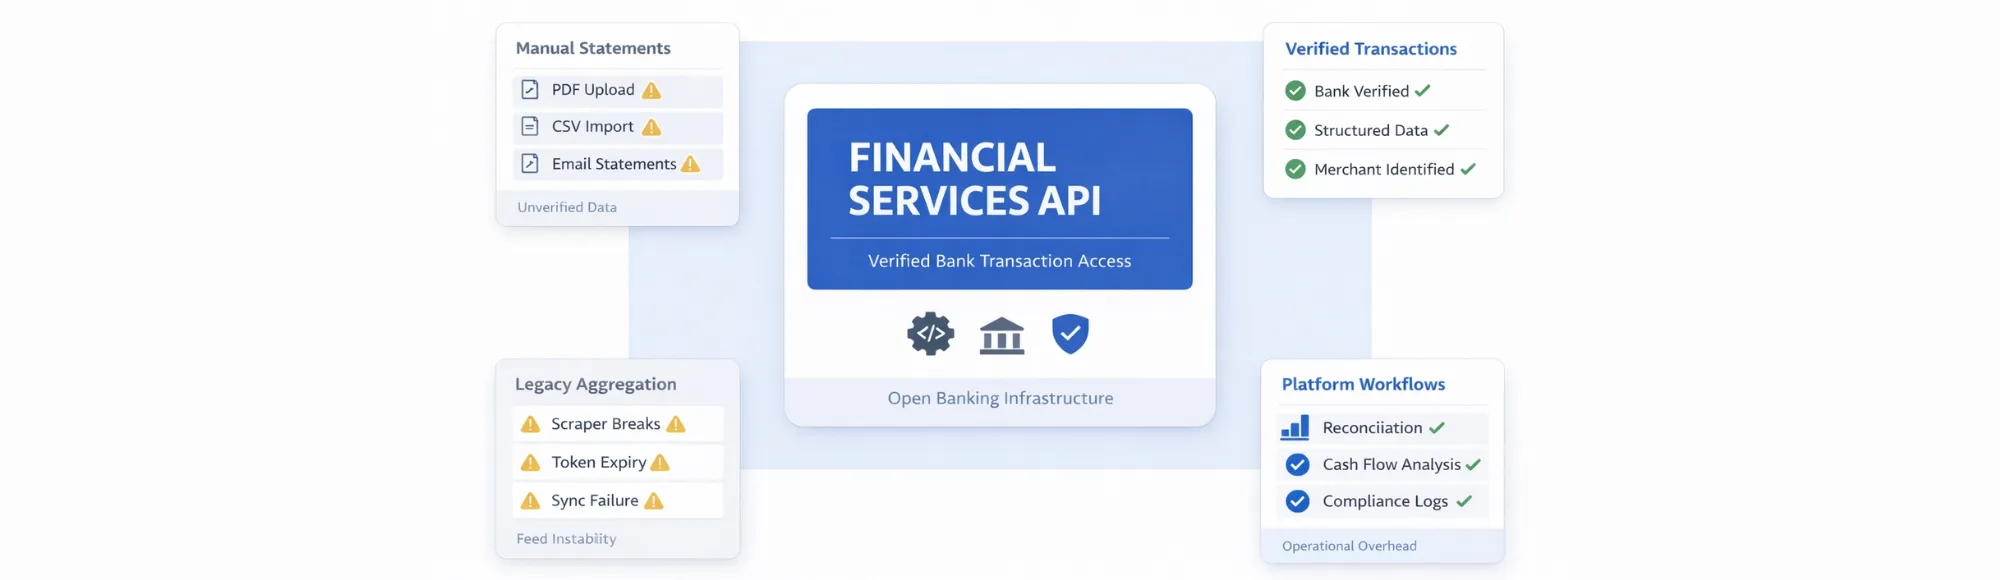
Verified Financial Services API for UK Regulated Platforms
Verified financial services API infrastructure for UK fintech platforms. Access bank transaction data through Open Banking APIs enabling automated workflows with verified, structured financial records.
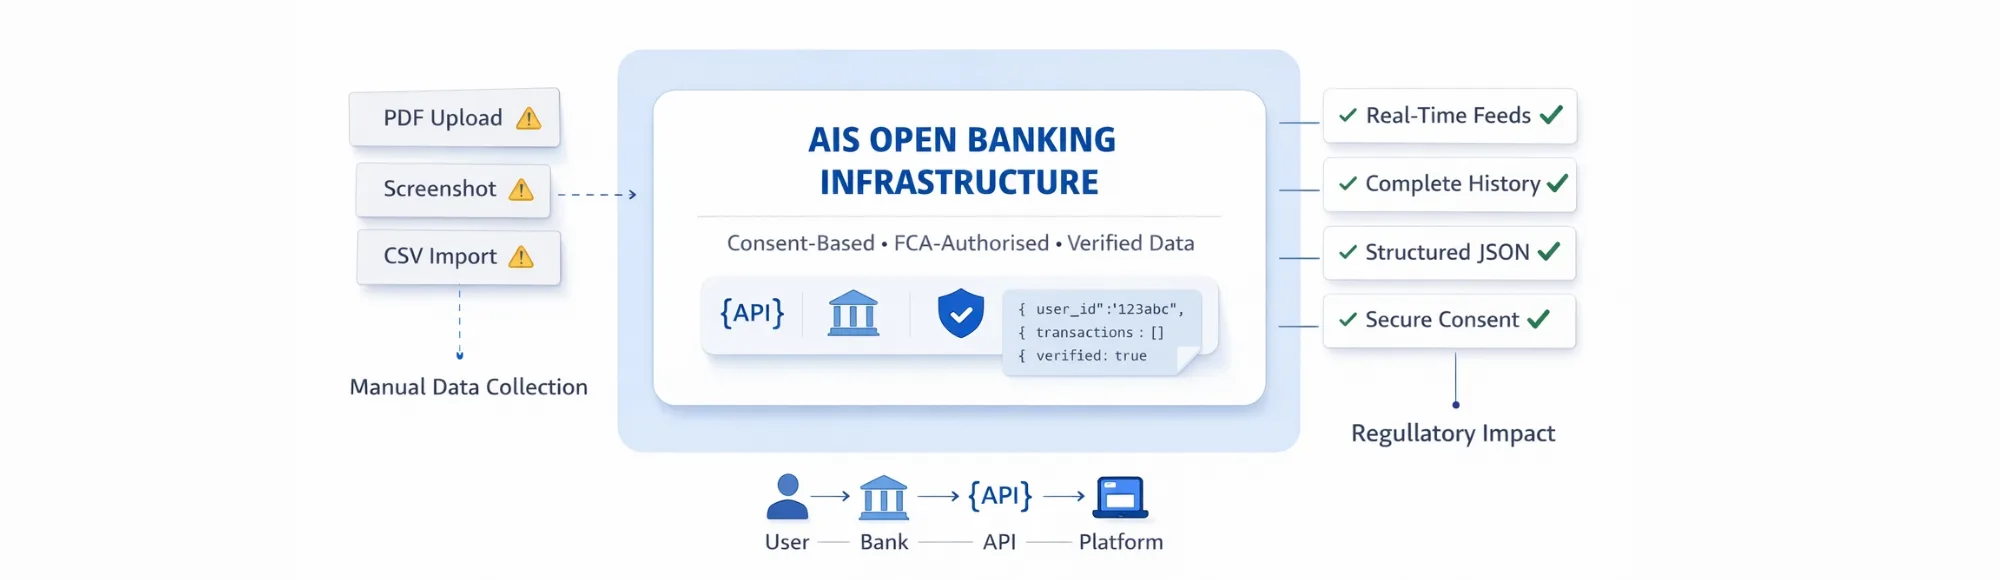
Secure AIS Open Banking Infrastructure for UK Regulated Platforms
AIS Open Banking infrastructure enables UK platforms to access verified bank transaction data via FCA-authorised APIs. Secure, consent-based financial data access for accounting, LawTech, and lending platforms.

Best Data Enrichment Tools for UK Fintech & Accounting Scaleups (2026 Guide)
Compare the best data enrichment tools for UK fintech and accounting scaleups. Evaluate transaction enrichment, merchant identification, and Open Banking integration capabilities from top providers.
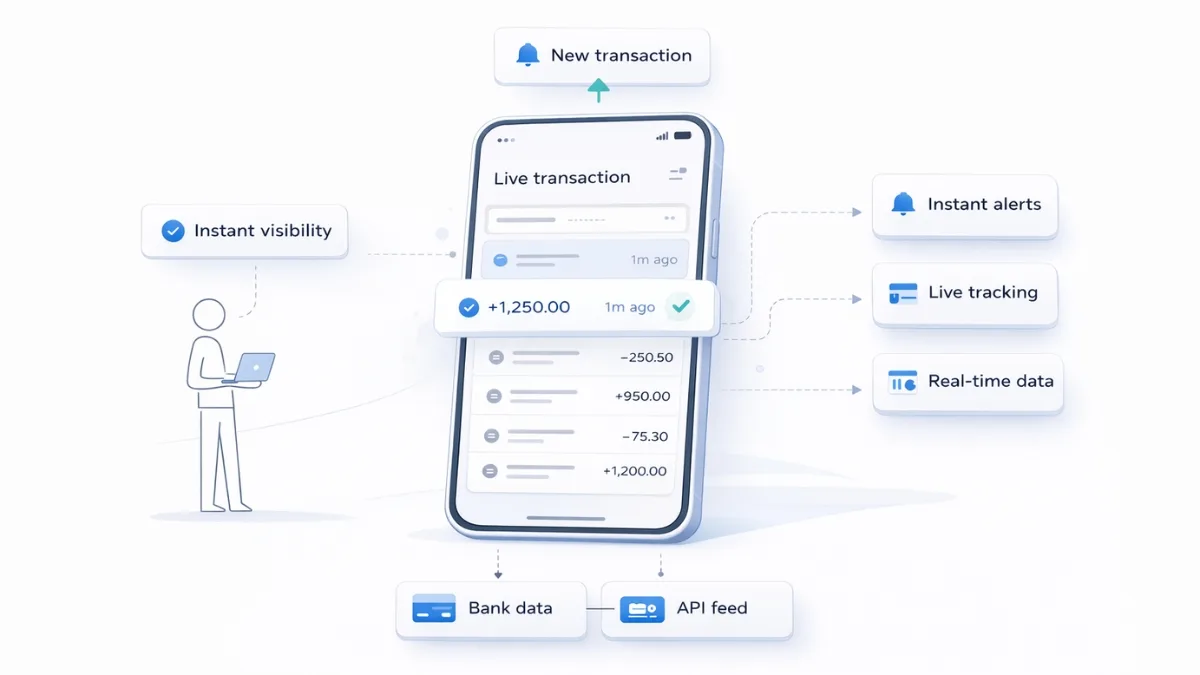
Automated Real-Time Transaction Monitoring for Fintech Platforms
Real time transaction monitoring enables UK fintech platforms to access instant bank transaction notifications. Platforms integrate open banking APIs for live financial visibility supporting payment confirmation, compliance workflows, and automated monitoring without delayed batch updates.
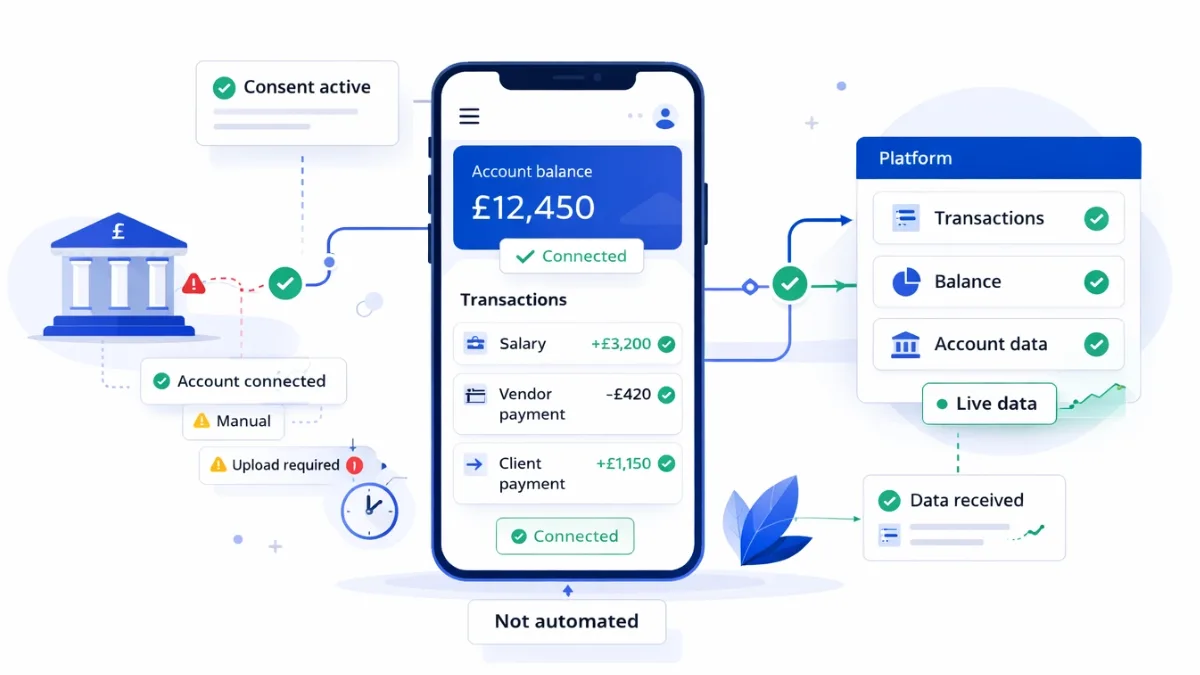
Open Banking AIS: How to Access Financial Data Reliably
Open banking AIS infrastructure enables UK platforms to access bank account data reliably. Platforms evaluate FCA authorisation, bank coverage, connection reliability, and consent management when choosing AIS banking providers.
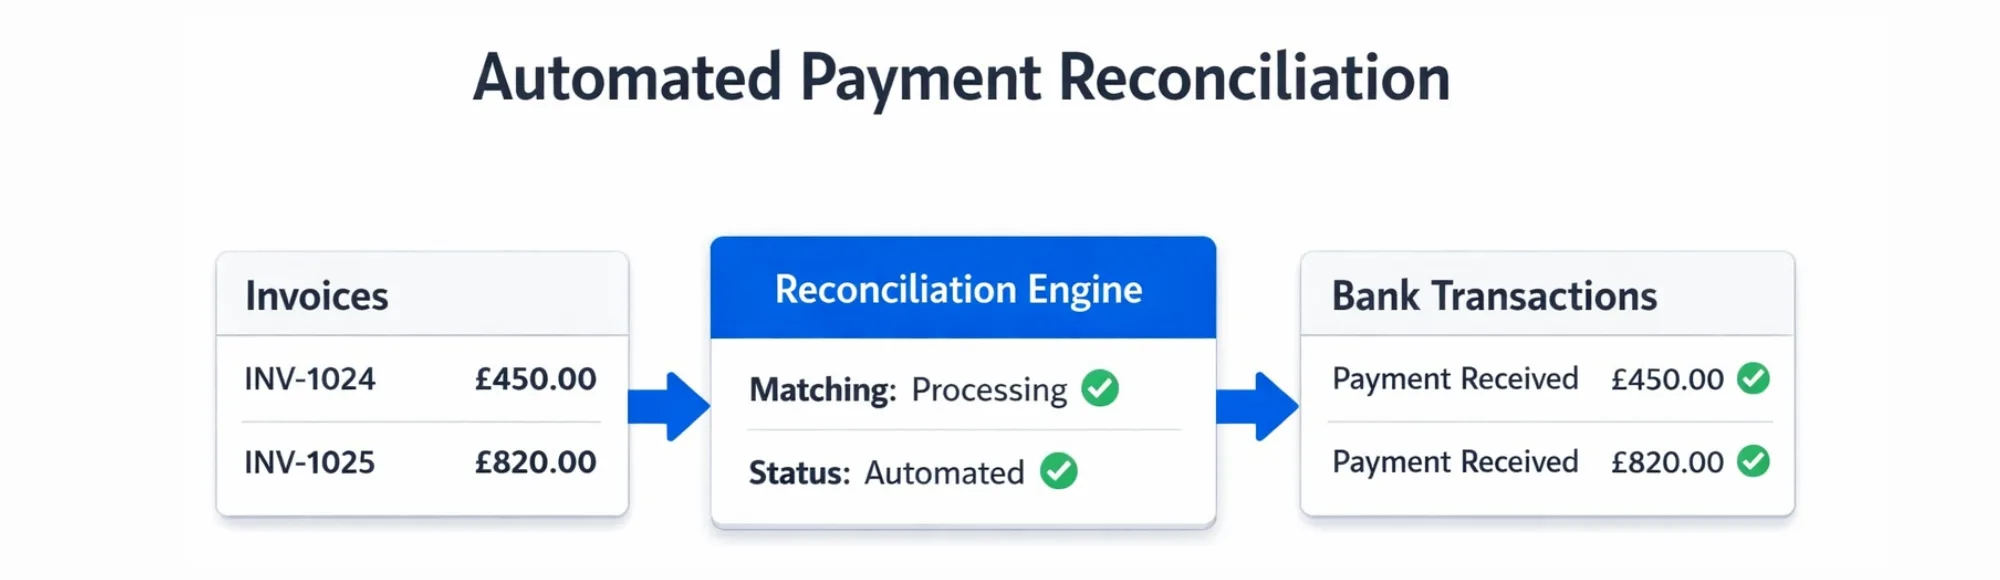
Automated Payment Reconciliation for UK Accounting Platforms
Automated payment reconciliation requires real-time bank transaction data. UK accounting platforms use Finexer’s FCA-authorised Open Banking infrastructure to access structured feeds enabling automated matching without manual CSV uploads.
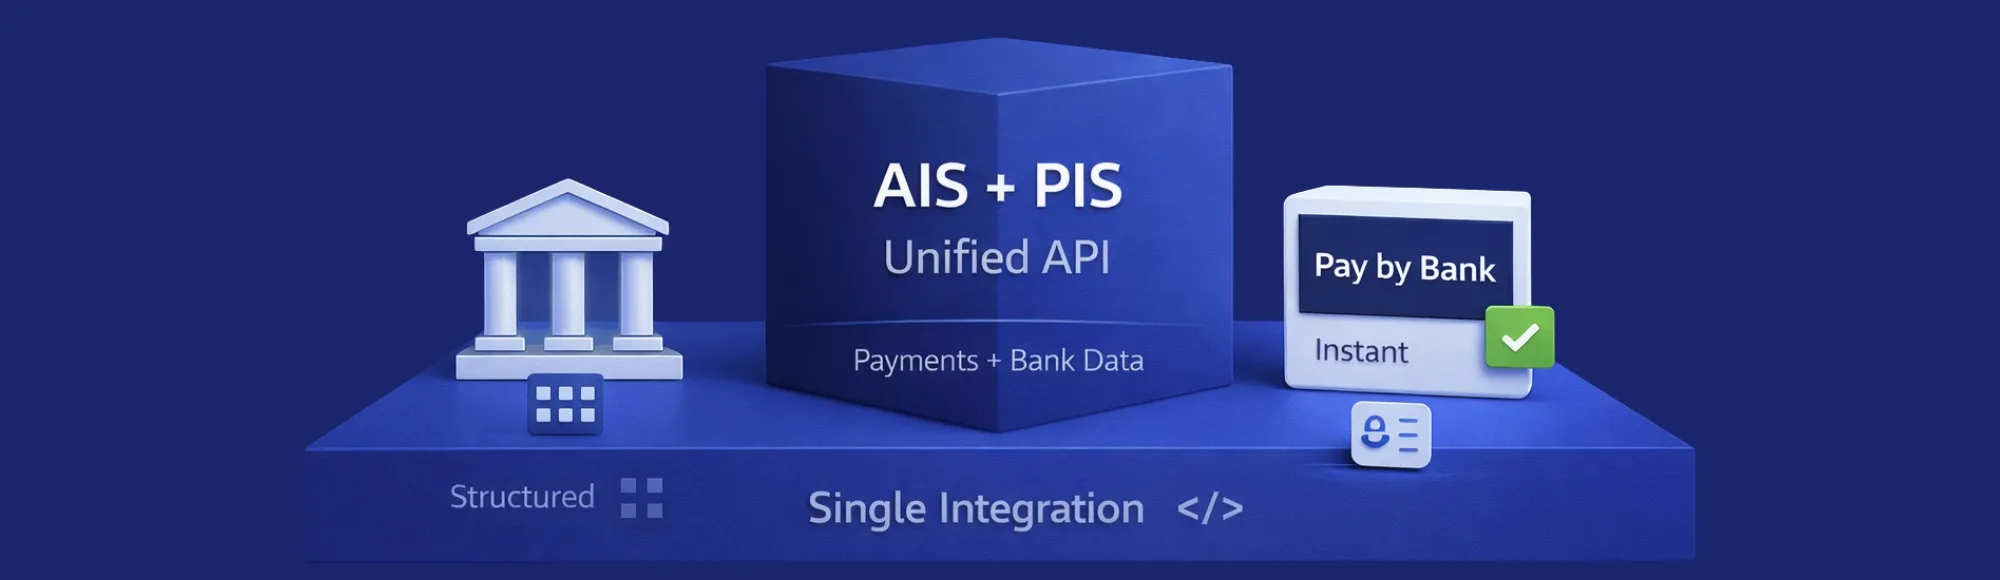
API Financial Services for Platforms Building Payments & Open Banking
API financial services with AIS+PIS in one integration. Compare Open Banking providers for UK platforms. Evaluate payments and bank data infrastructure now.
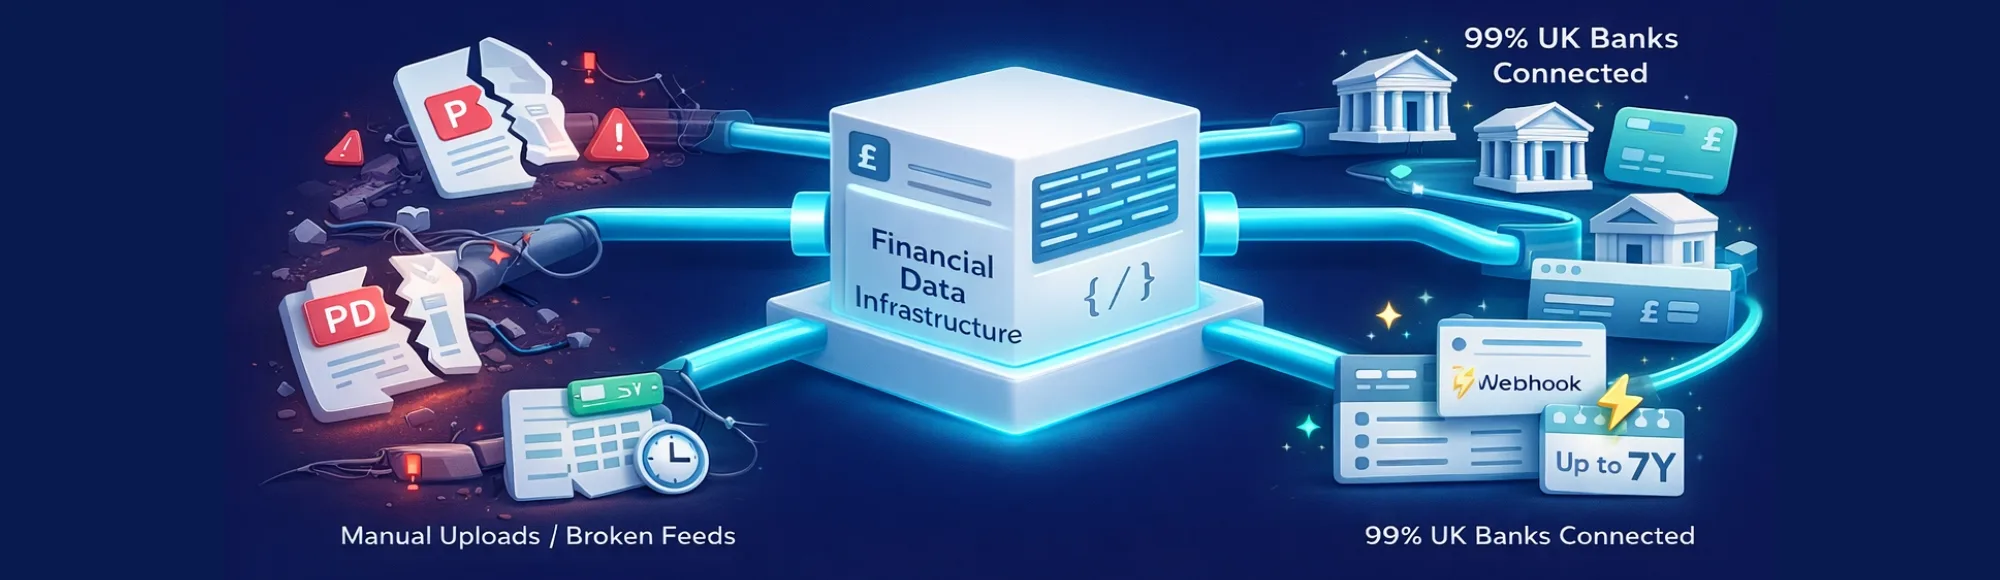
Financial Data Aggregation for Platforms: What Actually Matters
Broken feeds and manual uploads hold your product back. Finexer’s financial data aggregation delivers structured UK bank data via Open Banking APIs. Book a demo.
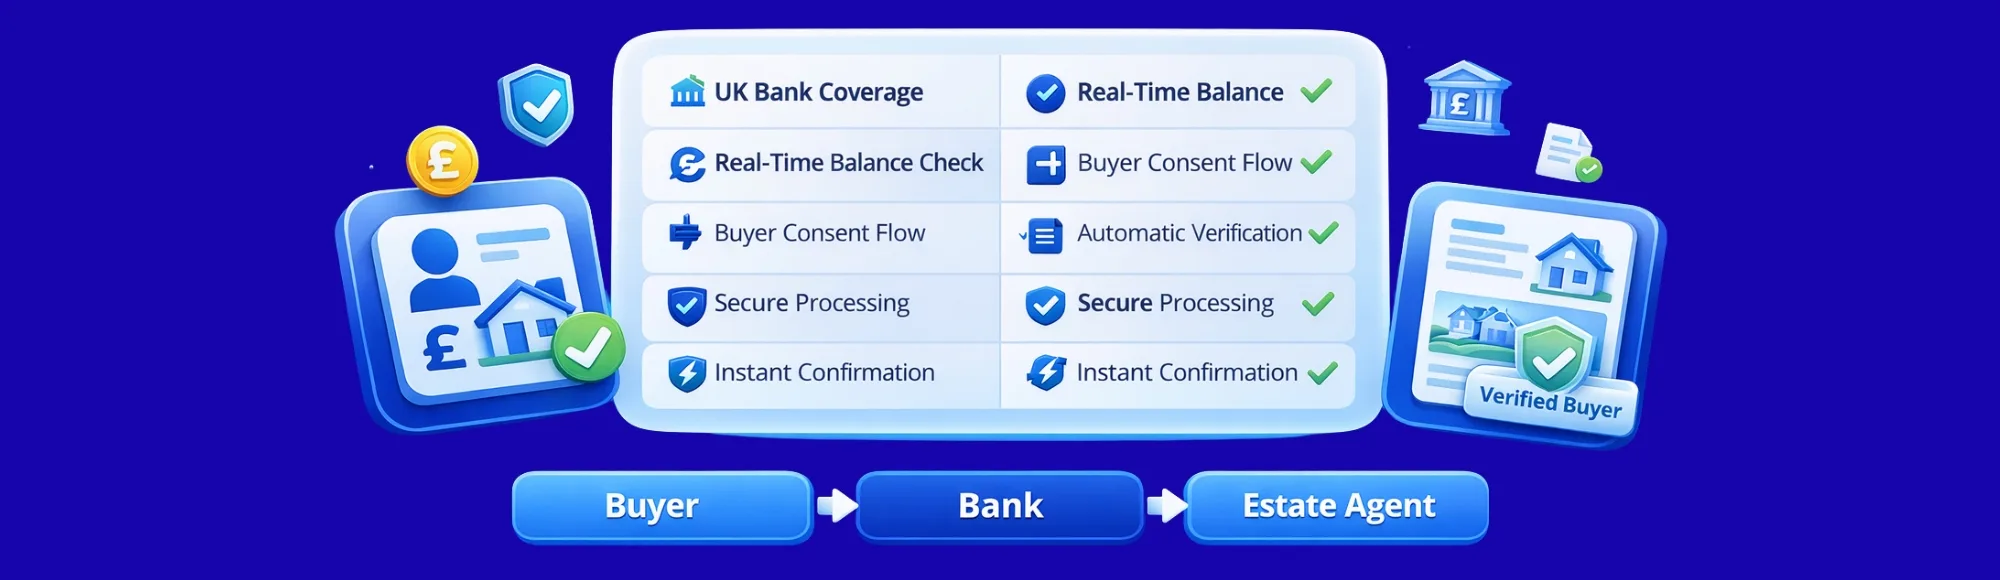
Real Estate Bank Verification: How Estate Agents Instantly Verify Proof of Funds & Bank Accounts Using Open Banking
Real estate bank verification for UK estate agents. Verify buyer funds instantly, eliminate statement delays & close deals faster with open banking technology.