Finexer Open Banking Blogs
AML Screening and Monitoring: The Real Difference (UK)
AML screening and monitoring get treated as one task, but MLR 2017 requires both as distinct obligations: first, due diligence at onboarding, then continuous transaction monitoring for the life of the relationship. This guide separates the AML screening process from ongoing monitoring and shows where UK platforms most often let the monitoring obligation quietly lapse.
What Is Right to Rent? UK Requirements and Digital Checks
Learn what is right to rent, the legal requirements for landlords in England, and how right to rent checks fit into modern tenant onboarding. Compare certified IDSPs with complementary verification workflows and see where Finexer supports lettings platforms without replacing statutory Right to Rent checks.
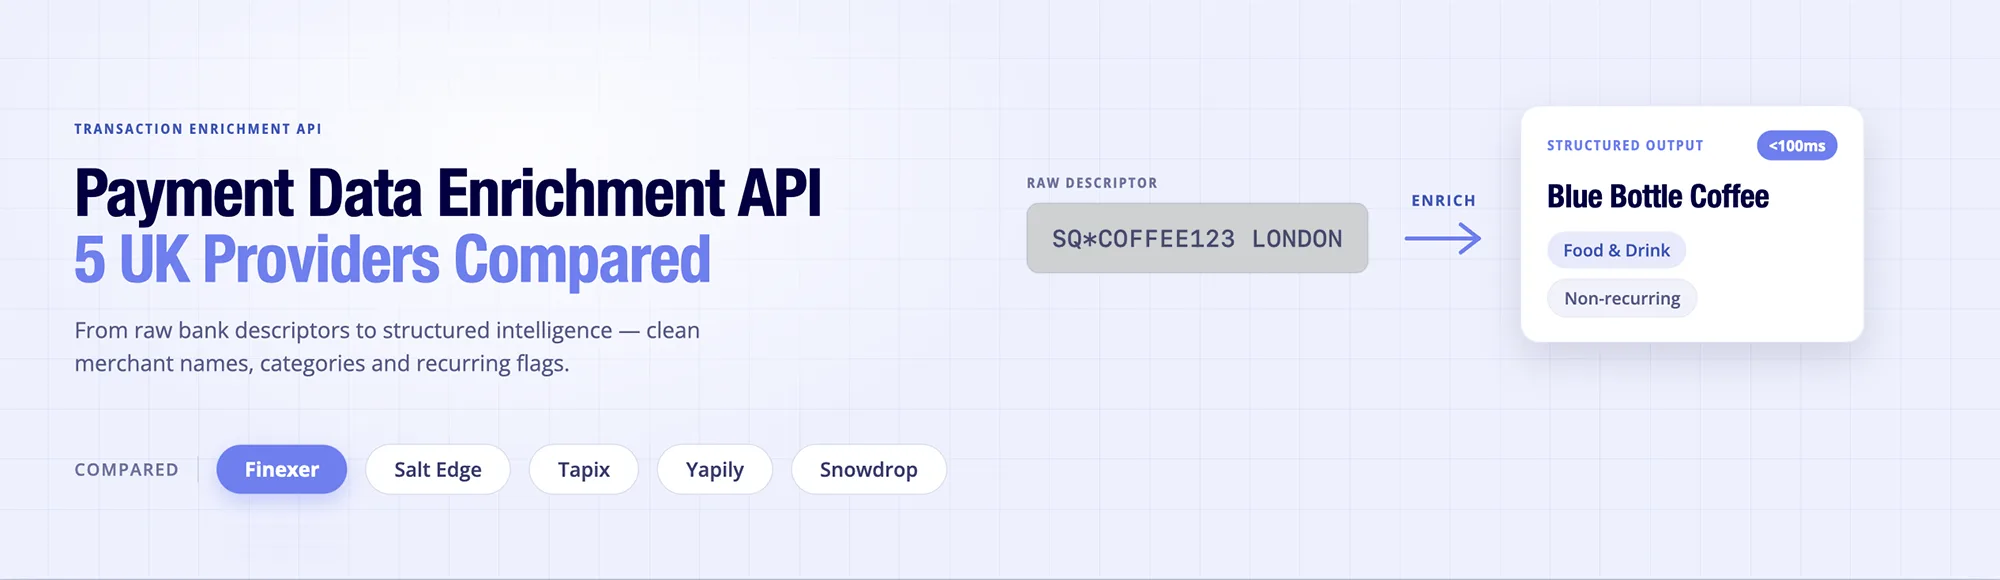
Payment Data Enrichment API: 5 UK Providers Compared
Your accounting platform receives 50,000 bank transactions daily. However, your bank descriptions arrive as cryptic codes that are hard to decipher. Your finance team can’t tell if it’s office supplies, cloud services, or equipment. They spend hours manually categorising transactions. Reconciliation slows down. Support tickets increase because users see unclear merchant names in their feeds. […]
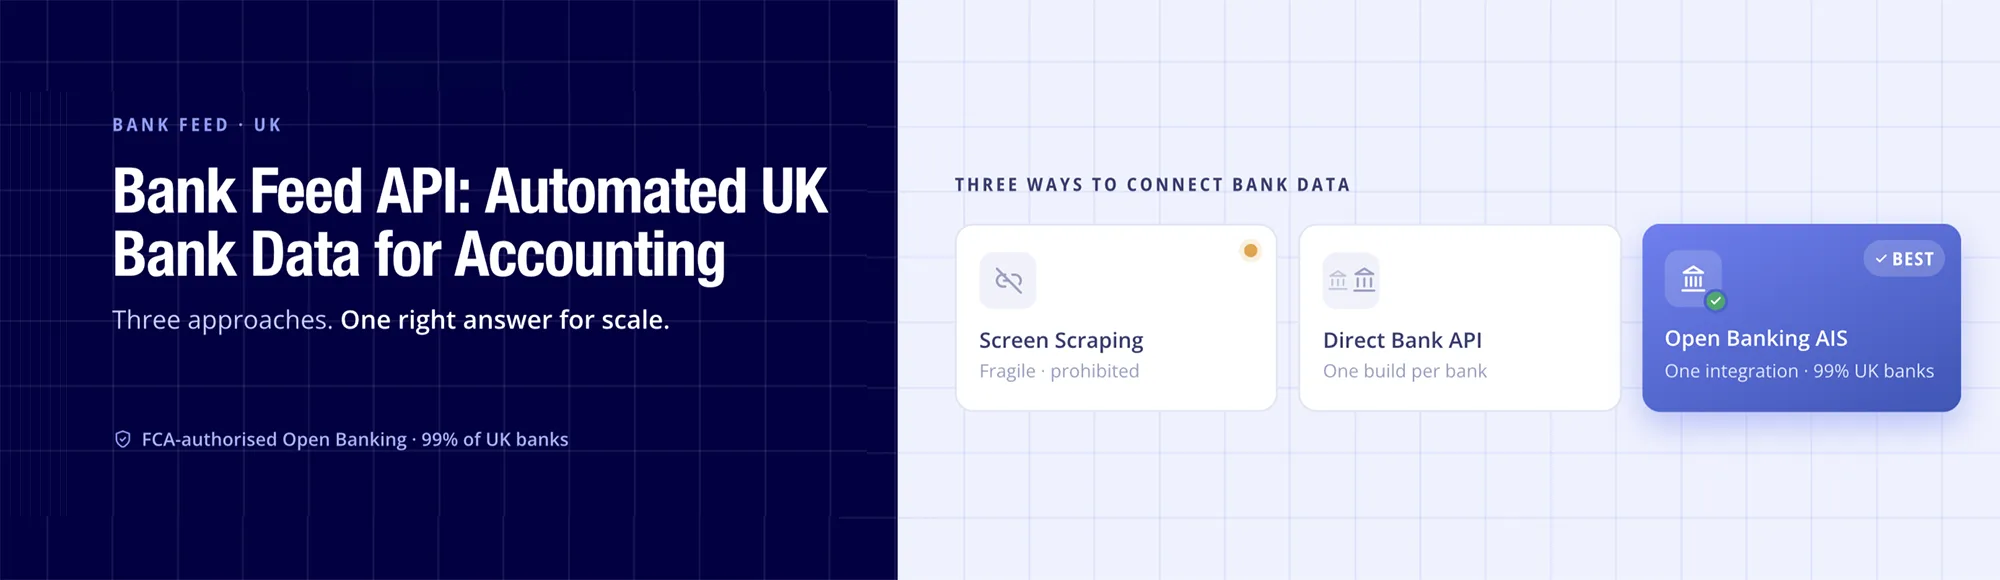
Bank Feed API: Automated UK Bank Data for Accounting
Bank feed solutions for accounting platforms- real-time data syncing from UK banks without manual CSV uploads. Learn how screen-scraping differs from Open Banking PIS, refresh frequency, and build vs buy decisions for accounting SaaS.
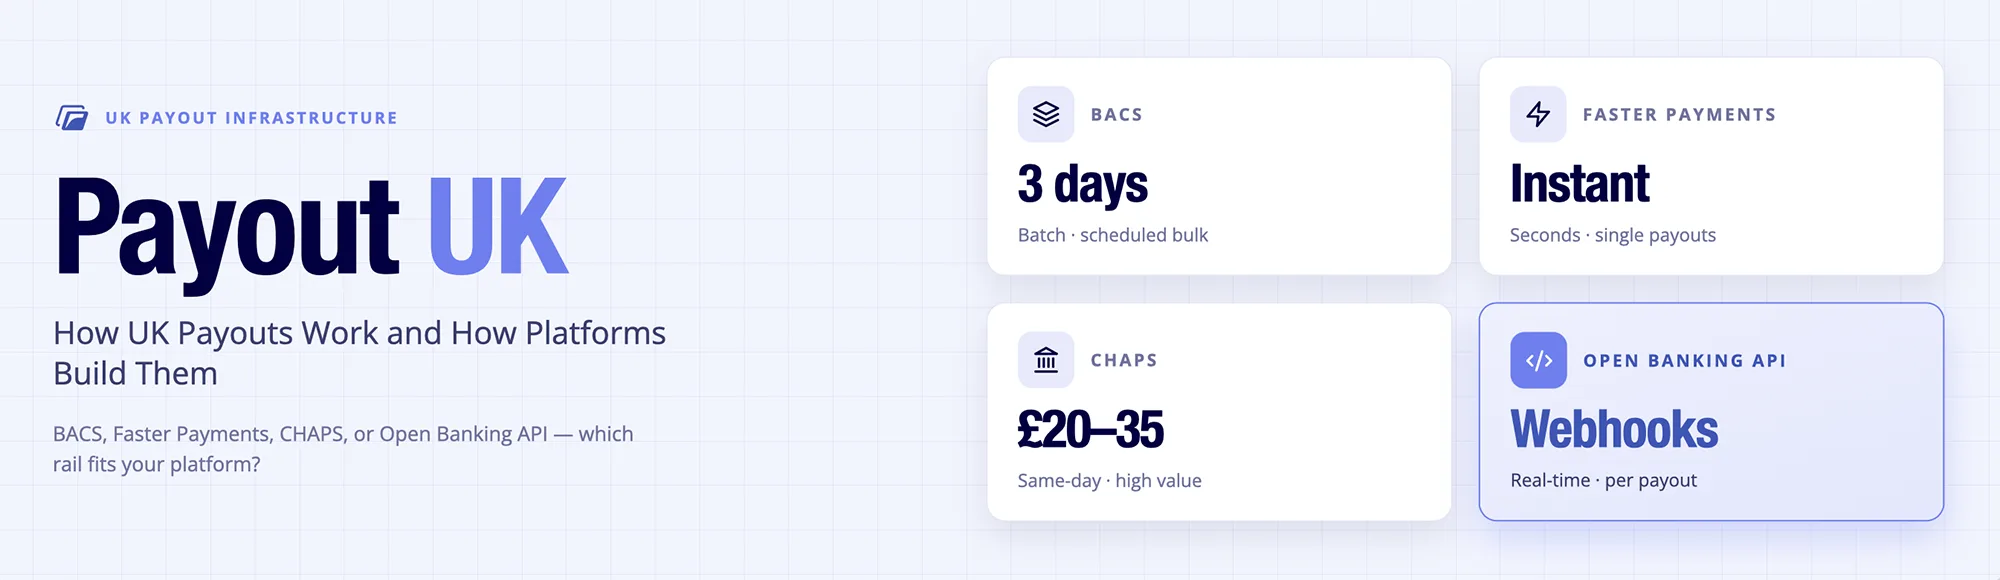
Payout UK: How UK Payouts Work and How Platforms Build Them
Discover how payout UK infrastructure works for businesses and platform builders. Compare BACS, Faster Payments, CHAPS, and Open Banking APIs to understand settlement speeds, payment visibility, and automation, helping you choose the right approach for high-volume, scalable payouts across the UK.
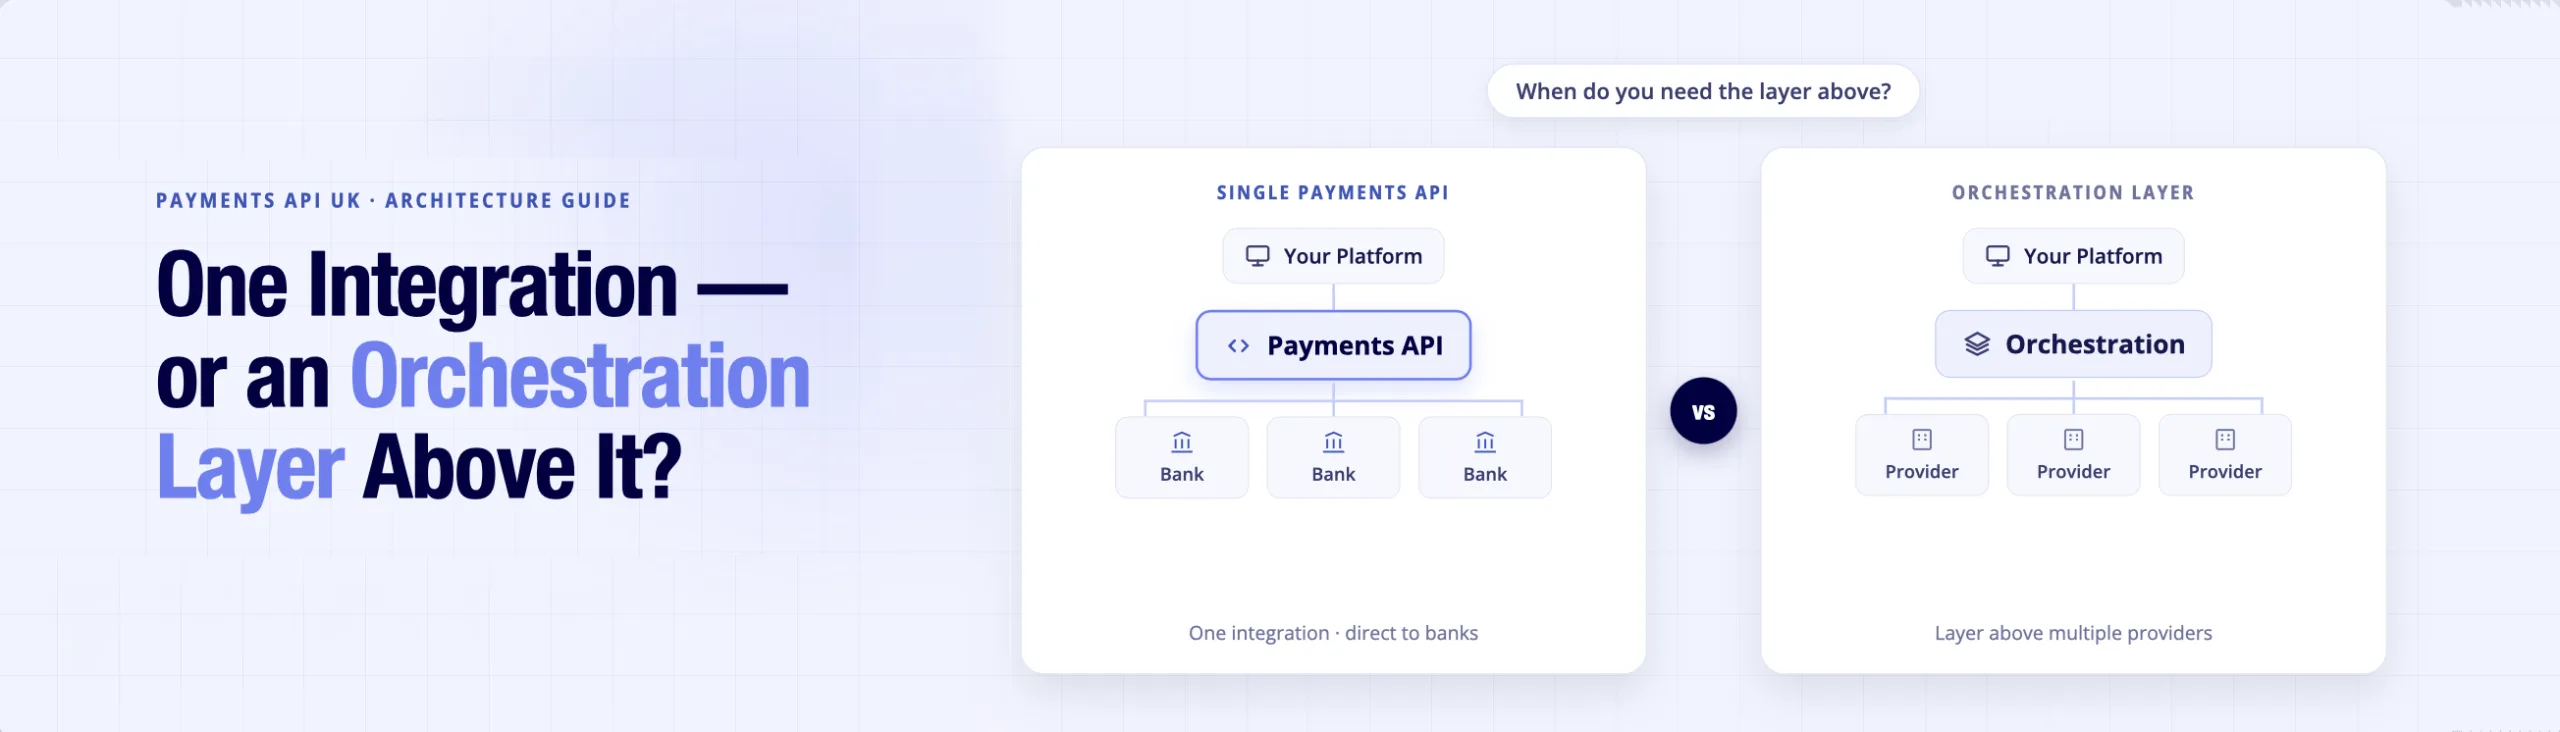
Payments API UK: What It Is and How Orchestration Extends It
Not every platform needs payment orchestration from day one. Learn the difference between a payments API and an orchestration layer, how each fits into your payment architecture, and when UK businesses should move beyond a single provider for greater resilience and scalability.
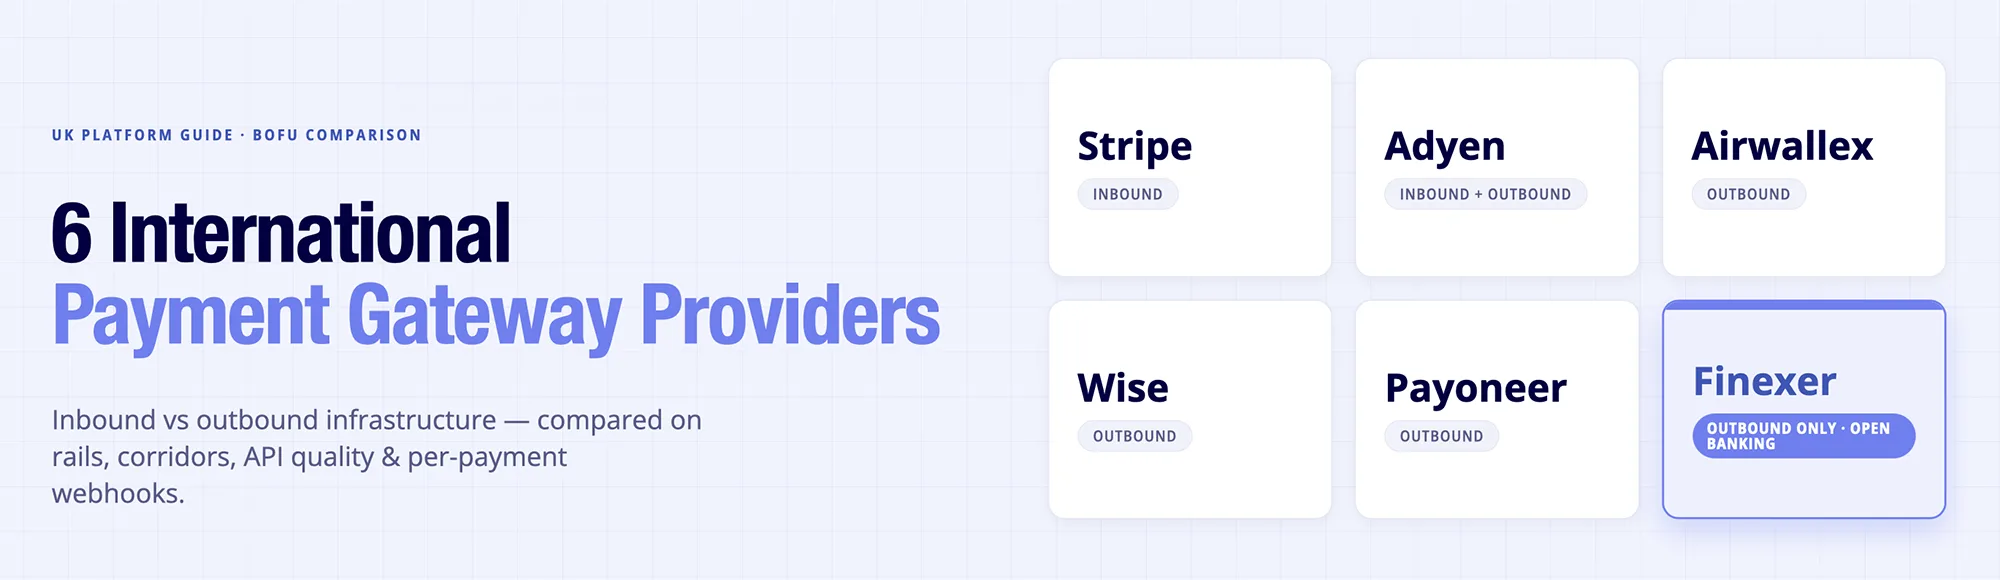
6 International Payment Gateway Providers: UK Platform Guide
Choosing an international payment gateway isn’t just about cost. Compare six leading providers, including Stripe, Adyen, Airwallex, Wise, and Finexer, on FX fees, payment corridors, API capabilities, and cross-border payment infrastructure to identify the best solution for your business and international payout requirements.
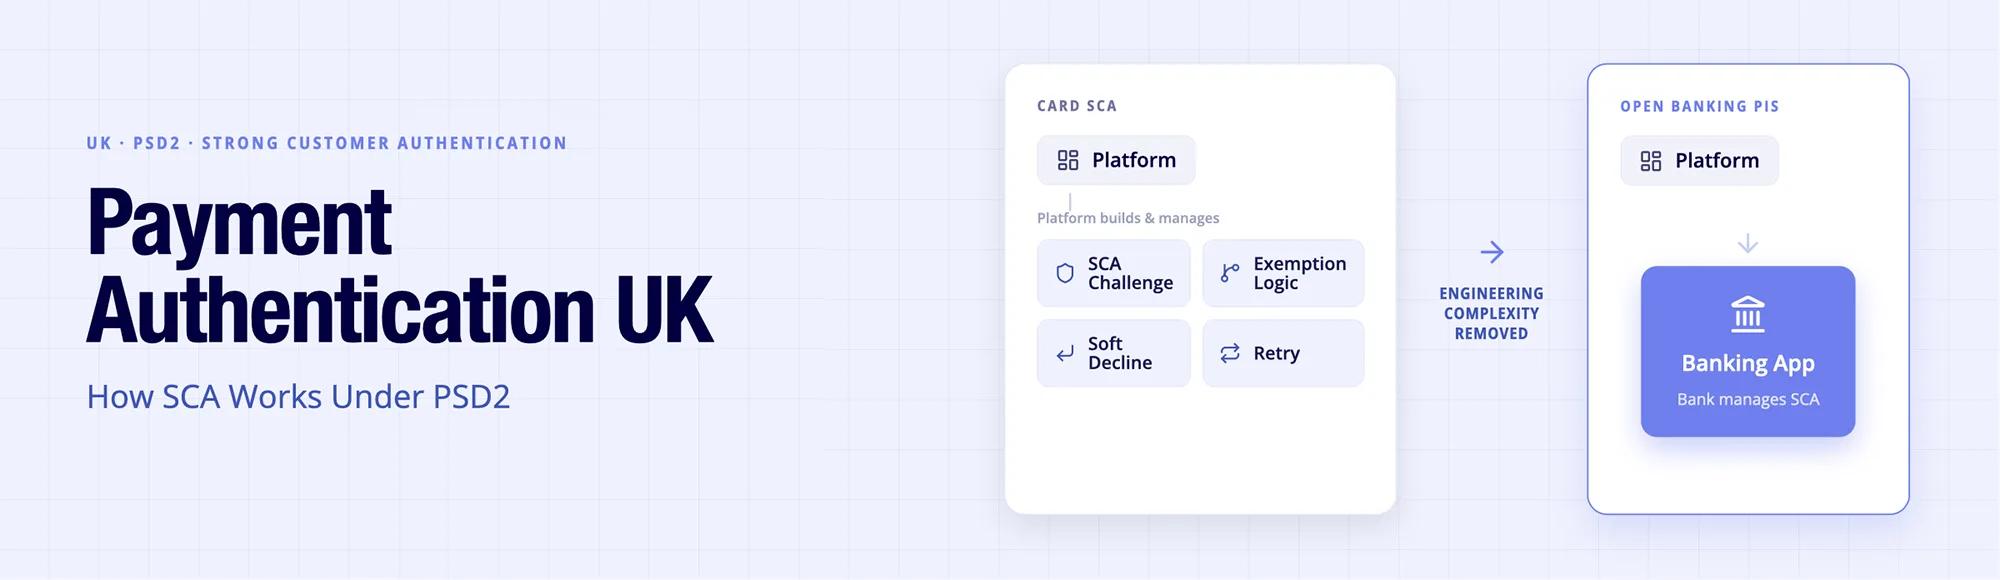
Payment Authentication UK: How SCA Works Under PSD2
Learn how payment authentication works under PSD2, when strong customer authentication (SCA) is required for UK electronic payments, and how card payments differ from Open Banking Pay by Bank. Understand platform responsibilities, SCA exemptions and why bank-managed authentication simplifies Open Banking payment flows.
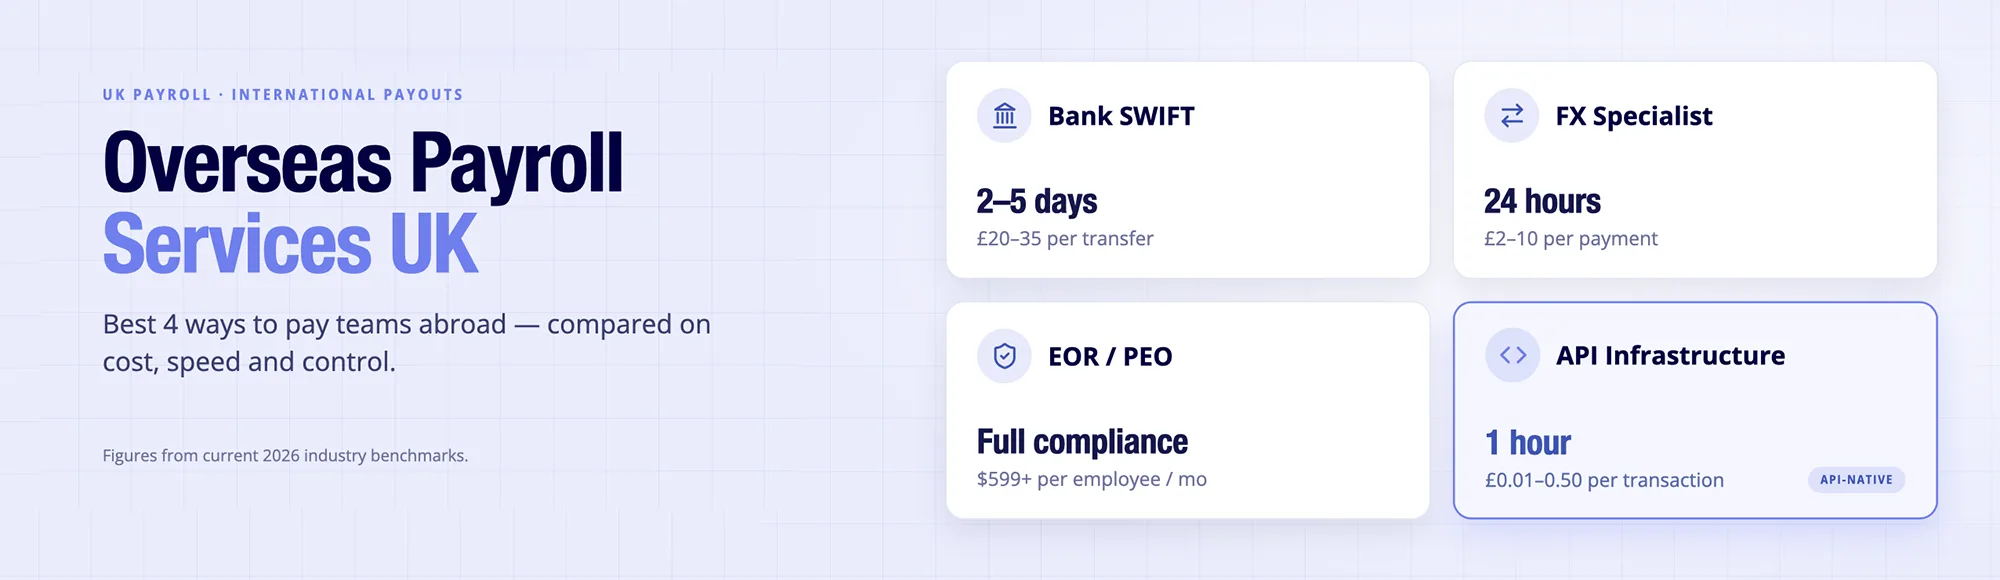
Overseas Payroll Services UK: Best 4 Ways to Pay Teams Abroad
Paying international employees and contractors involves more than simply sending money abroad. Compare four overseas payroll payment methods, including SWIFT, Wise, Airwallex, and Open Banking APIs to understand their costs, settlement speed, payment visibility, and suitability for UK businesses managing global teams.
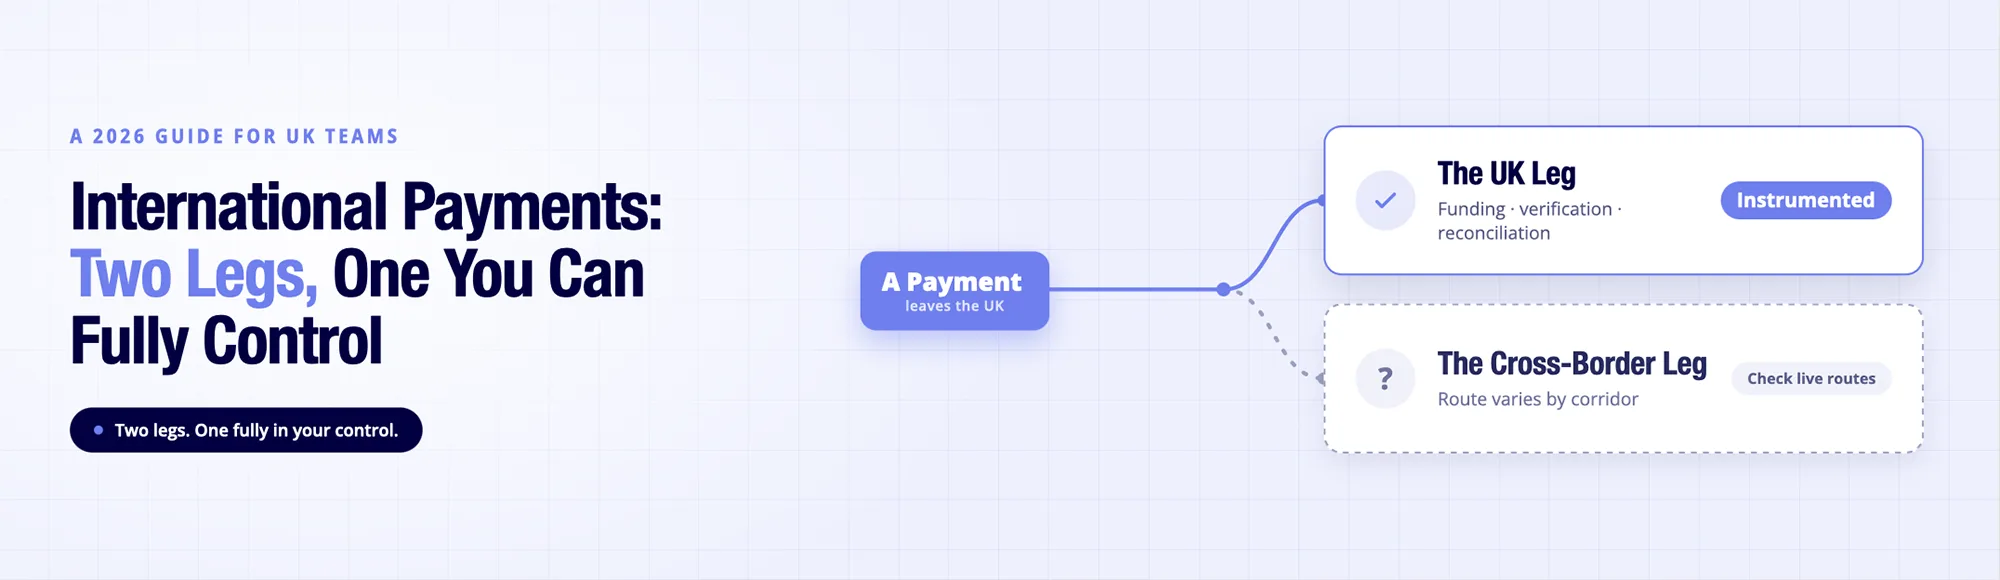
International Payments Still Break at Scale. Here Is Why.
International payments from the UK are two journeys joined together: a fast domestic leg and a slower cross-border leg where fees and visibility hide. This guide explains how each leg works, the four real costs, what Open Banking can and cannot change, and how to compare international payout services properly.
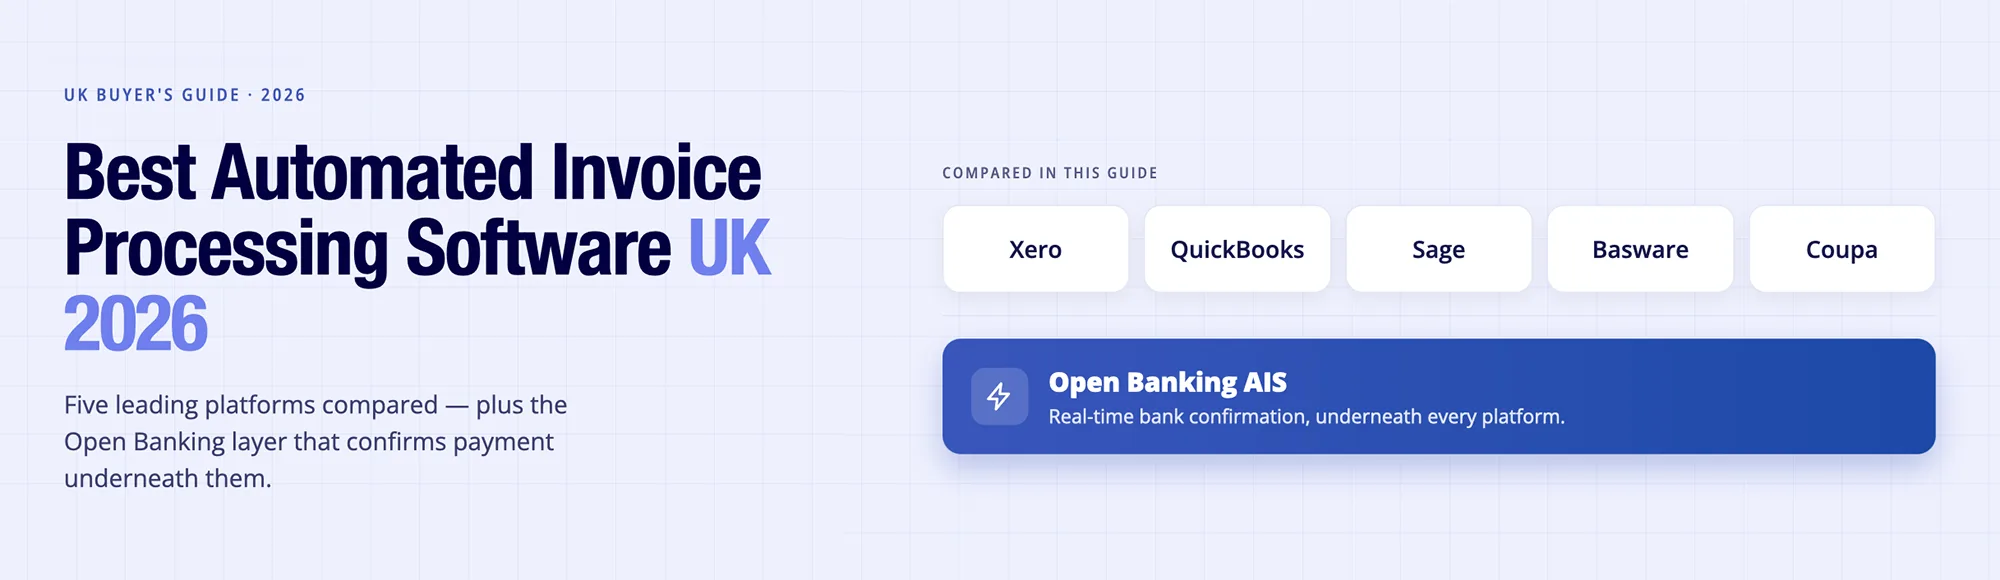
UK’s 5 Best Automated Invoice Processing Software for 2026 Compared
Compare the UK’s leading automated invoice processing software for 2026, including Xero, QuickBooks, Sage, Basware and Coupa. Learn how each platform handles OCR, approvals and reconciliation invoice workflows, and why Open Banking AIS enables faster, real-time payment matching beyond traditional bank feeds.
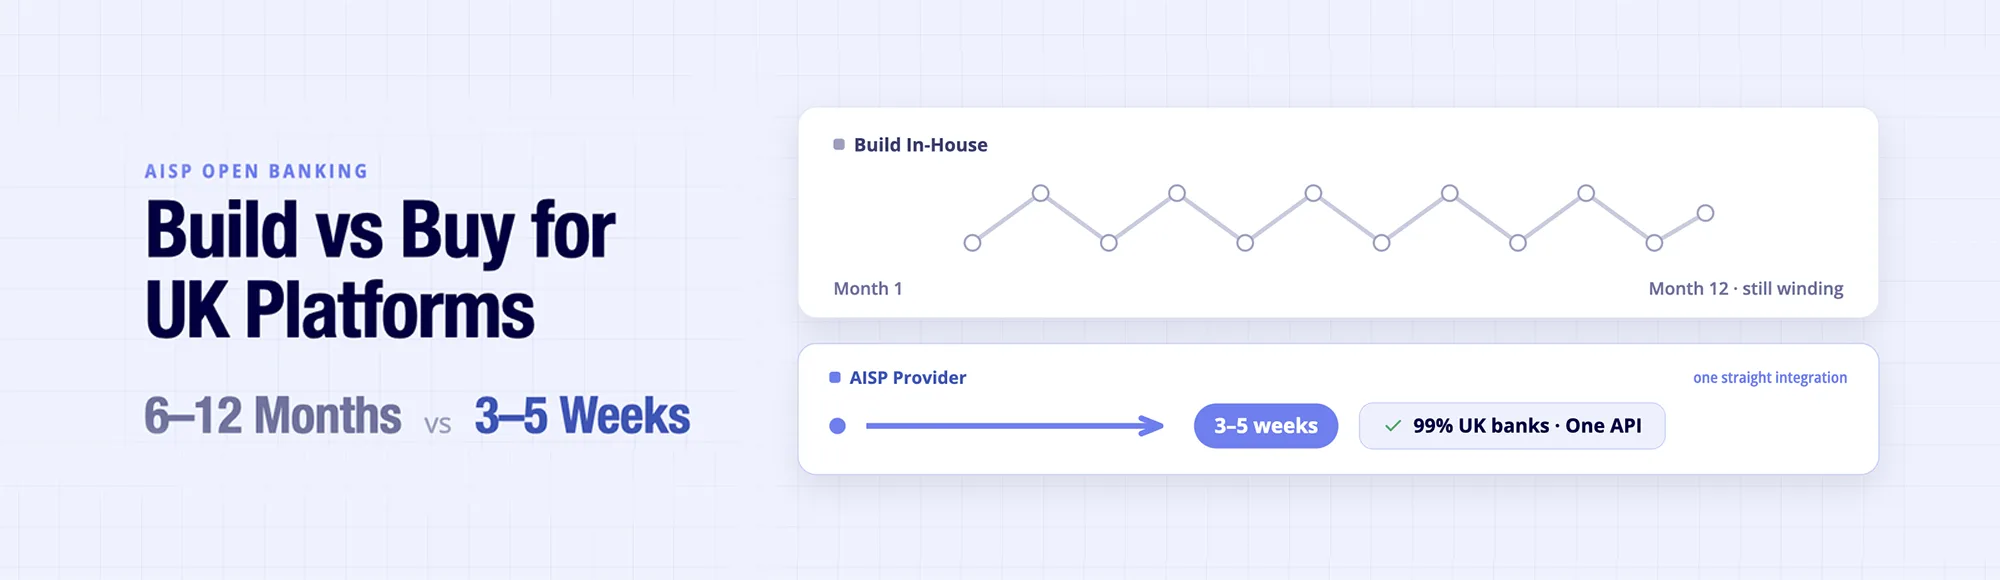
AISP Open Banking: Build vs Buy for UK Platforms
Deciding whether to build direct bank connections or use an AISP Open Banking provider comes down to engineering time and ongoing maintenance cost. This guide compares in-house integration against open banking AISP infrastructure on timeline, FCA authorisation, consent handling and reliability, so UK platform teams can evaluate the real cost of each path.
UK’s 5 Best Rental Property Accounting Software 2026 Compared
Rental property accounting software helps UK landlords and lettings platforms manage rent, expenses, reconciliation and HMRC reporting. This comparison reviews Hammock, LandlordStudio, Xero, FreeAgent and QuickBooks, while explaining how open banking reference workflows and Open Banking connectivity improve rental income verification and bank transaction visibility.
Best Invoice Tracking Software in the UK: Top 5 Tools Compared 2026
Choosing the best invoice tracking software means comparing more than invoice creation. This guide reviews Invoice Ninja, Xero, Square Invoices, Invoicely and Wave on payment tracking, bank integration and reconciliation, then explains how Open Banking infrastructure enables real-time, bank-confirmed invoice status for UK finance platforms beyond traditional CSV-based workflows.
Global Mass Payouts: Why They Break at Scale? (UK Guide)
Global mass payouts break at scale for predictable reasons: batch blindness, partial failures, and reconciliation lag. This UK guide explains the three failure modes, the two-layer architecture that fixes them, and how one ERP platform cut its payout time by 15 days after moving to per-payout webhooks.
UK Payout APIs: Open Banking Disbursements for Platforms
Open Banking PIS lets UK platforms program Faster Payments for outbound disbursements and receive per-payout webhook status, reducing manual CSV uploads and reconciliation delays. This guide explains how payout APIs work, compares card/BACS/Open Banking options, and gives engineers a checklist for choosing a provider: coverage, webhooks, idempotency, sandbox fidelity, compliance, onboarding and pricing.
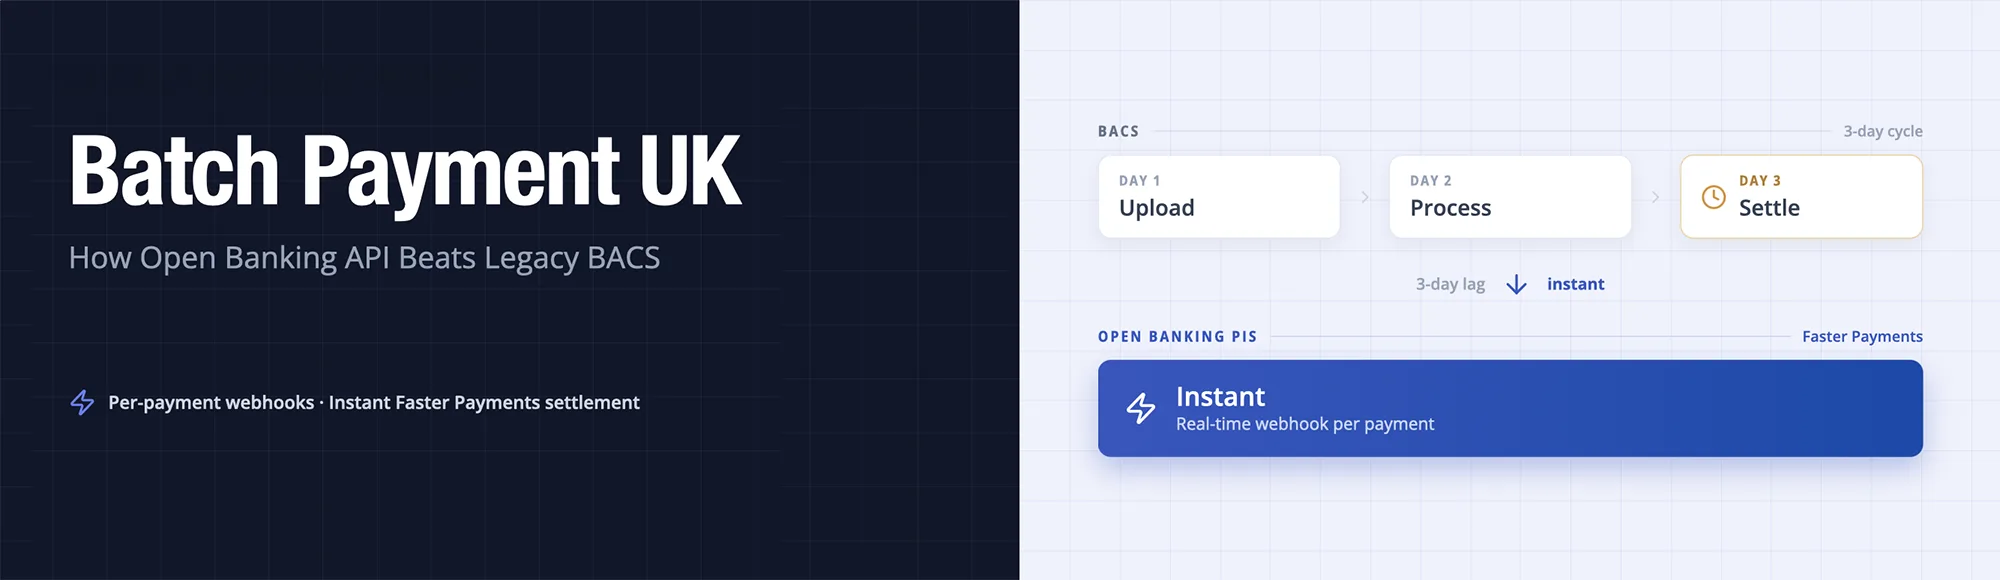
Batch Payment UK: How Open Banking API Beats Legacy BACS
Still relying on BACS for batch payments? Discover how Open Banking APIs provide faster settlement, real-time payment visibility, automated reconciliation, and a more efficient alternative for UK businesses managing payroll, supplier payments, and mass payouts. Compare the two approaches to find the right payment infrastructure for your organisation.
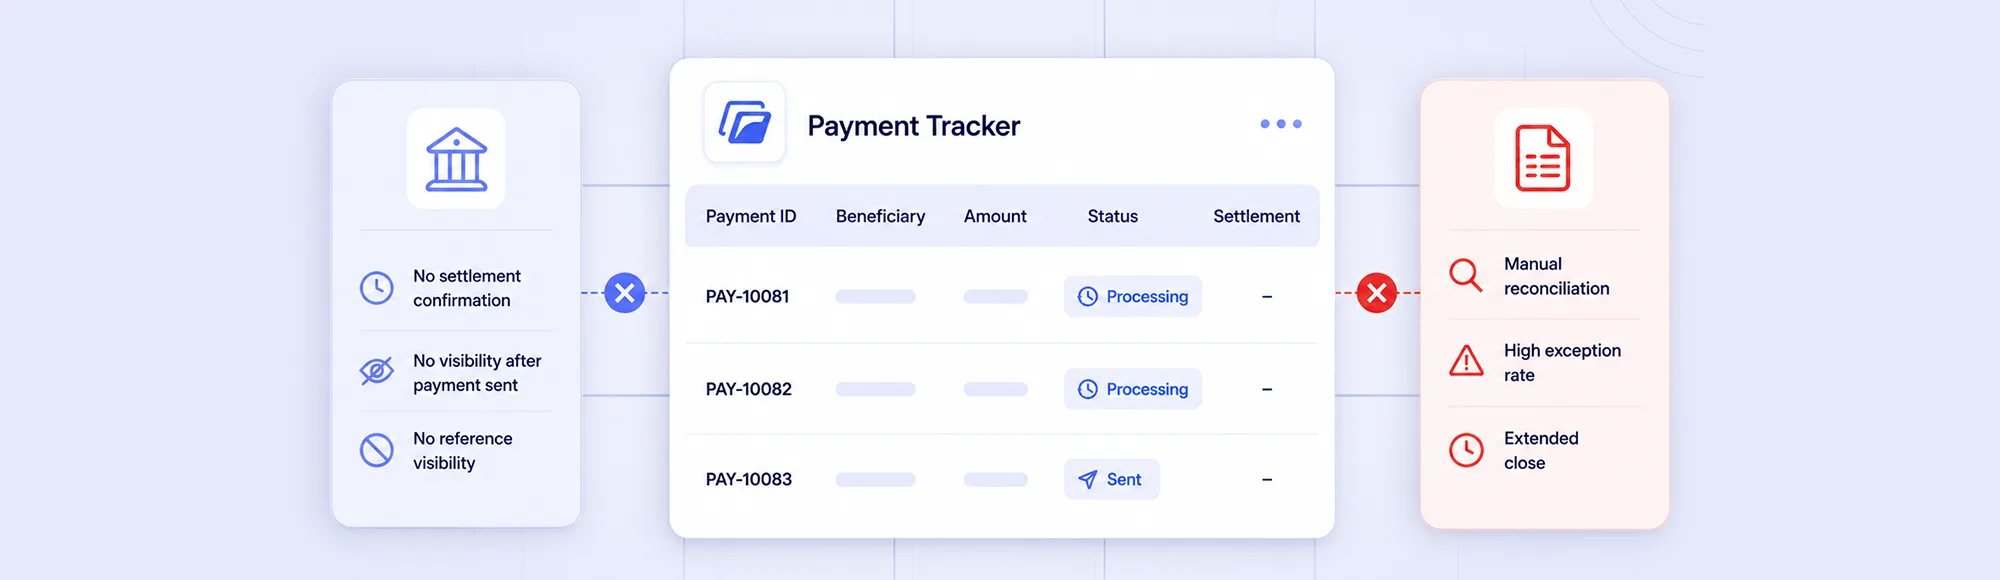
Why Your Payment Tracker Is Not Telling You Enough
Most payment tracker tools answer one question: did the payment go out? UK finance teams need three more answers. Did it arrive? Did the reference survive? Did it close the reconciliation? Industry research from March 2026 found 85% of UK firms still use manual reconciliation. This blog covers why payment tracking breaks and what fixes it.
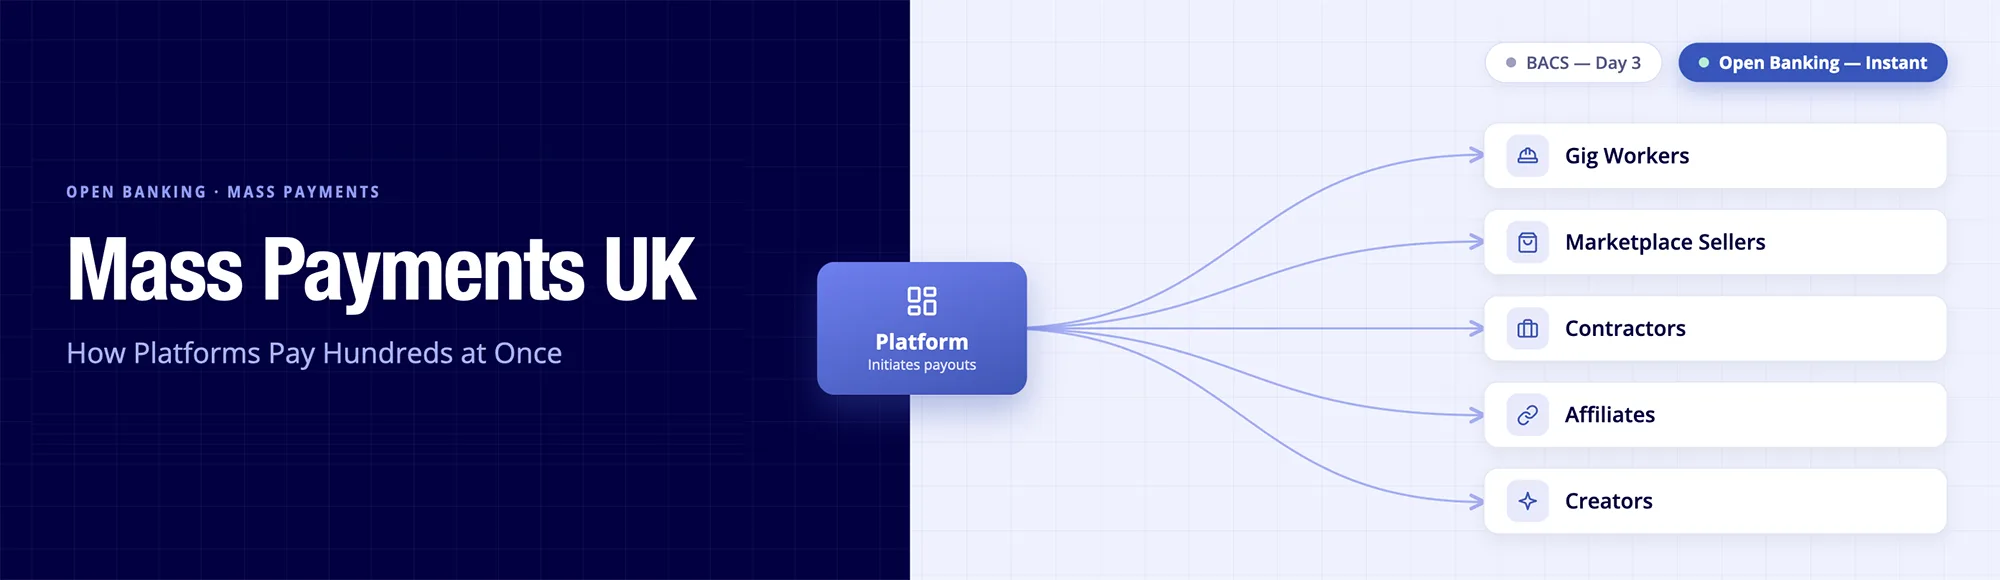
Mass Payments UK: How Platforms Pay Hundreds at Once
Traditional payment methods like BACS can slow down mass payouts with delayed settlement, limited visibility, and late error detection. Discover how Open Banking APIs enable faster, more transparent mass payments with real-time payment status, automated reconciliation, and a better experience for UK platforms paying hundreds or thousands of recipients.
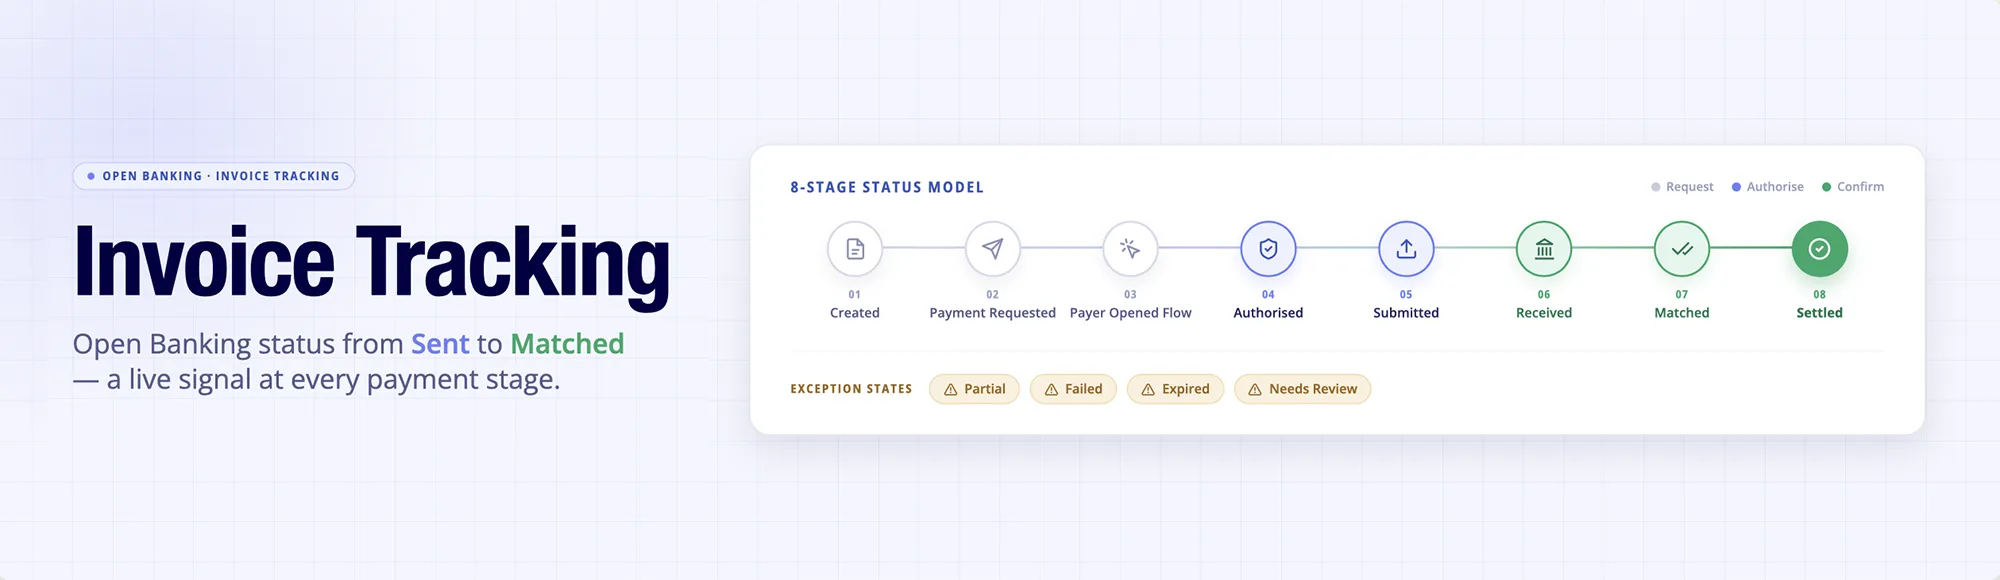
Invoice Tracking: Open Banking Status from Sent to Matched
Invoice tracking with Open Banking gives finance teams per-invoice, real-time status – from payment requested and authorised through bank receipt, matched, and settled – without manual bank checks. Finexer’s OB Invoice Tracker delivers webhooked events (PIS + AIS) so platforms get live payment signals, spot exceptions faster, and delegate reconciliation and UI to their own systems.
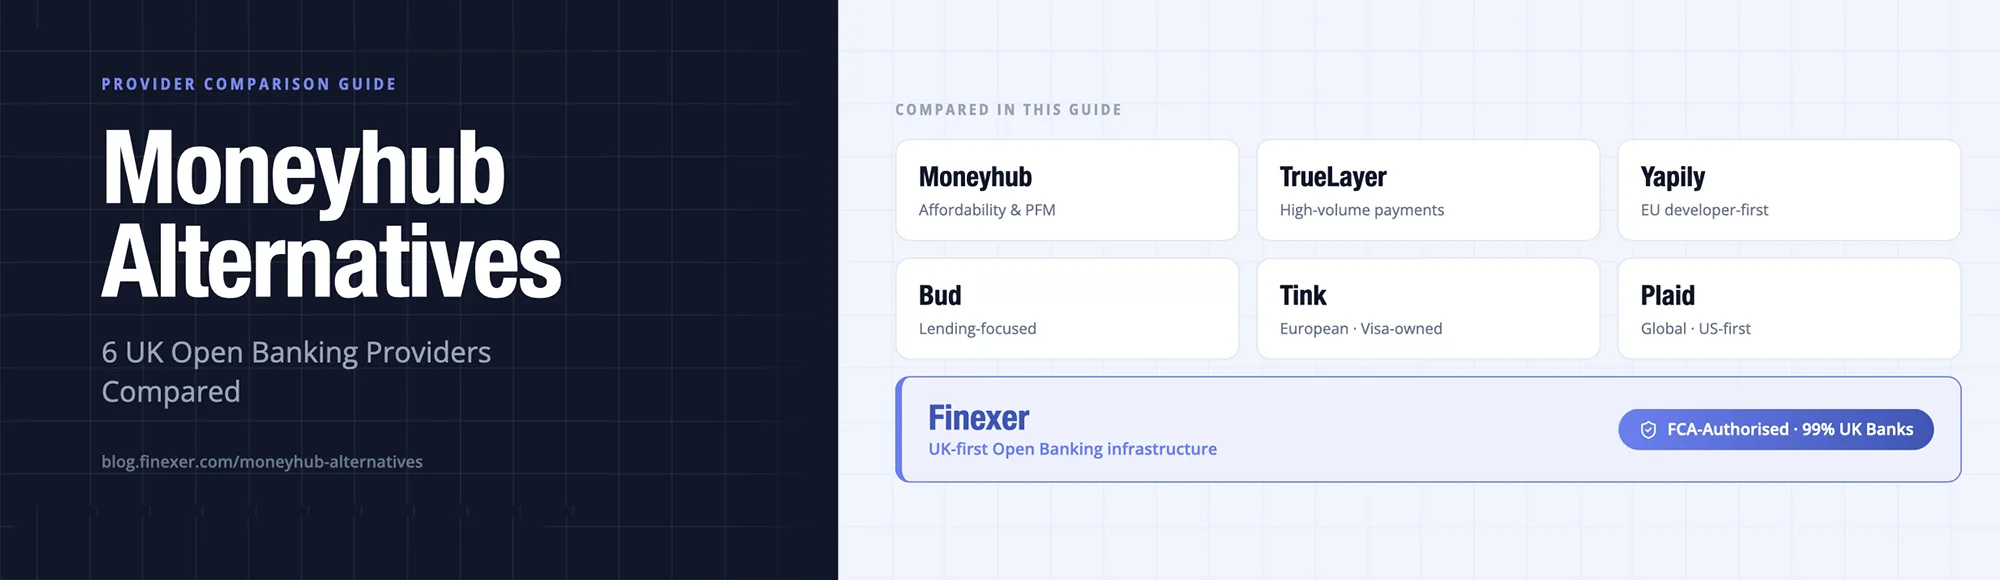
Moneyhub Alternatives: 6 UK Open Banking Providers Compared
Compare the best Moneyhub alternatives for UK Open Banking. This guide breaks down TrueLayer, Yapily, Bud Financial, Tink, Plaid, and Finexer across bank coverage, AIS/PIS capabilities, pricing models, and deployment speed. Ideal for fintech, SaaS, and platform teams evaluating providers for payments, data access, and affordability use cases in the UK market.
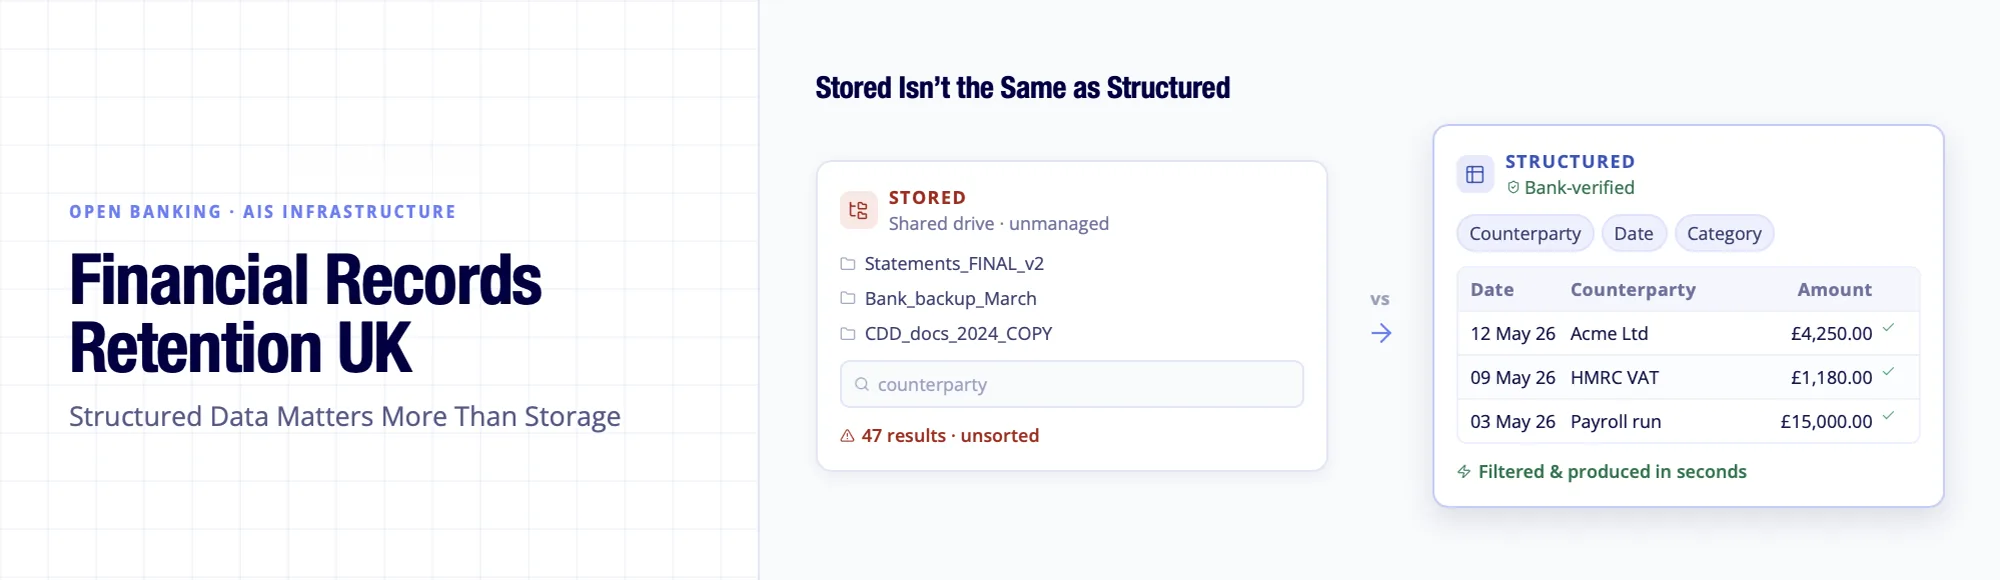
Financial Records Retention UK: Structured Data Over Storage
Financial records retention UK requirements have not changed dramatically in 2026. What has changed is what regulators, auditors, and sanctions investigators actually expect to find when they request evidence. Stored documents are not enough. Structured, accessible, and bank-verifiable transaction data is what regulated platforms need to demonstrate compliance when it is tested rather than assumed.
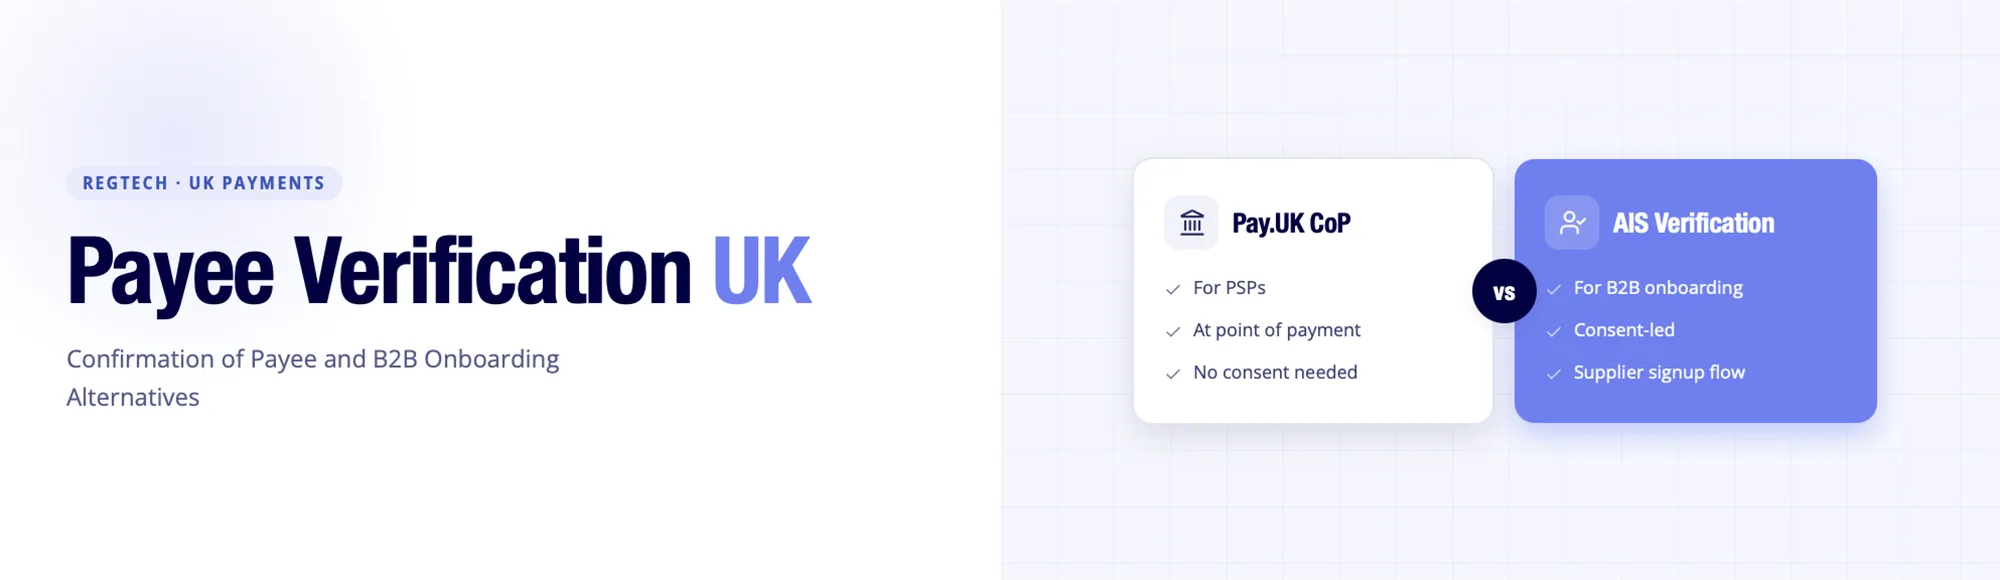
Payee Verification UK: CoP Explained and B2B Alternatives
Payee verification in the UK covers two distinct mechanisms: the regulated Pay.UK Confirmation of Payee scheme for PSPs checking accounts before payment, and AIS-based bank account verification for B2B platforms onboarding suppliers. This guide explains how Confirmation of Payee works, who must comply, who provides it, and where Open Banking verification fits B2B onboarding workflows.
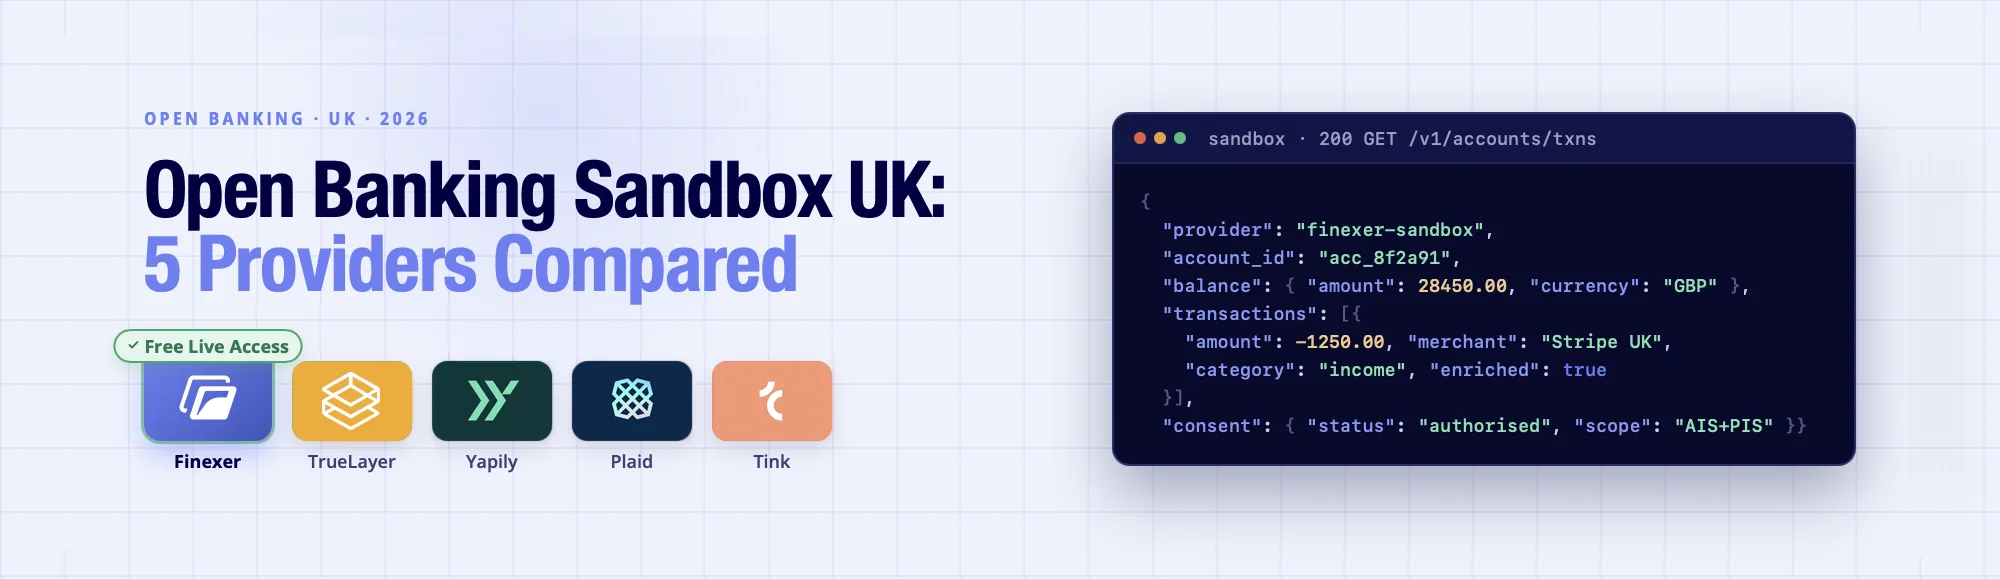
Open Banking Sandbox UK: Finexer vs TrueLayer vs Yapily vs Plaid vs Tink Compared
Most open banking sandboxes look identical until you try to go live. Some providers offer free signup and instant access. Others route every enquiry through a sales call before testing a single endpoint. This comparison covers five UK open banking sandbox environments on free access, AIS and PIS coverage, bank simulations, and time to live.
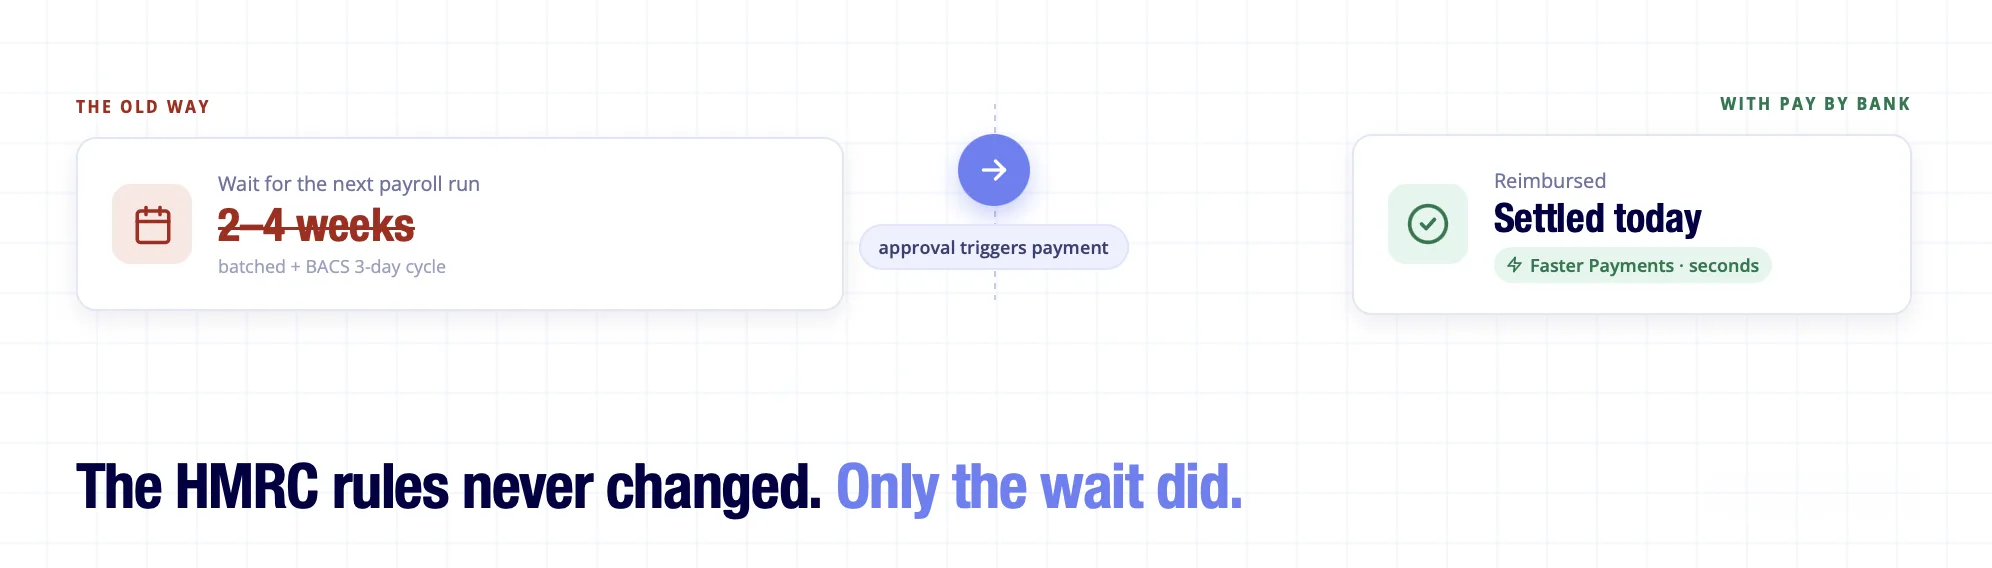
Employee Expense Reimbursement: UK Rules and Process
Employee expense reimbursement in the UK is governed by HMRC ITEPA s336 – tax-free only when an expense is wholly, exclusively, and necessarily incurred for work. The rules are clear. The wait is not: most reimbursements sit two to four weeks for the next payroll run. This guide covers both the rules and the fix.
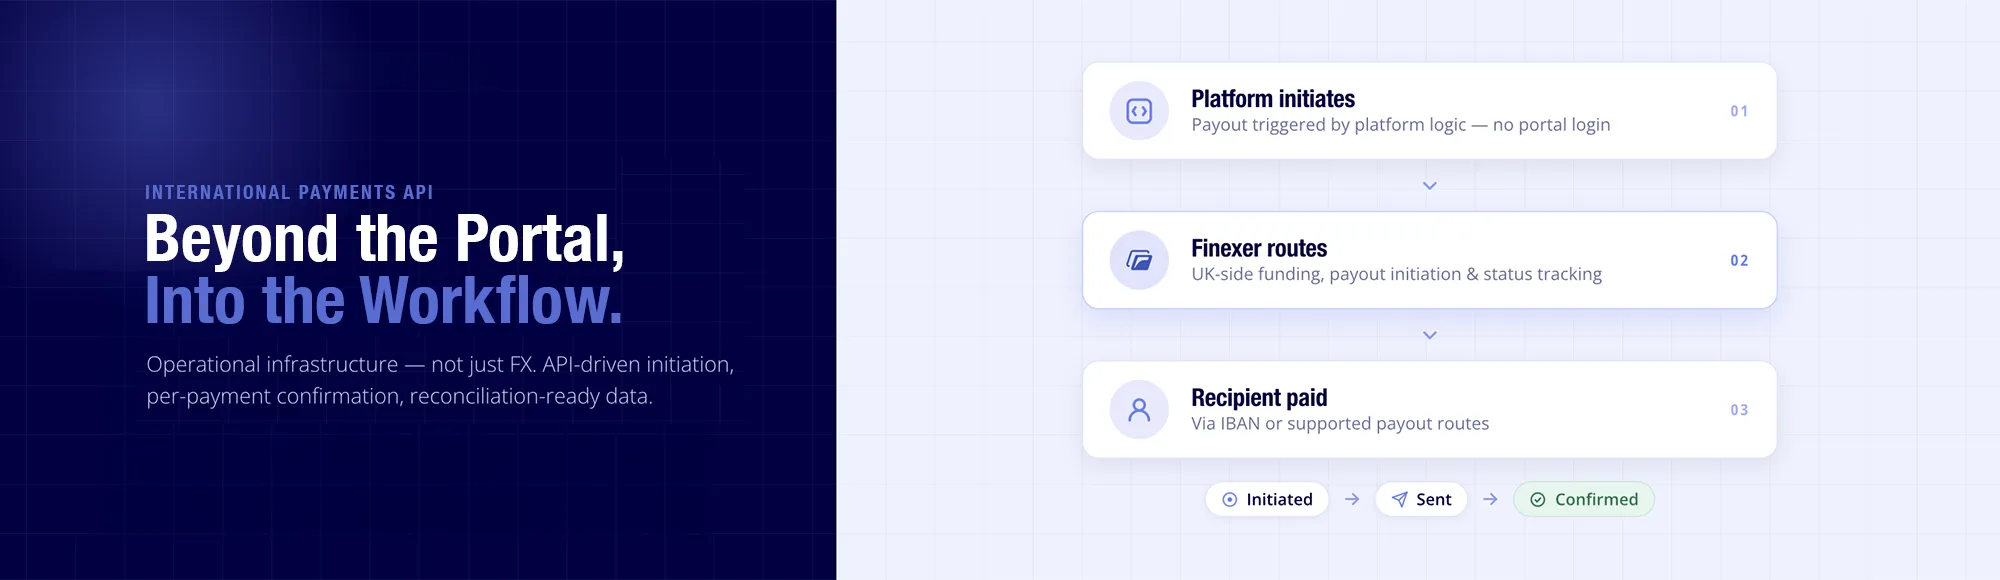
International Payments APIs Are Not Just for FX. They Are Becoming Operational Infrastructure.
Most businesses still treat international payments as a manual problem – bank portals, SWIFT references, chasing confirmations. An international payments API changes that. This blog covers why cross-border payment workflows break at the operational layer, what a cross border payments API actually needs to deliver, and how infrastructure-first businesses are replacing the manual steps entirely.
Bud Financial Alternatives: Top 6 UK Open Banking Providers
Looking for Bud Financial alternatives for your UK Open Banking platform? This comparison covers six providers, Finexer, TrueLayer, Tink, Plaid, Yapily and Moneyhub, on UK bank coverage, AIS, transaction data enrichment and white-label capability. Lending platforms are directed to lending-focused alternatives. Non-lending platforms find the UK data and payments stack that fits their use case.
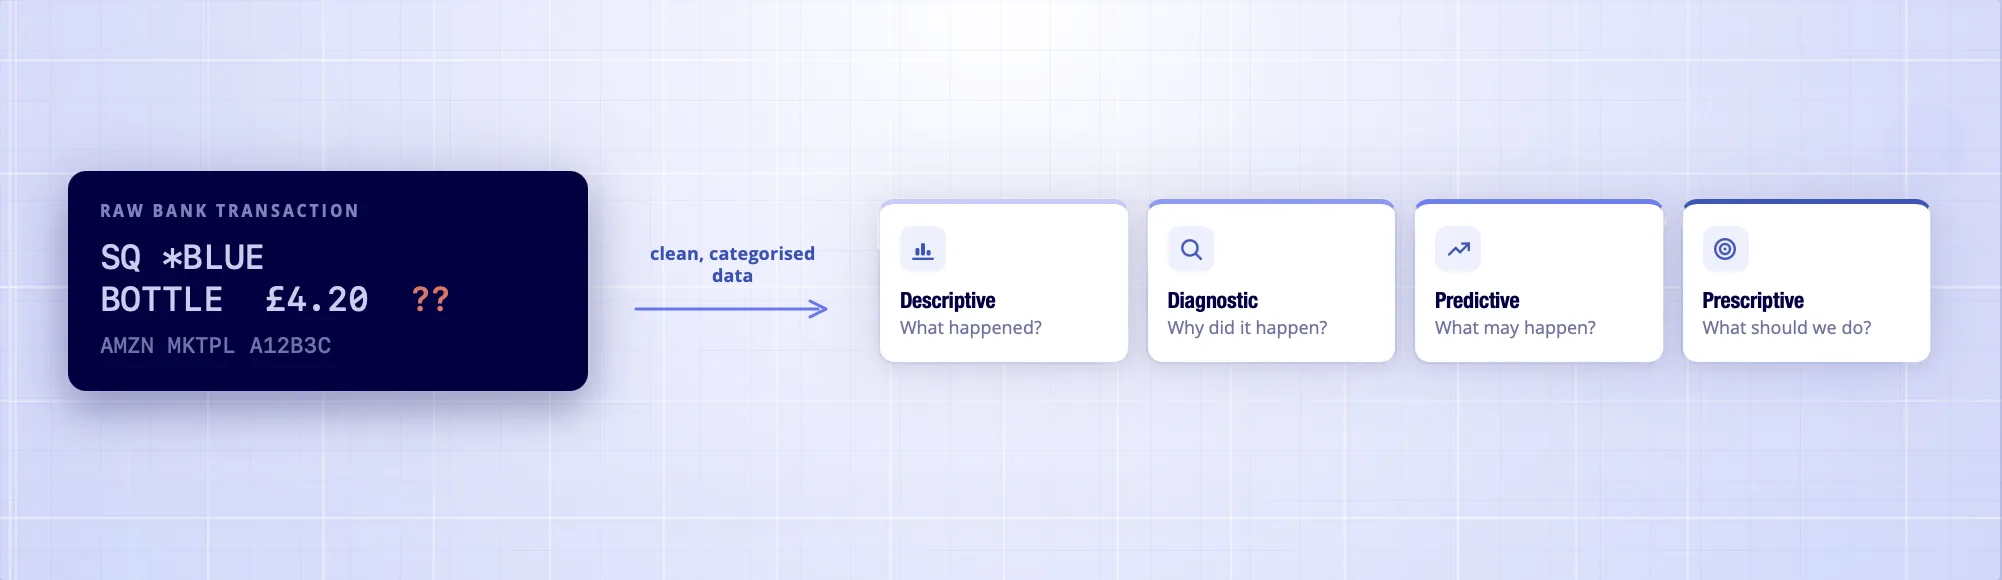
Financial Data Analysis: The 4 Types and How to Apply Them
Financial data analysis examines transactions, revenue, and cash flow to support business decisions. It falls into four types under the Gartner framework: descriptive, diagnostic, predictive, and prescriptive. Each answers a different question, and each depends on clean, categorised data underneath. This guide explains all four with practical UK examples and where data quality fits in.
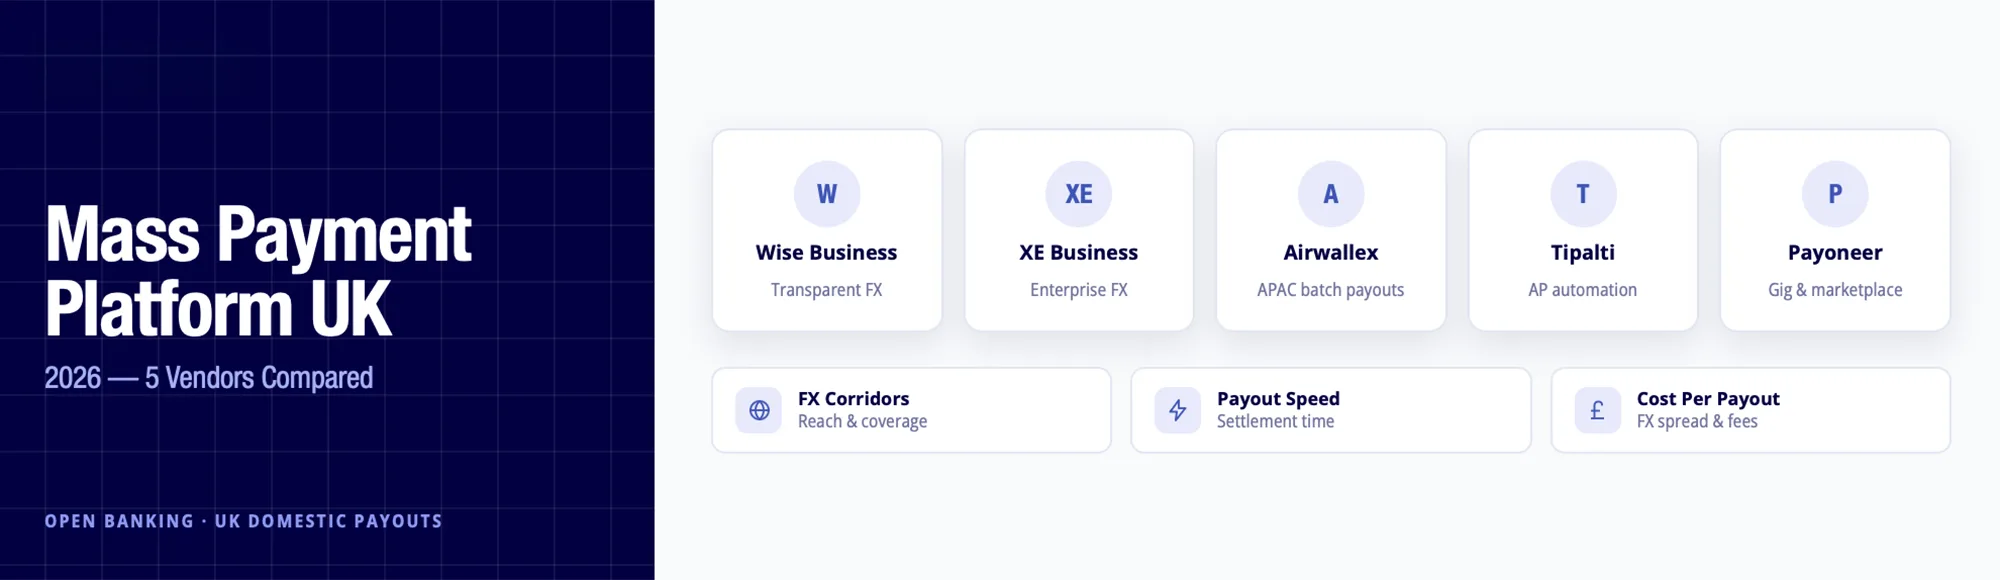
Mass Payment Platform UK 2026: Top 5 Vendors Compared
A mass payment platform sends hundreds or thousands of bulk payments to contractors, marketplace sellers and suppliers across multiple corridors in a single batch. This comparison reviews five platforms, Wise Business, XE, Airwallex, Tipalti and Payoneer, on corridor coverage, FX cost and payout speed, with a guide for UK marketplaces, gig platforms and payroll teams.
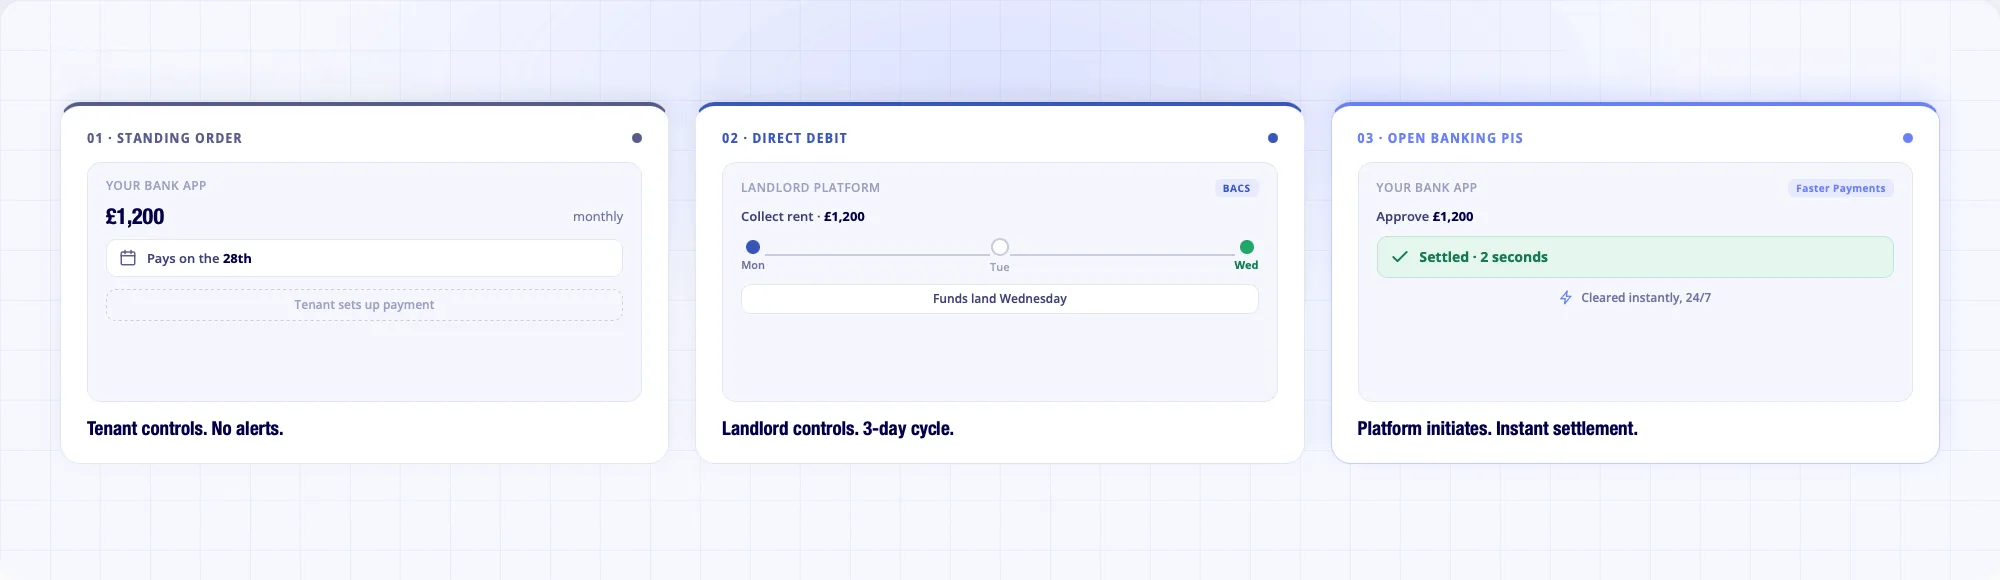
Landlord Rent Collection in the UK: Standing Order vs Direct Debit vs Open Banking Compared
Most UK landlords default to Standing Orders because that is how rent has always been collected. The method is free but gives the landlord no control. Direct Debit adds control, but it also adds fees. Open Banking is the newer option. This blog compares all three landlord rent collection methods on cost, speed, and reconciliation.