Finexer Open Banking Blogs
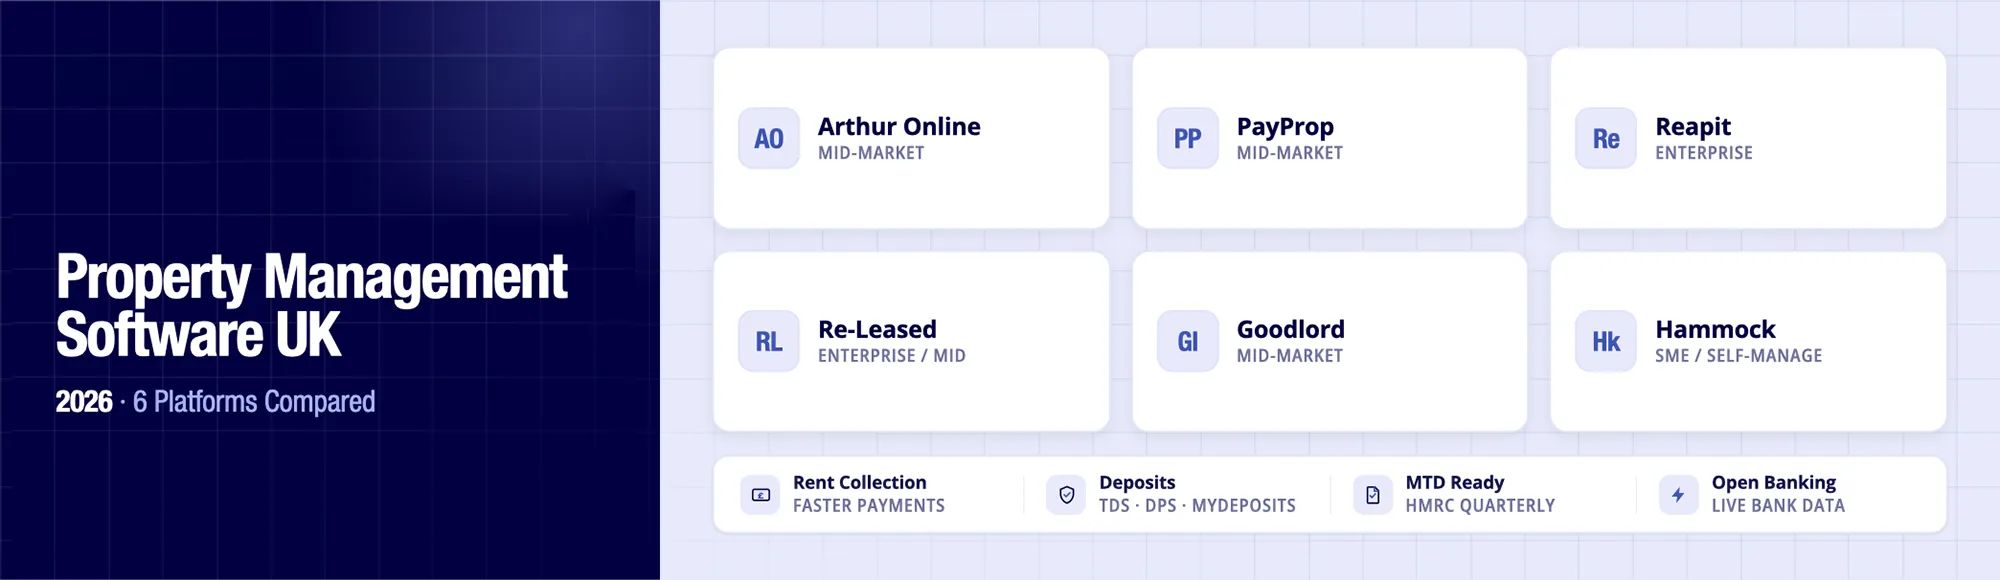
Property Management Software UK 2026: Top 6+ Compared
Property management software UK landlords and letting agents use to run tenancies covers rent collection, deposits, maintenance, accounting and MTD compliance in one platform. This comparison reviews six tools, Arthur Online, PayProp, Reapit, Re-Leased, Goodlord and Hammock, with a decision guide for self-managing landlords, letting agencies and PropTech platform builders evaluating Open Banking payments integration.
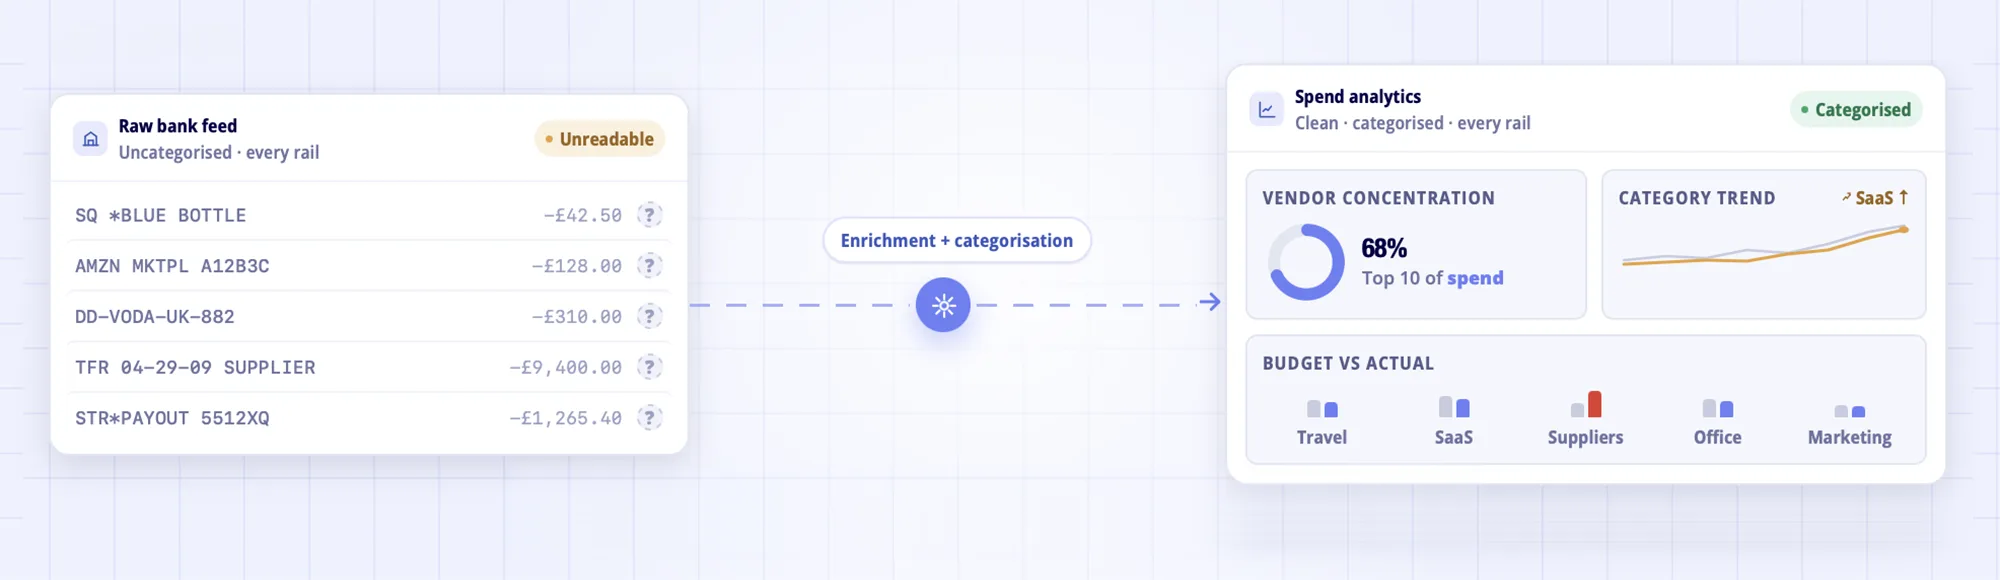
Spend Analytics UK: How Clean Bank Data Powers Finance Visibility
Spend analytics is the layer that turns raw transaction data into vendor, category, and budget insight. Most finance teams already capture their spend. What they lack is clean, categorised data across every payment rail. This blog explains what spend analytics is, why card-only tools fall short, and what a clean bank-data feed actually makes possible.
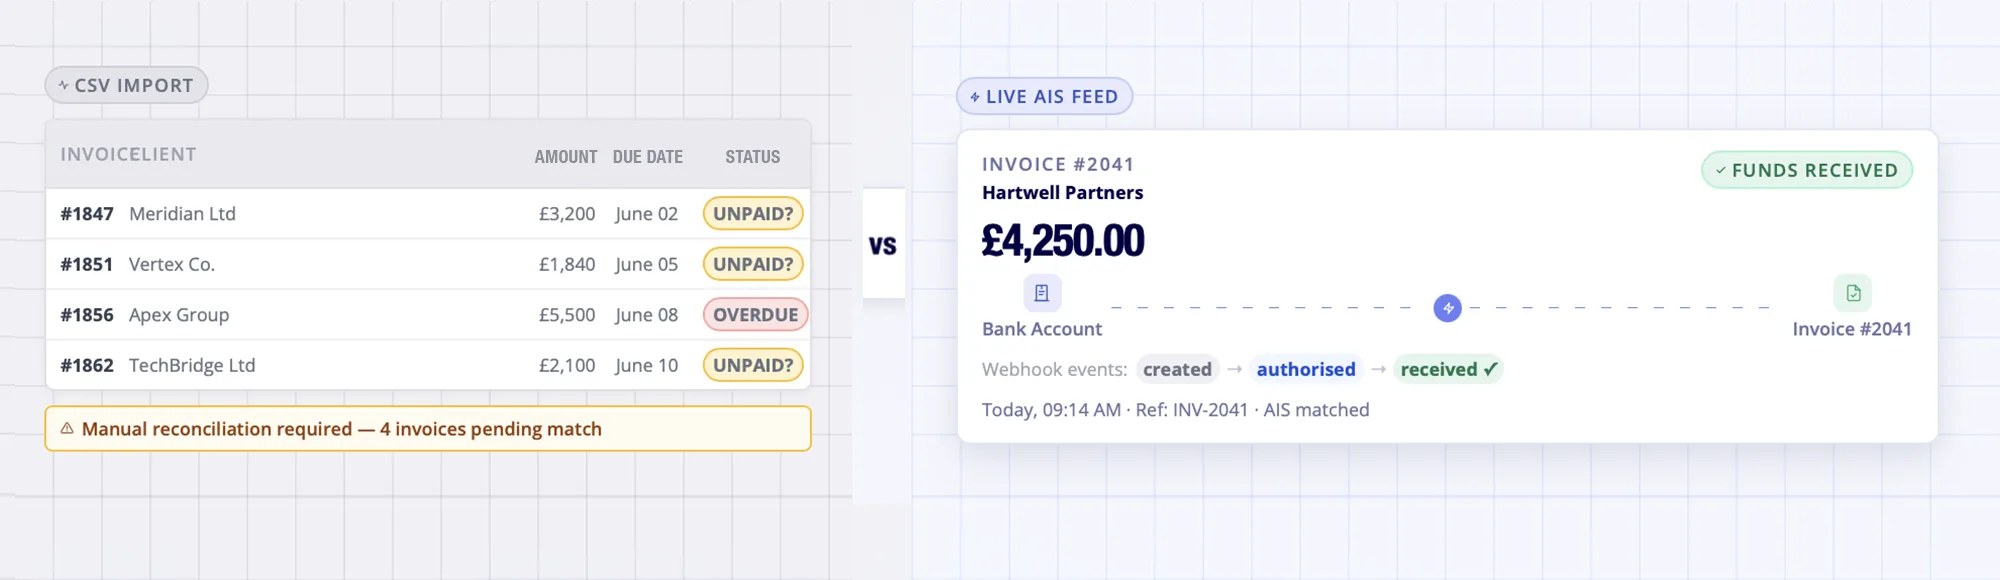
Invoice Tracker UK: Open Banking Invoice Reconciliation
Finexer’s invoice tracker UK connects invoice records with live Open Banking bank data, Pay by Bank initiation and per-event webhooks from request to bank-matched confirmation. Platforms building invoice tracking as a product feature use the Finexer Invoice Reconciliation Tracker as the regulated bank data and payment layer. The platform owns the workflow. Finexer provides connectivity.
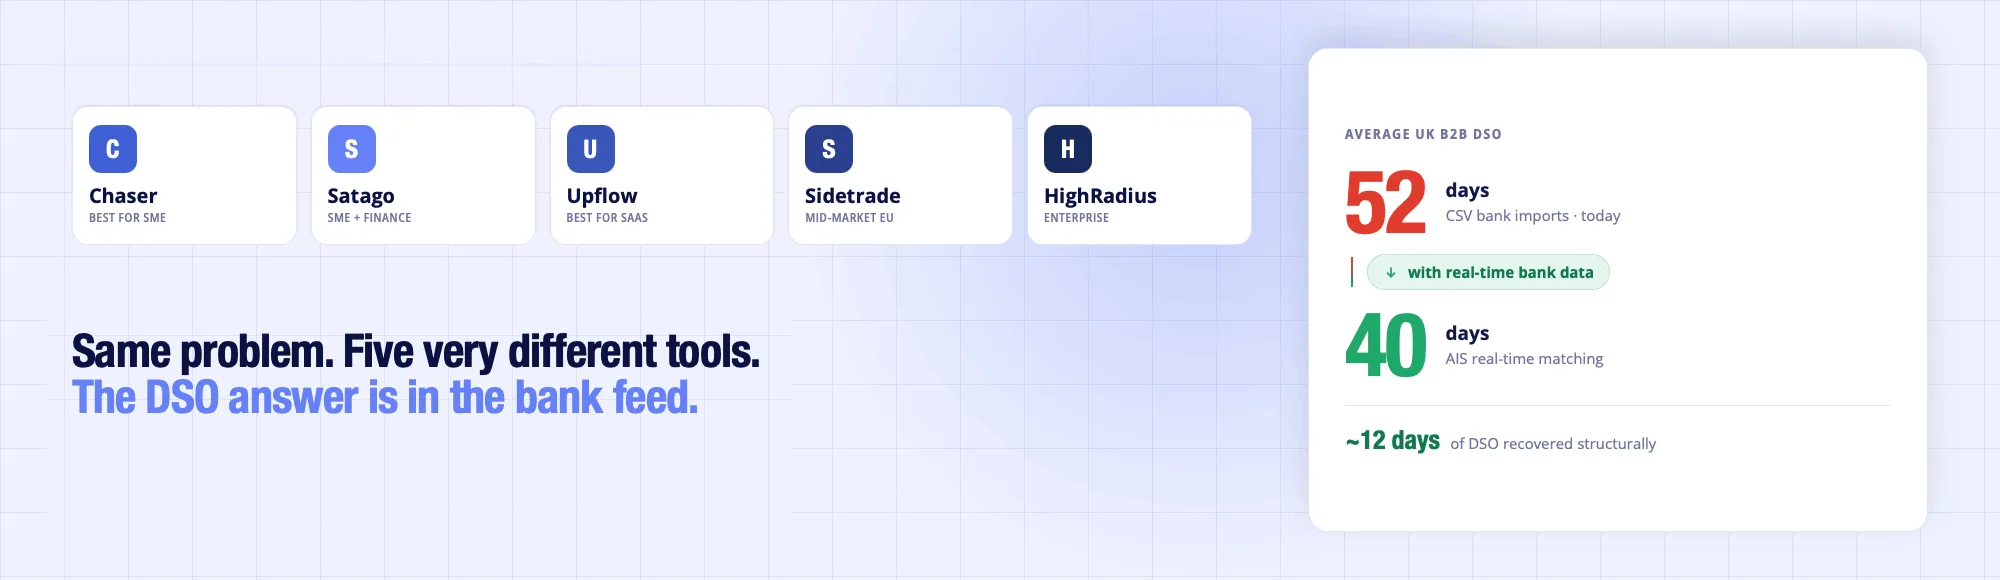
Collections Software UK: Top 5 Tools Compared (Chaser, Satago, Sidetrade, Upflow, HighRadius)
Western European B2B Days Sales Outstanding now averages 52 days, up from 41 in 2023, with UK businesses tracking close to that average. UK finance teams are shortlisting collections software to claw the number back. This blog compares Chaser, Satago, Sidetrade, Upflow and HighRadius on dunning workflow, bank data integration, accounting platforms, and pricing model.
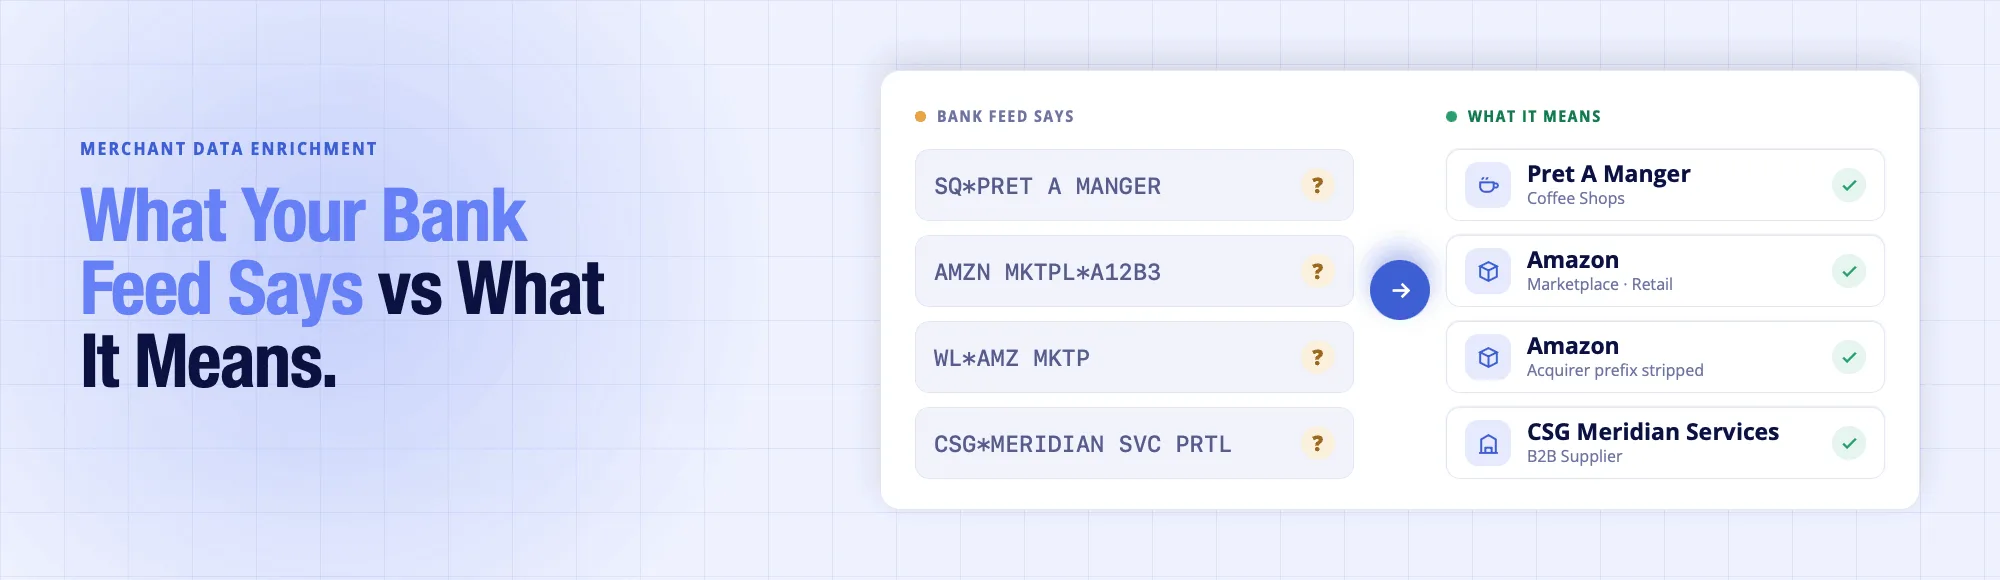
Merchant Data Enrichment APIs Compared: From Cryptic Strings to Clean Merchant Names
Merchant data enrichment resolves raw bank transaction strings – SQPRET A MANGER, AMZN MKTPLA12B3 – into clean merchant names, categories, logos and locations. This comparison covers how five merchant data enrichment APIs process those strings, what each provider returns, which fits your UK platform use case and coverage requirements, and what to test before choosing.
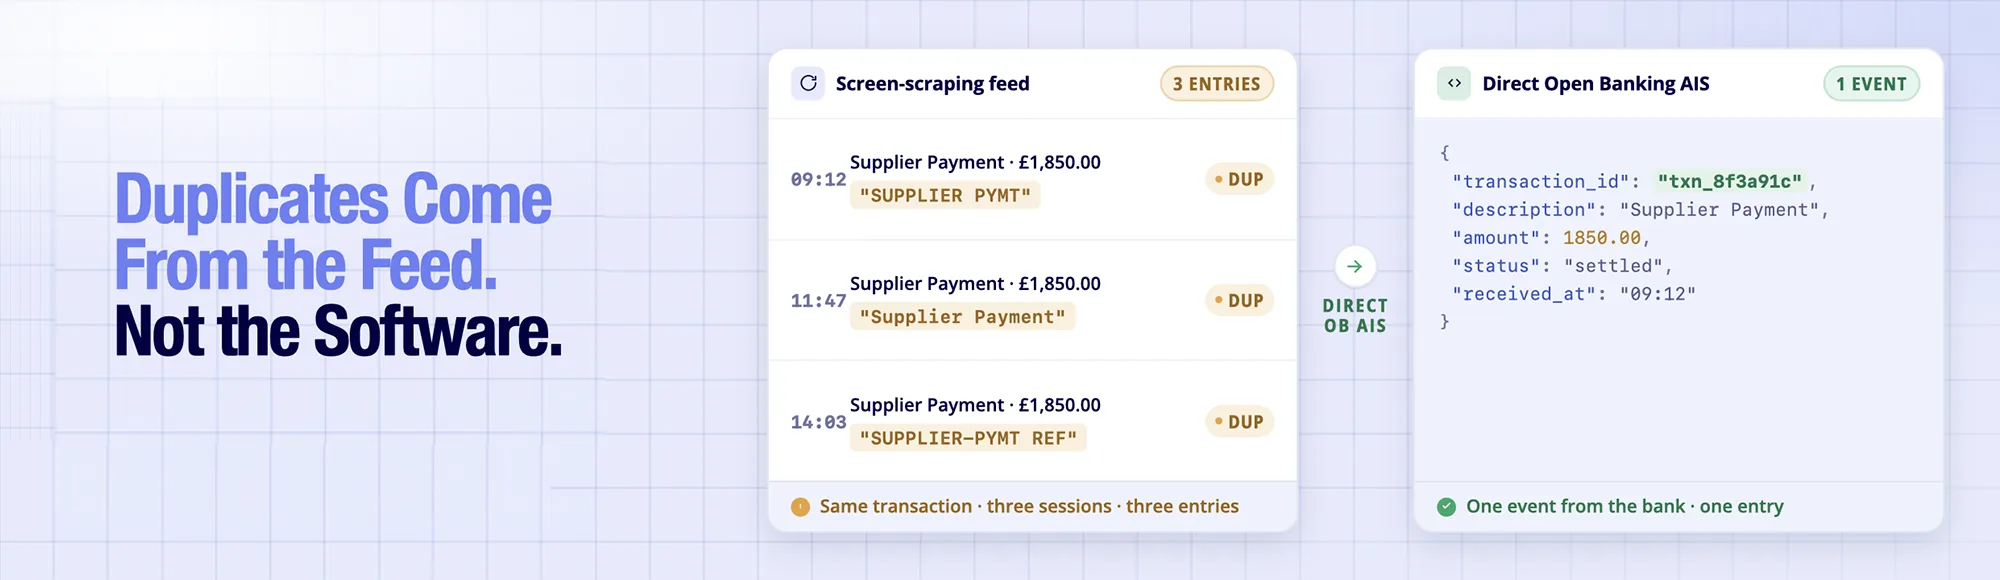
Why Duplicate Transactions Appear in Bank Feeds (and How Direct Open Banking Prevents Them)
Most duplicate transactions in bank feeds are not software bugs. They are predictable consequences of how the feed collects data – screen-scraping refresh cycles, batch sync gaps, and reconnection re-imports generate duplicates at source. This blog explains each cause and why direct Open Banking AIS eliminates most of them before they reach your accounting system.
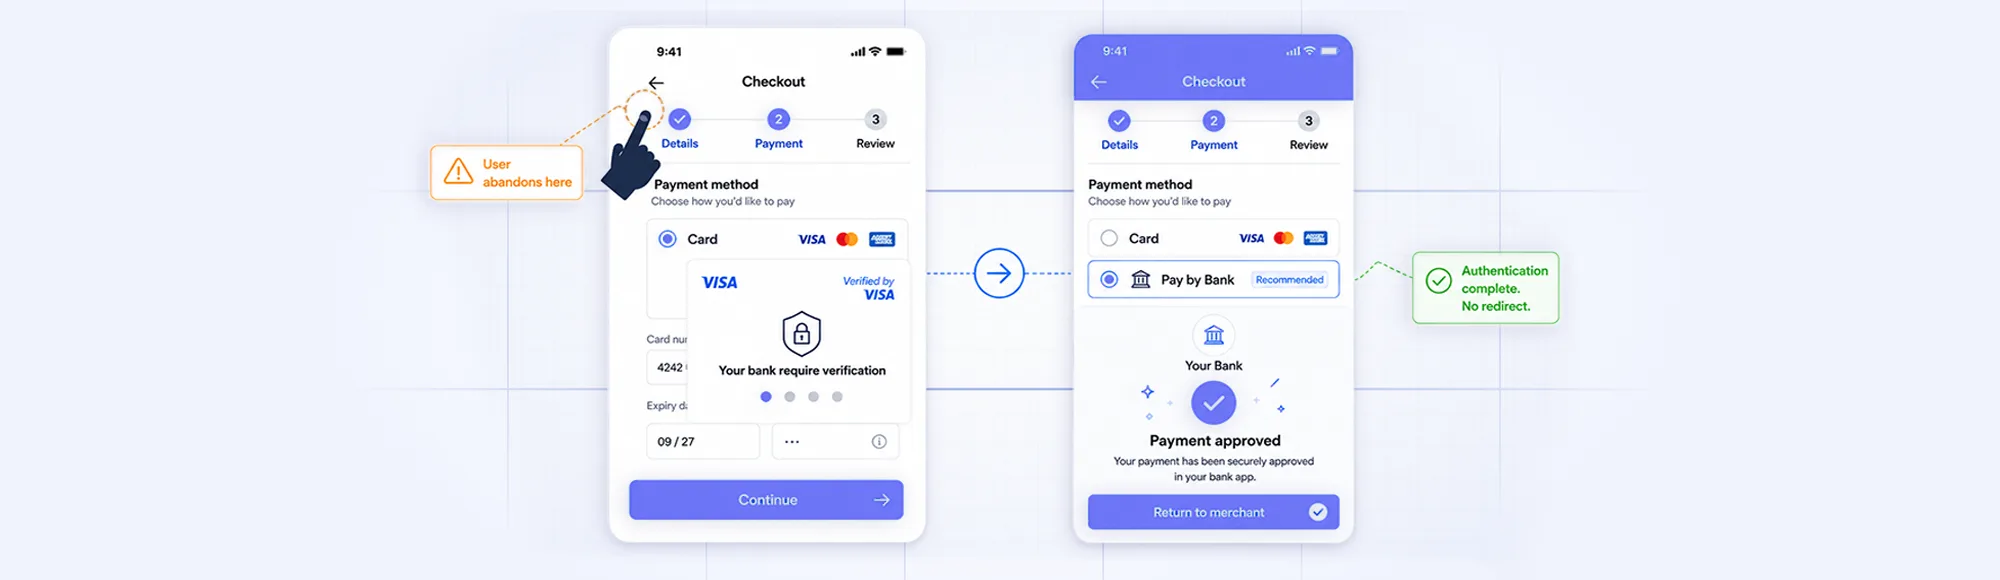
Checkout Abandonment Rate: Which Causes Pay by Bank Actually Fixes (And Which It Doesn’t)
Most UK platforms adding Pay by Bank expect their checkout abandonment rate to improve. Often it does not, because the cause sits entirely outside the payment step. This blog maps each Baymard-verified checkout abandonment reason to an honest answer: what Pay by Bank fixes at the payment step, and what requires a separate product decision.
5 Best Tenant Background Verification Tools in the UK (2026)
Get verified with Finexer Connect with 99% of UK Banks and Scale Your Business without Limits Try Now Letting property in the UK comes with rising risks: from missed payments to Right to Rent fines. That’s why more landlords are turning to tenant background verification tools, digital platforms that check a renter’s credit, employment, and […]
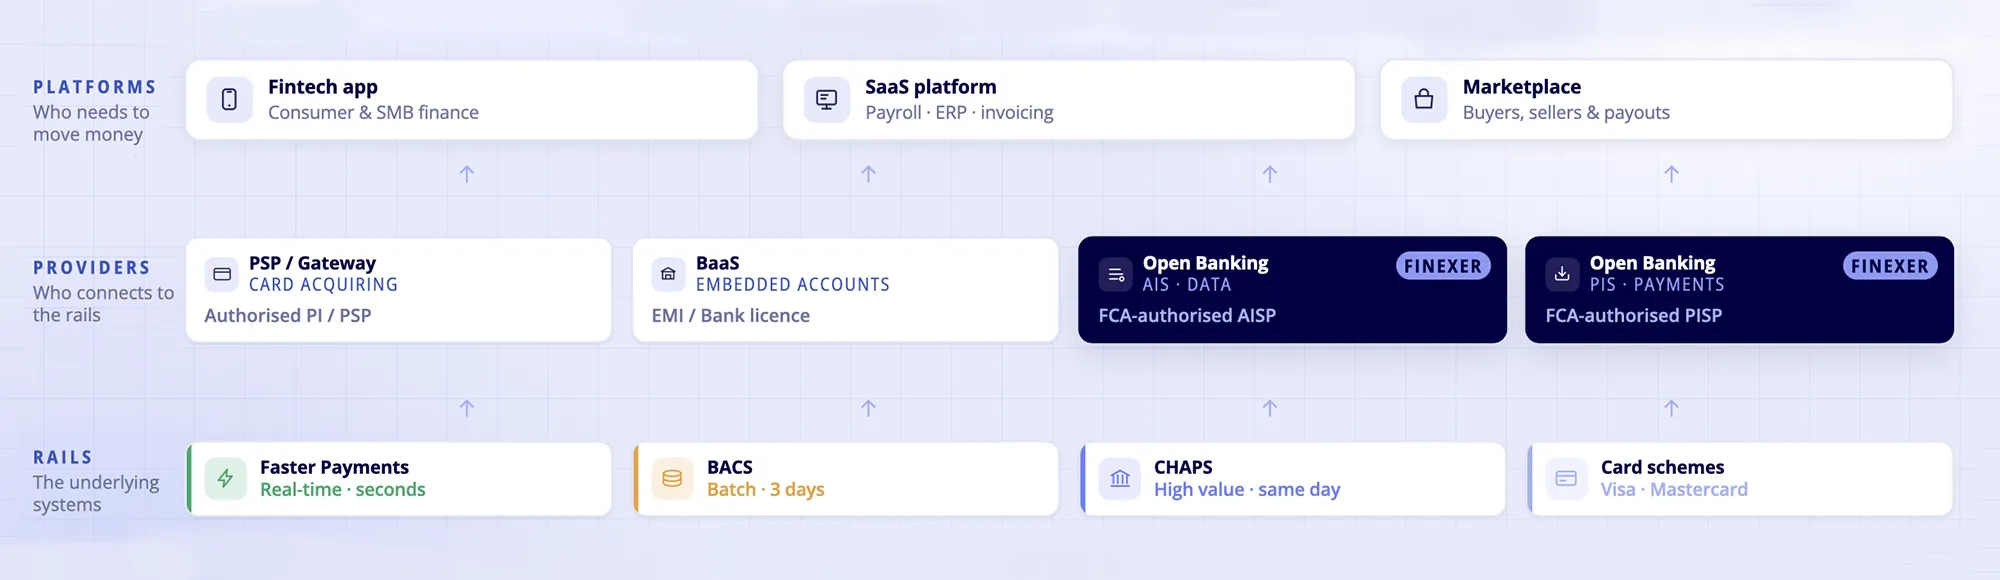
Payment Infrastructure UK: The Full Stack from Rails to Regulation
Every payment a platform processes touches infrastructure it did not build and regulation it did not choose. Understanding the UK payment infrastructure stack – the rails, the provider categories, and who regulates what – is the decision that shapes everything downstream: cost, speed, coverage, compliance, and how easily the stack can change when requirements do.
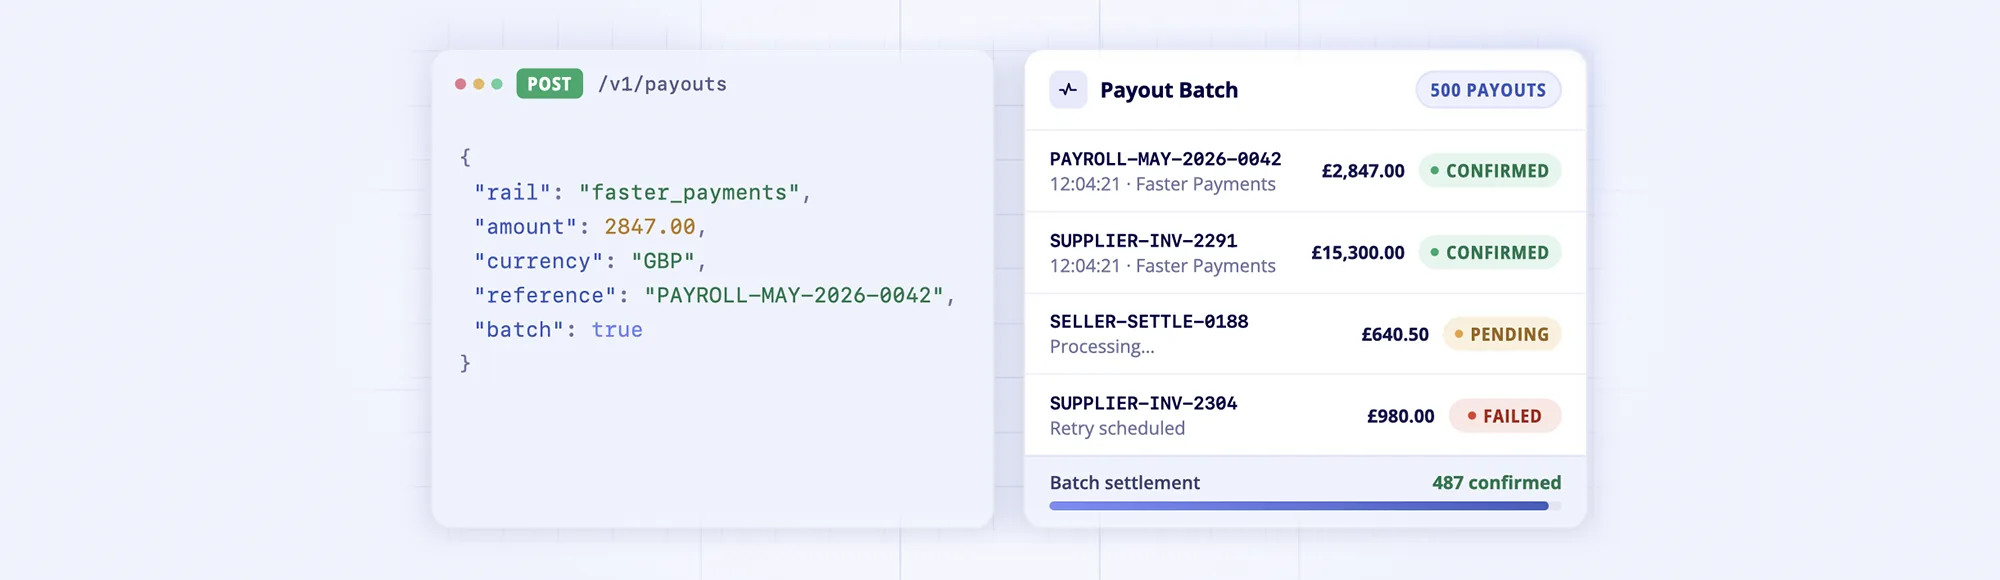
Global Payments API for UK Payout Infrastructure
A global payments API for UK platforms connects domestic GBP payout rails, international recipient disbursements and per-payout reconciliation into one infrastructure layer. This guide covers what rail-aware routing delivers, where Open Banking fits the UK payout stack, how Finexer International Payouts handles UK-origin outbound disbursements to recipients, and what to evaluate beyond the feature page.
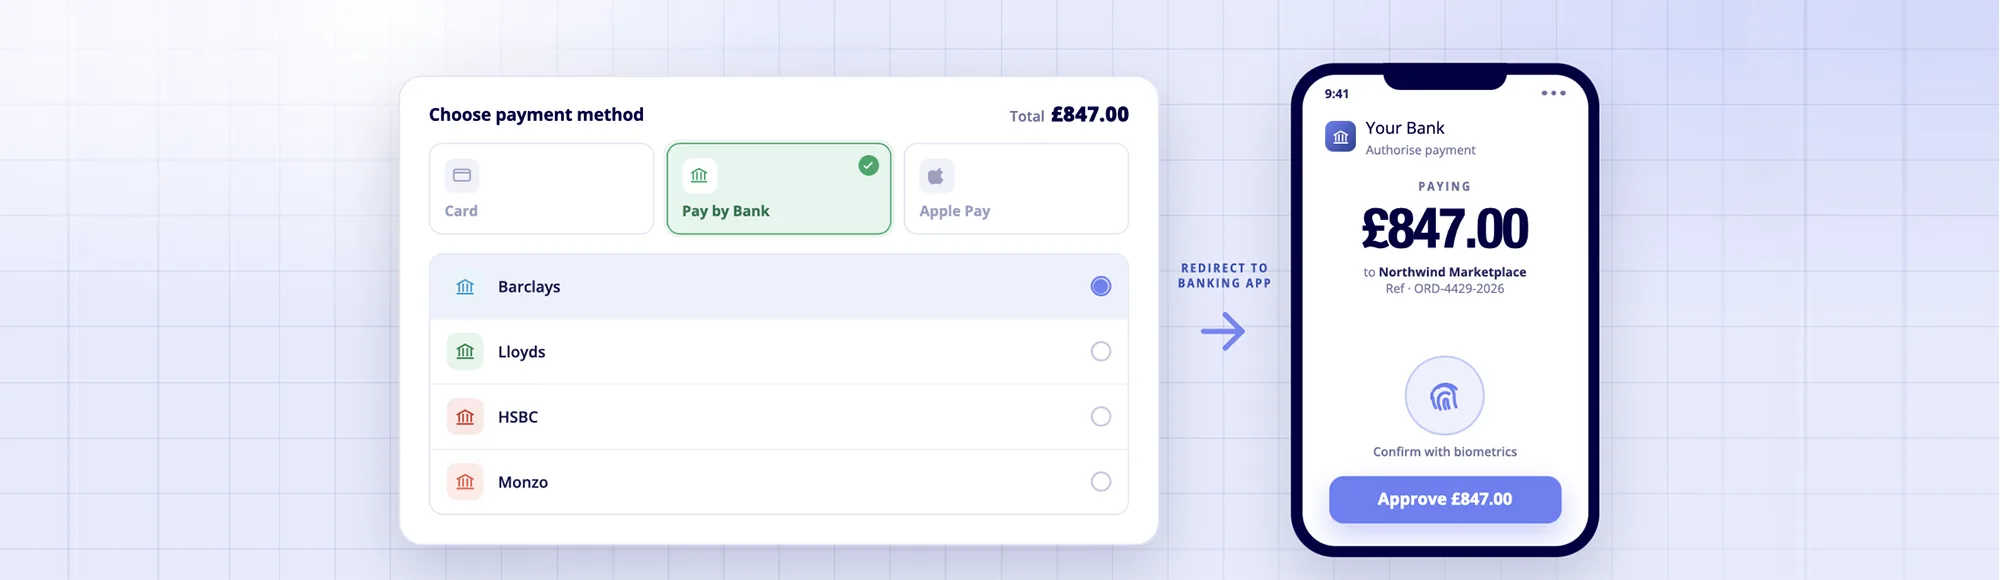
How to Add Pay by Bank Transfer to Your Platform Checkout
Card fees stack up. Checkout friction adds up. A growing share of UK buyers are now comfortable paying directly from their bank. Implementation playbook for platform teams adding pay by bank transfer as a checkout option – covering engineering scope, webhook handling, edge cases, and what this checkout option genuinely does and does not replace.
OpenPayd Pricing Guide [2026]: Real Costs of Using Open Banking APIs
Get Paid with Finexer Connect with 99% of UK Banks and Scale Your Business without Limits Contact Now All information in this article has been sourced from OpenPayd’s official website, announcements, and industry pricing benchmarks from Open Banking Tracker (2026). Pricing is custom and subject to change – figures cited reflect typical market ranges, not […]
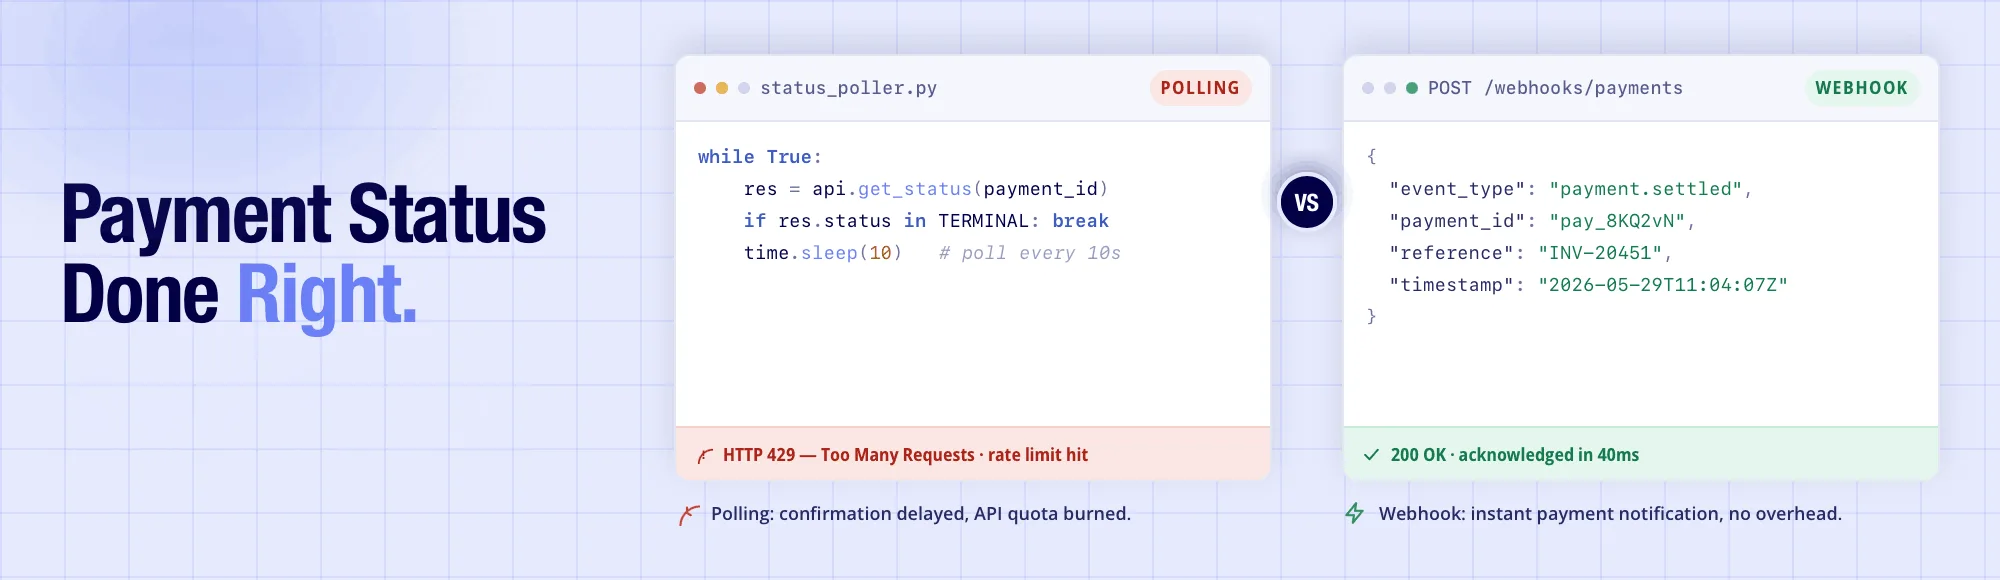
Payment Status Tracking: Webhooks vs Polling and the Open Banking Approach
Payment status is one of those things that looks simple until you are running payment workflows at volume on a UK platform. Polling creates rate limit pressure, confirmation delays, and reconciliation gaps that compound with scale. This is how webhooks, idempotency, and bank-confirmed instant payment notification change the operational picture for engineering and product teams.
How to Fix Data Inconsistencies in Simply Accounting for Good
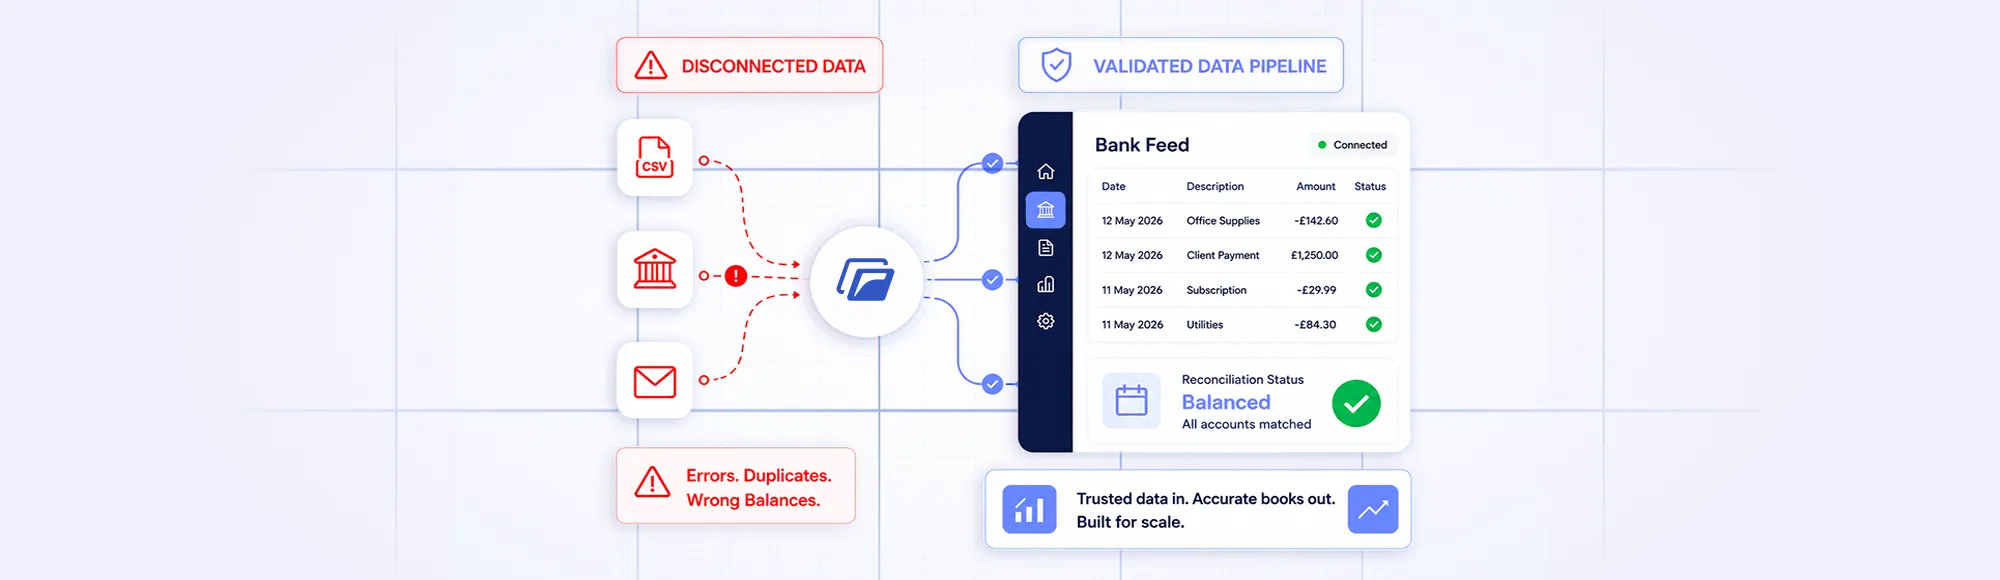
How to fix data inconsistencies in Simply Accounting is a question most finance teams answer with a repair tool. The inconsistency clears. It returns three weeks later. The repair addressed the symptom – not the import workflow that created it. What is breaking upstream and what changes the pattern permanently is what this blog examines.
Tenant Referencing Companies UK: Why Platforms Are Moving to Bank-Verified Workflows
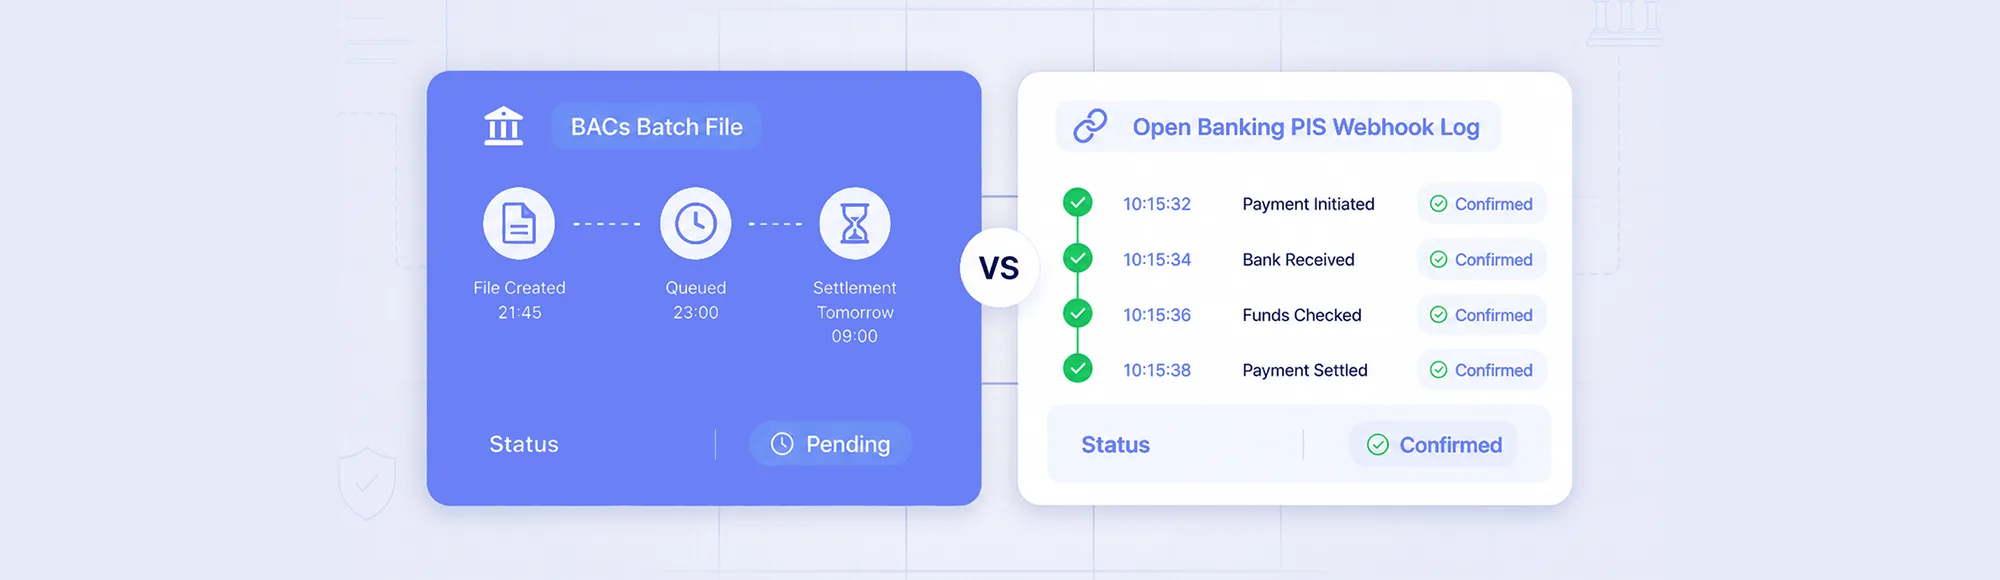
Tenant referencing platforms are switching from manual document collection to bank-verified income data. If your platform still runs on uploaded payslips and PDF bank statements, here is what the document fraud exposure looks like for your product, the workflow cost it creates, and what integrating Open Banking AIS into your tenant referencing stack actually changes.
Standard Bank Transaction Data Is the Foundation. Why Enrichment and Validation Both Matter.
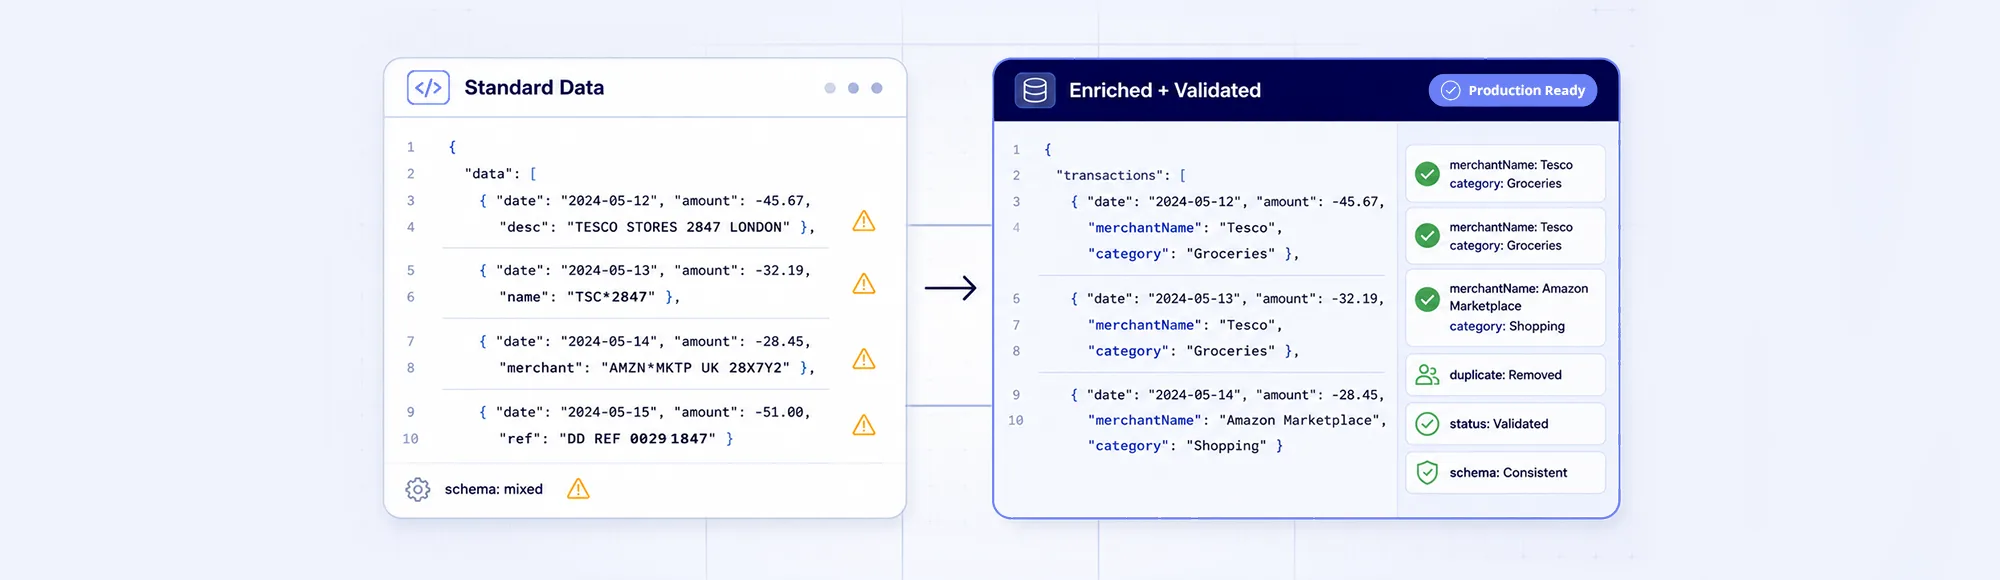
Standard bank transaction data gives platforms the foundation they need – account activity, balances, amounts, and payment references. Financial data enrichment adds merchant context and spending categories on top of that. But enrichment alone, without validation and verification of data, still breaks production workflows at scale. Both layers together determine whether financial automation holds up.
Why Automated Bank Feeds Still Fail in Production Accounting Workflows
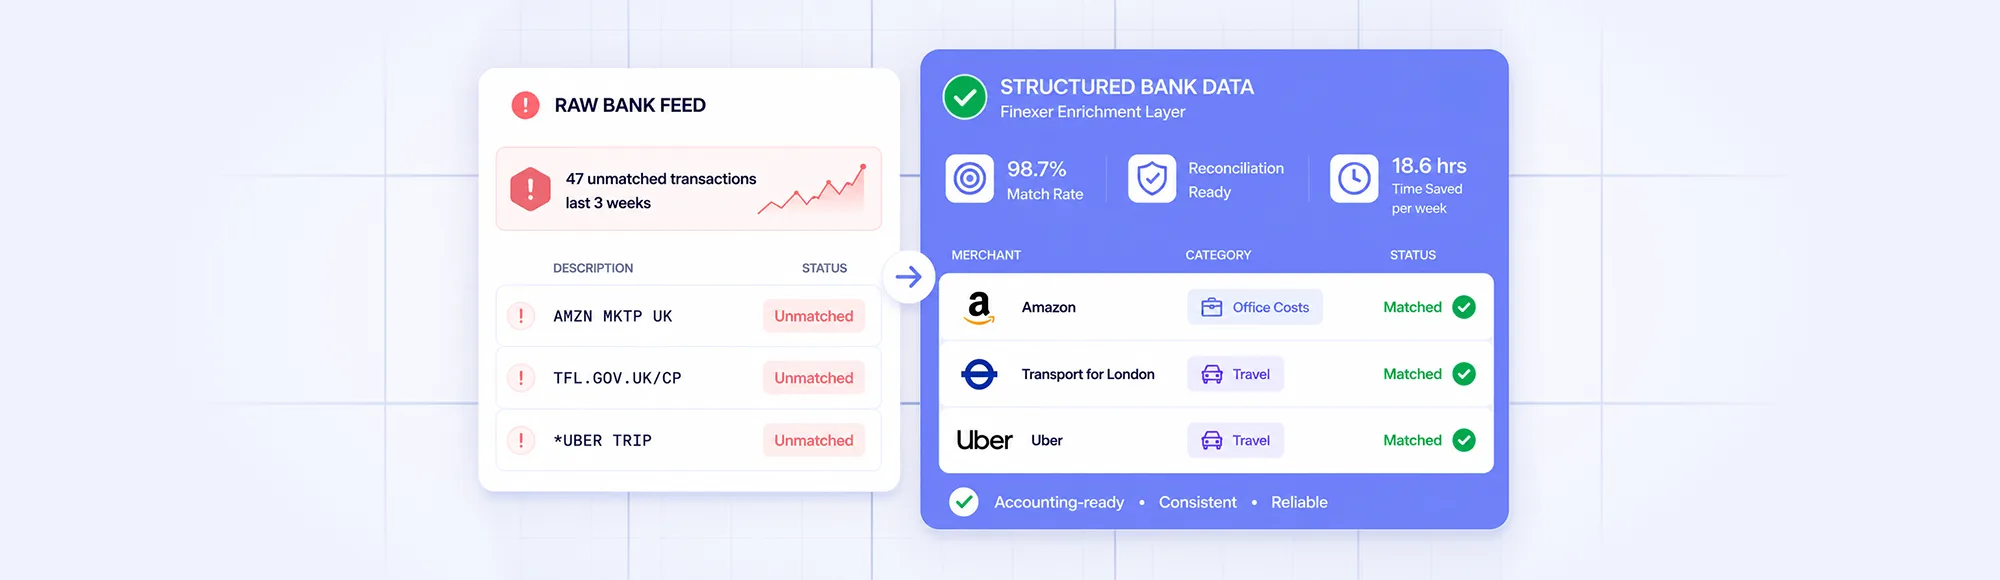
Automated bank feeds work in the development sandbox. They break in production. Inconsistent transaction formats, missing webhooks, and incomplete UK bank coverage all create the reconciliation failures accounting platforms discover only at month-end. This blog covers why automated bank feeds fail in real accounting workflows and what UK financial data infrastructure actually determines their reliability.
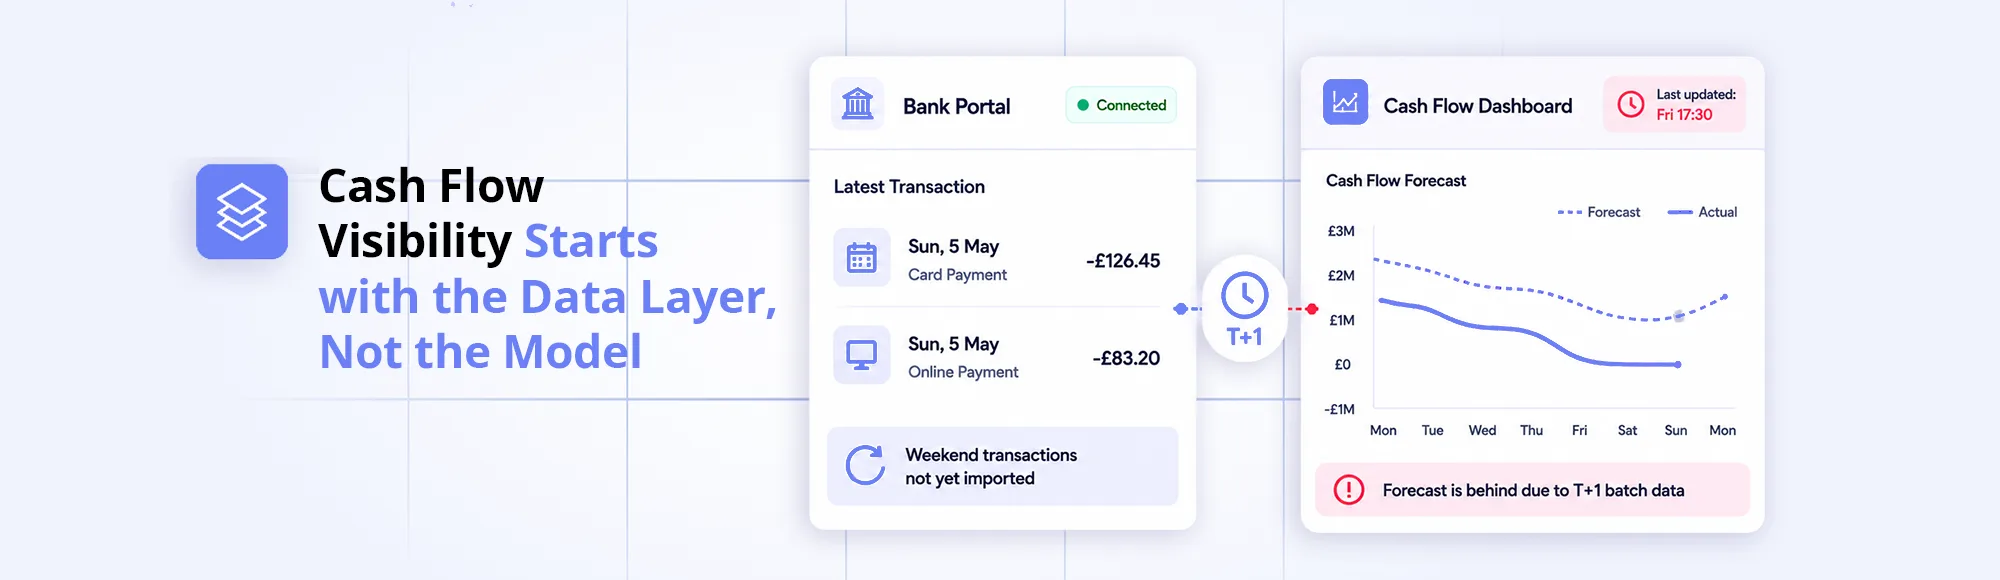
Why Most Businesses Still Struggle to Improve Cash Flow Visibility
Cash flow visibility fails when the data feeding it is delayed. A forecast built on yesterday’s bank statement is a reconstruction, not a real forecast. This blog covers why finance teams struggle to improve cash flow visibility, why forecast accuracy depends on connected financial data, and what changes when bank transaction data arrives near settlement.
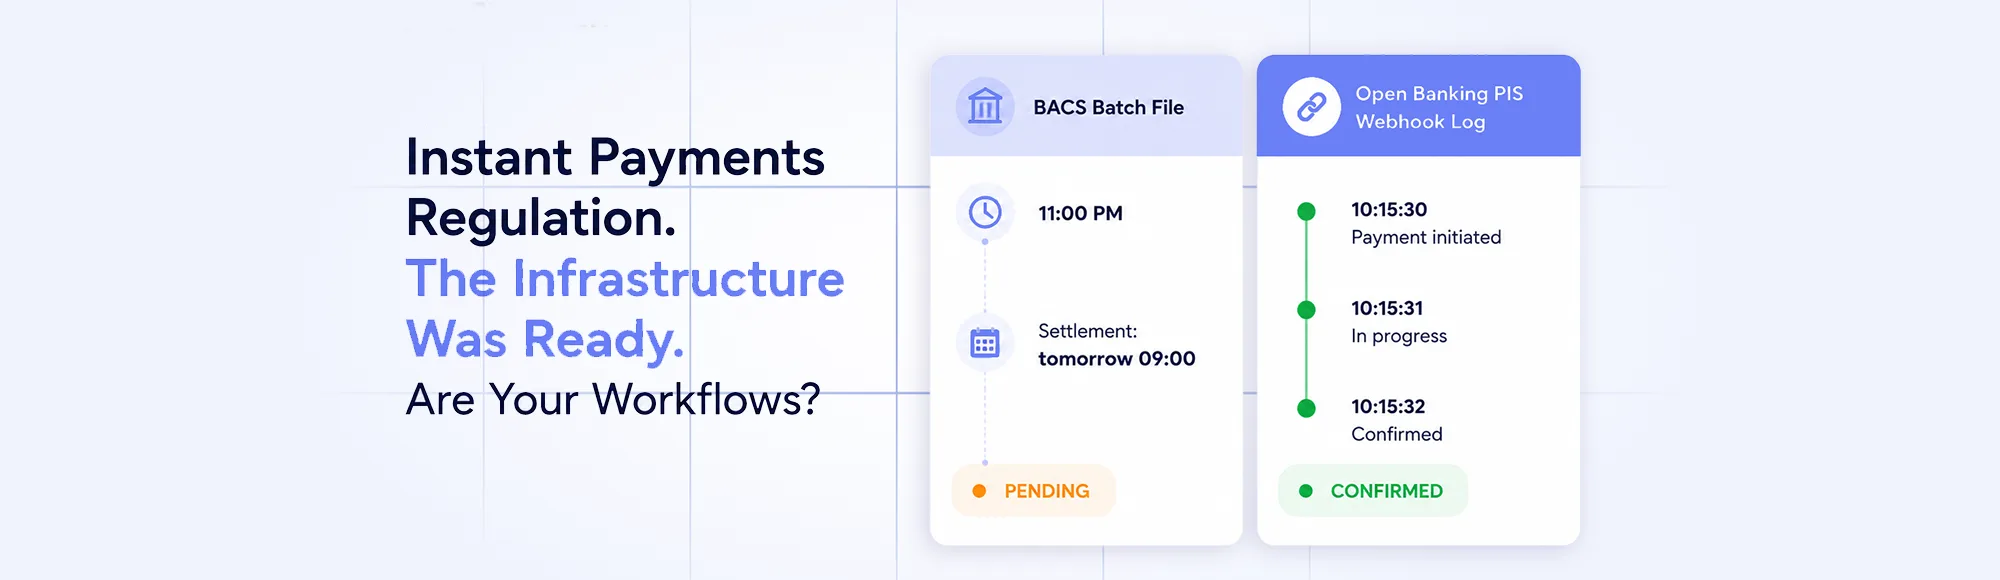
Why Instant Payments Regulation Is Changing More Than Just Speed
Instant payments regulation is not just a compliance update. It is changing the operational assumptions payment platforms, billing systems, and finance teams have built their workflows on. This blog covers what the EU Instant Payments Regulation means operationally, how the UK Faster Payments ecosystem compares, and what it means for platform payment infrastructure in 2026.
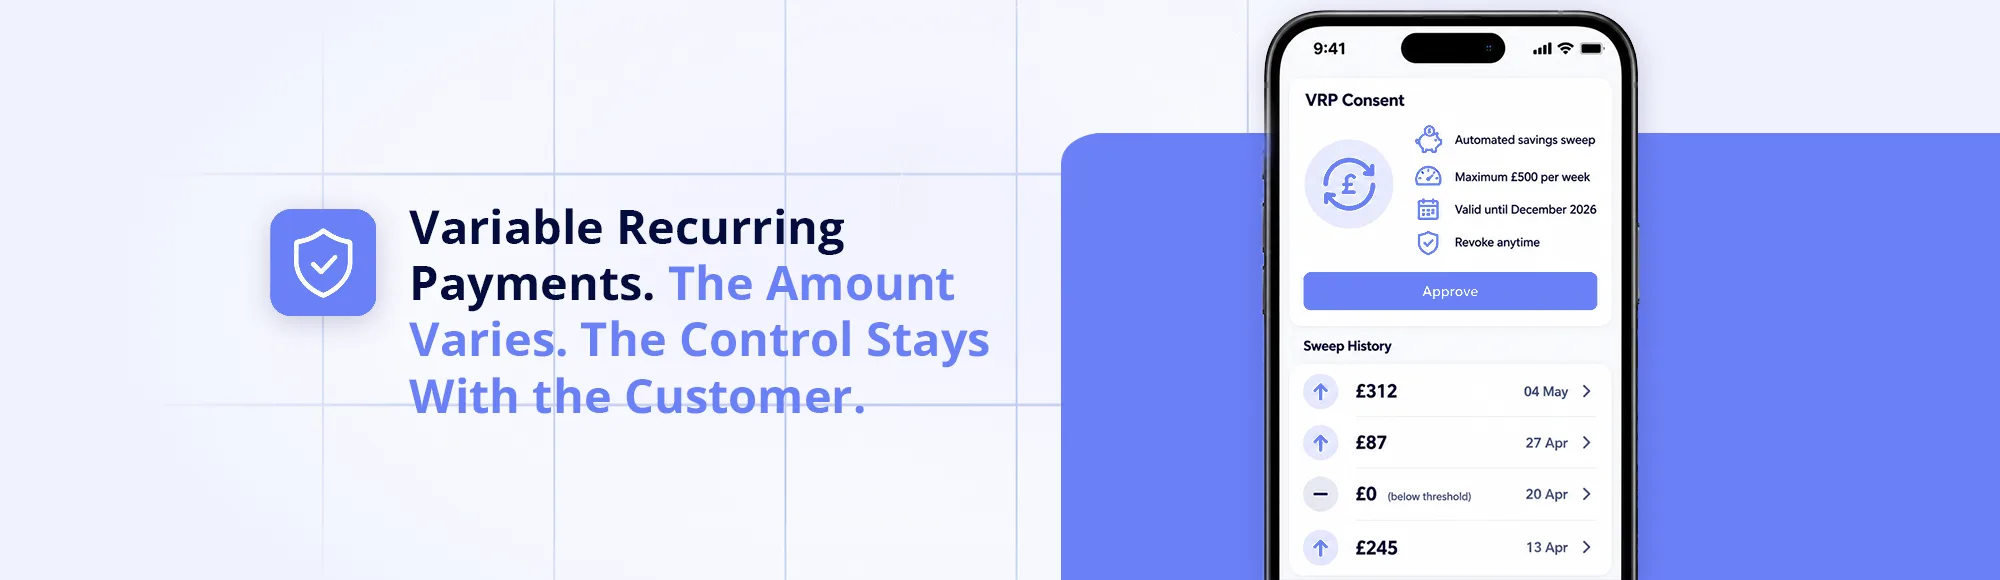
Variable Recurring Payments Open Banking Examples That Show Where Payments Are Heading
Variable recurring payments are described as a technical upgrade to Direct Debit. That undersells them. VRPs change who controls recurring payment amounts – shifting control from the business to the customer. This blog covers real Open Banking VRP examples across savings, utilities, lending, and subscriptions, and why VRPs matter for financial inclusion beyond flexible billing.
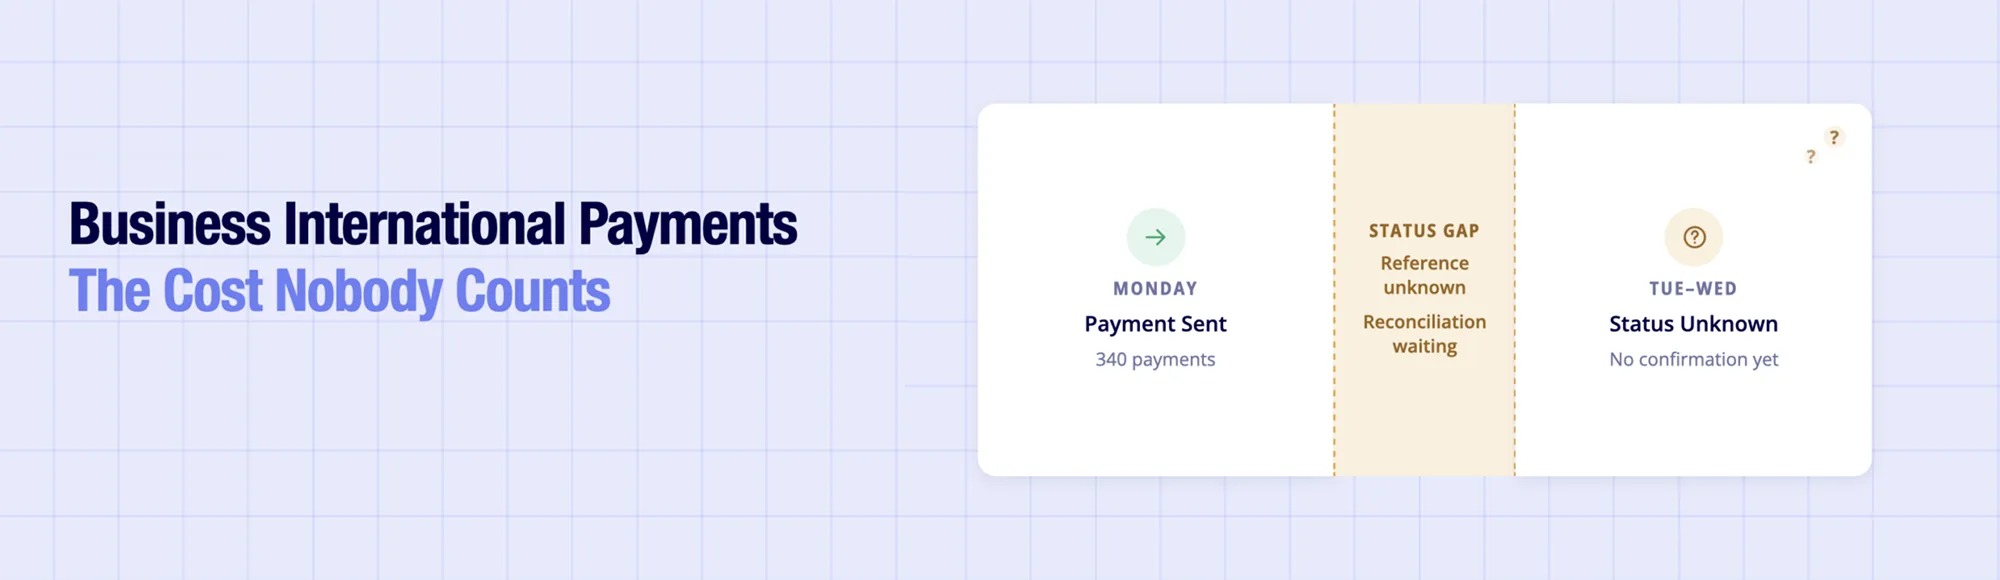
Business International Payments: The Hidden Operational Cost
Business international payments often stall not in transit but in confirmation, leaving finance teams chasing status, matching references, and reconciling manually. This guide breaks down where international business payments lose operational visibility and how per-payment webhook tracking, embedded references, and reconciliation-ready data close that gap for UK B2B platforms sending GBP-denominated payouts abroad.
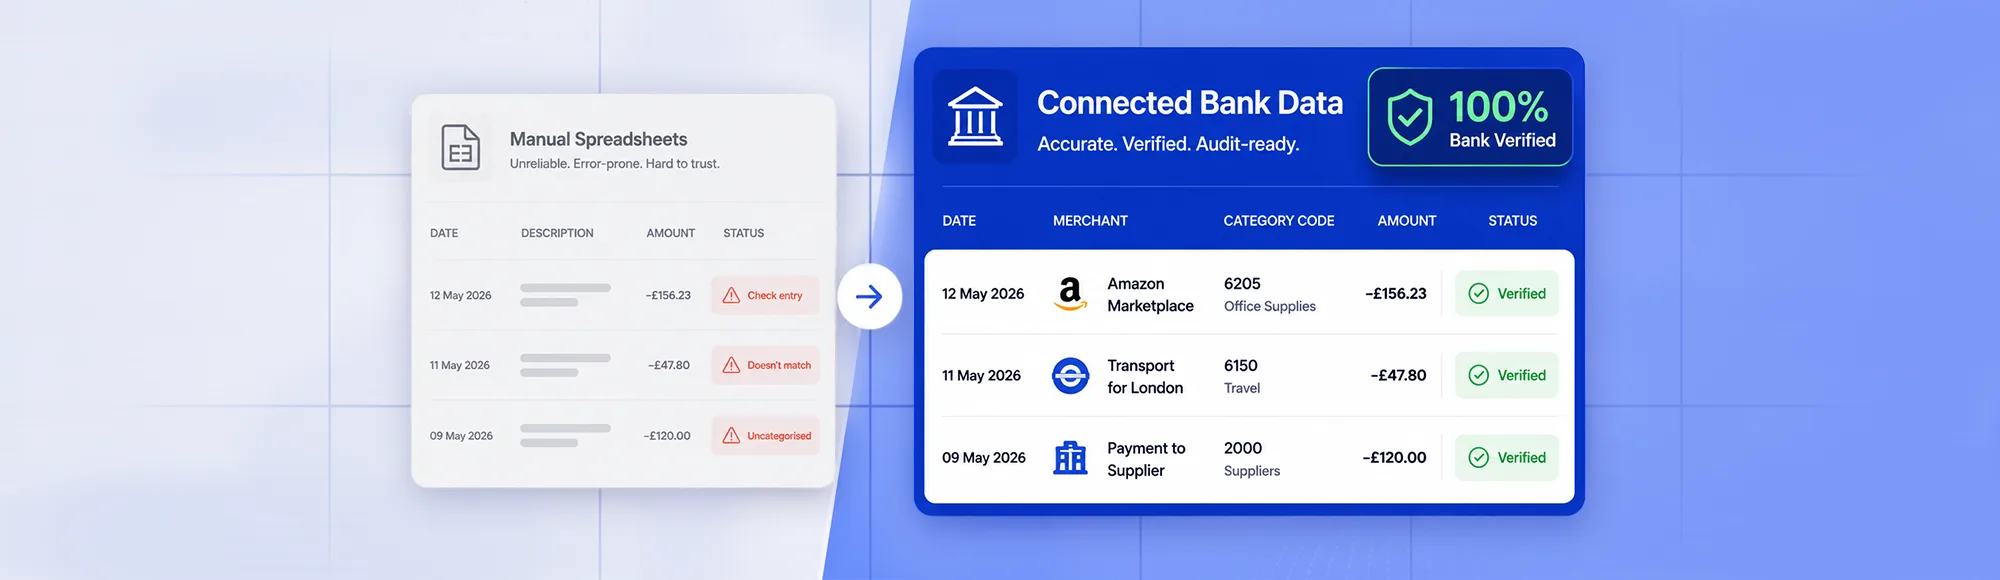
Why Is Accurate Record Keeping Important? The Operational Answer
Accurate record keeping matters for compliance. But that is only the start. Finance teams that struggle at month-end or fail audits almost always share the same root problem: transaction data that is incomplete, delayed, or manually entered. This blog covers why keeping financial records accurately is an operational issue – not just a regulatory one.
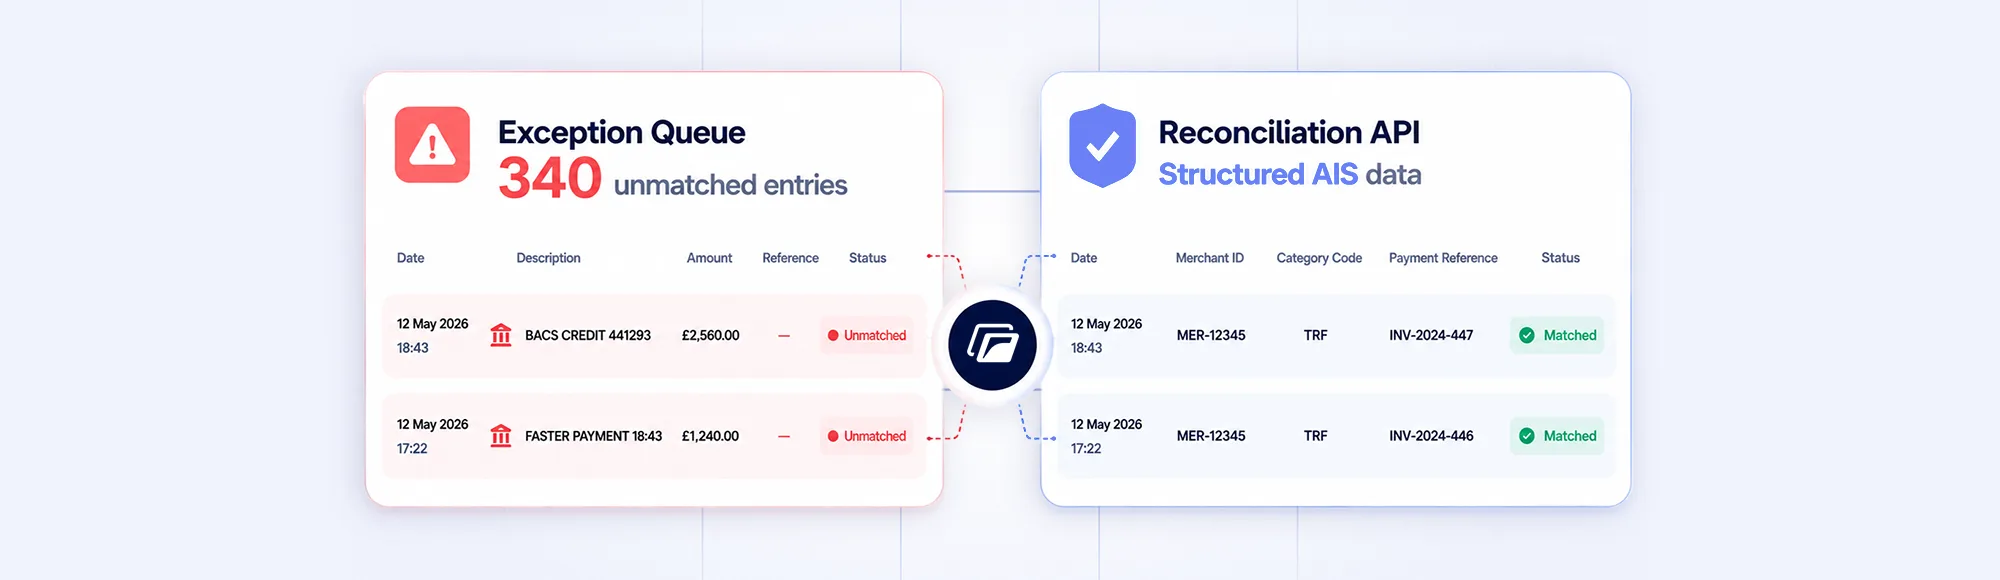
Why Accurate Reconciliation Depends on Better Reconciliation API Infrastructure
Most reconciliation API failures are not algorithm failures. They are data failures. The matching logic works. The bank transaction data feeding it is delayed, generic, or disconnected from the payment that triggered it. This blog covers why accurate reconciliation depends on infrastructure-level data connectivity, and what a reconciliation API needs to do beyond transaction matching.

What the HMRC Expenses List Gets Wrong About How Businesses Actually Track Costs
The HMRC expenses list tells businesses what to claim. It does not tell them how to track those claims accurately. For accounting SaaS, ERP systems, and expense management tools, that gap is where compliance breaks down. This blog covers the HMRC expense categories, where tracking fails in practice, and how structured bank data changes it.

Why Multi-Bank Connectivity Still Breaks in Modern Finance Stacks
Multi-bank connectivity sounds like a solved problem. Connect the right APIs and unified bank access should follow. In practice, each bank behaves differently. APIs time out at different rates. Data formats vary. Consent cycles expire at different intervals. This blog covers why fragmented bank integrations create operational problems and what reliable multi-bank infrastructure actually requires.
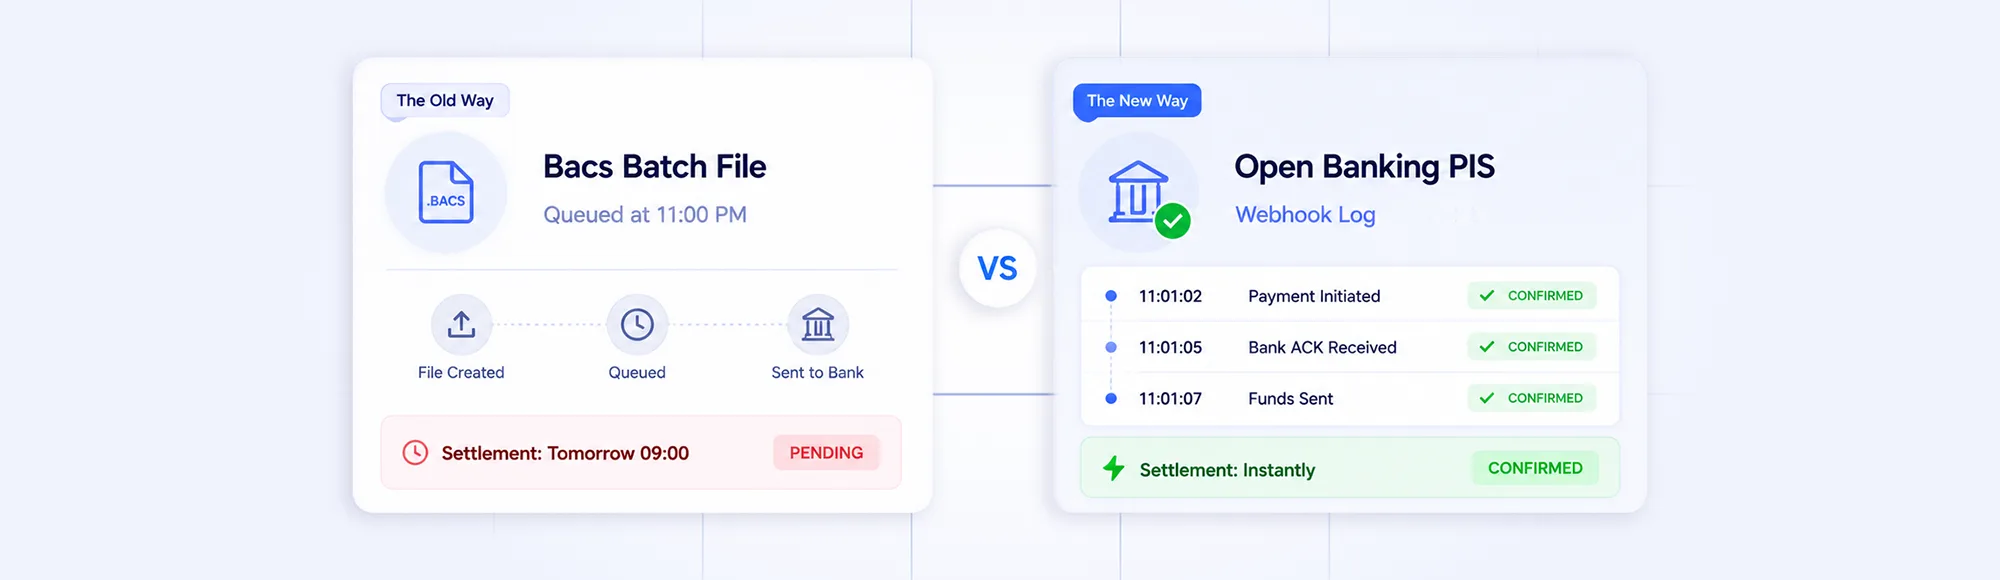
Best Payroll System UK 2026: 6 Options for Accounting Firms
Payroll system UK comparisons usually stop at RTI compliance and feature lists. The differences that matter for accounting firms in 2026 are multi-client bureau scale, cloud migration readiness, accounting integrations, and whether payroll services disburse salaries on the same day or wait three business days for BACS. This review covers all six on those criteria.

Why Payment Tracking Still Breaks in Modern Financial Workflows
Payment tracking sounds like a solved problem. Most platforms have a status page. Most finance teams have a spreadsheet. Neither tells you what happened at the bank. This blog covers why payment tracking breaks operationally, what online payment tracking requires beyond status updates, and how connecting payment initiation to bank transaction data changes the workflow.

Payment Gateway vs PSP vs Payment Processor: What UK Businesses Actually Need to Know
Most businesses asking about payment gateways are really asking one question: which do I actually need? This guide explains what a payment gateway does, how it differs from a PSP and payment processor, and when the payment gateway vs PSP debate matters less than you think because Open Banking changes the decision for UK platforms.

Data Security in Financial Services Begins Before the Database
Data security in financial services is not just about where data is stored – it is about how it enters the platform. Manual bank statements introduce fraud risk, integrity gaps, and compliance exposure that encrypted storage cannot fix. This blog covers what secure bank data access requires and how Open Banking APIs change the risk.

Open Banking Referencing: Reliable Tenant Verification for PropTech Platforms
Open banking referencing replaces manually submitted statements with verified data from the bank. Payslip fraud makes up over half of tenancy fraud – and AI fakes take minutes to create. This blog covers how open banking for referencing works at the platform level, and what PropTech and letting agent platforms need to build it reliably.